|
시장보고서
상품코드
2122656
파워 반도체 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Power Semiconductor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
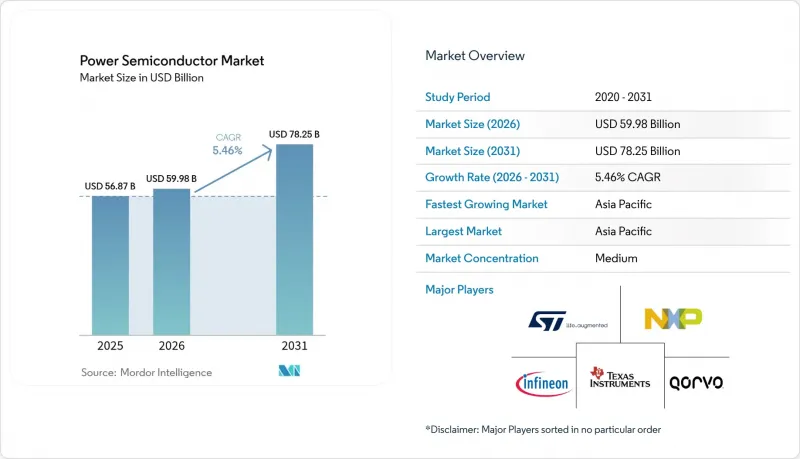
에 의하면, 파워 반도체 시장 규모는 2025년에 568억 7,000만 달러로 평가되었고, 2026년 599억 8,000만 달러에서 2031년까지 782억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.46%를 나타낼 전망입니다.
본 보고서는 부품별(디스크리트, 모듈, 파워 IC), 소재별(실리콘, 실리콘 카바이드, 갈륨 나이탈리아드, 기타), 최종 사용자 산업별(자동차, 가정용 전자기기·가전, ICT, 산업 및 제조, 에너지 및 전력, 항공우주 및 방위, 의료·의료기기, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 파워 반도체 시장 동향 및 인사이트
전기차(EV) 및 충전 인프라에 대한 수요 급증
전기차(EV)에서는 구동계의 효율을 높이고 충전 시간을 단축하기 위해 SiC MOSFET에 대한 의존도가 높아지고 있습니다. 800V 시스템으로의 전환을 추진하는 자동차 제조업체들은 인버터의 손실을 줄이기 위해 SiC를 지정하고 있으며, 온세미컨덕터와 폭스바겐의 계약과 같은 FORVIA(공급 보장 계약)가 칩에서 모듈에 이르기까지 수직 통합된 안정적인 공급을 확보하고 할당 위험을 경감시키고 있다는 점이 그 증거입니다. 병렬 DC 급속 충전기의 도입에는 8kW에서 1MW의 파워 블록이 필요하며, 이로 인해 차량 탑재분만으로도 SiC 수요가 실질적으로 두 배로 증가하게 됩니다. 자동차 등급 제품의 수율은 여전히 과제로 남아 있기 때문에 각 IDM 기업들은 자사 내 기판 생산 능력을 증강하여 비용 곡선을 안정화하고 이익률을 확보하고 있습니다.
5G 기지국의 보급
GaN 고전자이동도 트랜지스터는 6GHz 미만 및 밀리파 주파수 대역에서 LDMOS보다 높은 이득과 효율을 실현합니다. 통신 사업자들이 치솟는 에너지 비용을 해결해 나가는 가운데, 스몰 셀의 고밀도화로 인해 GaN 출하량은 2010년 말까지 4배 증가할 것으로 예측됩니다. NXP는 Si LDMOS와 GaN 다이를 결합한 멀티칩 매시브 MIMO 모듈을 제공하고 있으며, 이를 통해 안테나 어레이가 통합되고 열 설계가 단순화됩니다. 파워 반도체 공급업체들은 225°C를 초과하는 핫스팟 온도에 대응하기 위해 소결형 다이 부착 재료를 채택하고 있습니다. 통신 업계가 총소유비용(TCO)을 중시하는 가운데, 효율의 점진적인 향상이 운영비용(OPEX) 절감으로 이어지면서 다음 단계의 전개에서 GaN의 채택이 정착되고 있습니다.
실리콘 웨이퍼 공급 부족의 주기
웨이퍼의 총 수요는 현재 인증된 생산 능력을 초과하고 있으며, 메모리 공급업체의 재고 감축이 단기적인 구매 행태에 왜곡을 초래하고 있습니다. 지정학적 마찰로 인해 팹 건설 비용이 증가하는 한편, 물 사용 제한으로 인해 가뭄이 발생하기 쉬운 지역에서의 신규 부지 확보가 제한되고 있습니다. 중국에서 신규 진입한 기업들이 가격 경쟁을 펼치고 있어, 공급망 전체의 이익률이 압박받고 있습니다. 프런트엔드 설비 수주는 회복 조짐을 보이고 있지만, PC나 스마트폰과 같은 최종 시장의 침체로 인해 생산량 회복은 더딘 상태이며, 이는 경기 순환적인 불균형이라기보다는 구조적인 불균형을 드러내고 있습니다.
부문별 분석
파워 IC는 2025년 파워 반도체 시장 규모에 크게 기여하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.02%로 성장할 전망입니다. 자동차 배터리 관리 장치(BMAU)에는 콤팩트한 PMIC 실적로 구현되는 멀티레일 레귤레이터 및 기능 안전 진단 기능이 요구되고 있습니다. 인피니언의 ISO 26262 준수 제품인 ‘OPTIREG TLF35585’는 안전 관련 전자 제어 장치를 뒷받침하며, 싱글 칩 파워 매니지먼트의 동향을 보여주고 있습니다. 대전류 경로에서는 여전히 디스크리트 소자가 필수적이며, 매출 점유율 44.60%를 유지하고 있습니다. 그러나 공간 제약이 있는 서브시스템에서 설계자들이 비용 최적화된 모듈이나 IC 솔루션을 선호하는 추세가 있어, 디스크리트 소자의 점유율은 서서히 감소하고 있습니다.
공급업체의 로드맵에서는 게이트 구동, 센싱, 보호 기능을 통합한 지능형 파워 모듈 내에 GaN 또는 SiC 다이를 탑재하고 있으며, 이를 통해 인버터 및 충전기 어셈블리 시장 출시 기간을 단축하고 있습니다. 모듈의 통합은 사내에 패키징 전문 지식이 없는 중규모 산업용 및 주거용 에너지 고객에게 이점이 됩니다. 한편, 소비자용 전자기기 ODM 업체들은 기판 수준의 유연성과 가격적 이점을 활용하기 위해 어댑터 설계에 여전히 디스크리트 MOSFET을 조달하고 있습니다. 디스크리트, 모듈, IC의 각 형태가 공존함으로써 파워 반도체 시장은 더욱 풍요로워지며, 성능과 비용의 최적의 균형을 실현할 수 있게 됩니다.
지역별 분석
2025년, 아시아태평양은 파워 반도체 시장 점유율의 51.35%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.74%를 유지할 전망입니다. 중국은 국가 보조금과 수직 통합된 공급망에 힘입어 SiC 및 GaN 생산 능력 확대를 주도하고 있습니다. 인도는 하루 1,500만 개를 목표로 하는 7,600카롤 루피 규모의 OSAT 캠퍼스 건설을 급속도로 추진하고 있으며, 조립 공정의 국내 복귀를 도모할 의향을 보이고 있습니다. 대만과 한국은 각각 첨단 패키징 및 메모리 분야에서 리더십을 계속 유지하고 있으며, 일본은 업스트림 소재 분야에서 주도권을 강화하고 있습니다.
북미는 ‘CHIPS 법’에 따른 500억 달러 규모의 장려 조치의 혜택을 받고 있으며, 이를 통해 Wolfspeed, Bosch 및 해외 신규 진출기업들의 기존 공장 전환과 신규 팹 건설이 촉진되고 있습니다. 자동차, 방위, 데이터센터 각 클러스터가 수요를 집중시키며 현지 조달 요건을 뒷받침하고 있습니다. SEMI는 2027년까지 해당 지역의 팹 설비 투자액이 2배인 247억 달러에 달할 것으로 예측하며, 장기적인 규모 확대를 뒷받침하고 있습니다.
유럽은 자동차 및 재생 에너지 정책의 일관성을 활용하여 SiC 및 GaN의 보급을 촉진하고 있습니다. 독일에서 승인된 50억 유로 규모의 드레스덴 공장은 자급률 향상을 위한 민관 협력의 좋은 사례입니다. 프랑스와 이탈리아는 최첨단 모듈 및 기판에 관한 노하우를 유지하기 위해 추가적인 보조금 패키지를 제공합니다. 중동 및 아프리카, 라틴아메리카의 신흥 시장에서는 여전히 비용에 대한 민감도가 높아, 성숙한 실리콘 플랫폼을 채택하는 한편, 유틸리티 규모의 태양광 발전 및 철도 전철화를 위해 WBG를 단계적으로 시범 도입하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the power semiconductor market size was valued at USD 56.87 billion in 2025 and estimated to grow from USD 59.98 billion in 2026 to reach USD 78.25 billion by 2031, at a CAGR of 5.46% during the forecast period (2026-2031).

This report is Segmented by Component (Discrete, Modules, Power IC), Material (Silicon, Silicon Carbide, Gallium Nitride, Others), End-User Industry (Automotive, Consumer Electronics and Appliances, ICT, Industrial and Manufacturing, Energy and Power, Aerospace and Defense, Healthcare and Equipment, Others), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Power Semiconductor Market Trends and Insights
Surging Demand for EVs and Charging Infrastructure
Electric vehicles increasingly rely on SiC MOSFETs that raise drivetrain efficiency and shorten charging times. Automakers shifting to 800 V systems specify SiC to trim inverter losses, evidenced by FORVIAs, such as onsemi's agreement with Volkswagen, secure vertically integrated chip-to-module deliveries, mitigating allocation risks. Parallel DC fast-charger roll-outs require 8 kW to 1 MW power blocks, effectively doubling SiC demand from vehicle content alone. Automotive-grade yields stay challenging, so IDMs add captive substrate capacity to stabilize cost curves and safeguard margins.
Proliferation of 5G Base-Stations
GaN high-electron-mobility transistors deliver higher gain and efficiency than LDMOS at sub-6 GHz and mmWave frequencies. Small-cell densification pushes GaN shipments to quadruple by decade-end as operators combat escalating energy bills. NXP couples Si LDMOS with GaN die in multichip massive-MIMO modules that integrate antenna arrays and simplify thermal design. Power semiconductor suppliers add sintered die-attach materials to cope with hot-spot temperatures above 225 °C. The telecom sector's focus on total-cost-of-ownership converts incremental efficiency gains into reduced opex, cementing GaN adoption in next-phase rollouts.
Silicon Wafer Supply Tightness Cycles
Total wafer demand now eclipses qualified capacity, and inventory drawdown at memory suppliers distorts short-term purchasing behavior . Geopolitical friction inflates fab-construction costs, while water-usage limits restrict greenfield sites in drought-prone zones. Chinese entrants pursue price competition that compresses margins across the chain. Although front-end equipment bookings hint at recovery, end-market weakness in PCs and smartphones tempers volume pick-up, exposing structural rather than cyclical imbalances.
Other drivers and restraints analyzed in the detailed report include:
- Renewables-Led Power Conversion Growth
- Industrial Automation and Motor-Drive Upgrades
- High Cost / Design Complexity of WBG Devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Power integrated circuits contributed significantly to the power semiconductor market size in 2025 and will climb at a 6.02% CAGR through 2031. Automotive battery-management units require multi-rail regulators and functional-safety diagnostics delivered in a compact PMIC footprint. Infineon's ISO 26262-compliant OPTIREG TLF35585 underpins safety-related electronic control units, illustrating the trend toward single-chip power management . Discrete devices remain indispensable for high-current paths, preserving 44.60% revenue share; nevertheless, the discrete share edges lower as designers favor cost-optimized module or IC solutions in space-constrained subsystems.
Supplier roadmaps bundle GaN or SiC dies within intelligent power modules that integrate gate drive, sensing, and protection, shortening time-to-market for inverter and charger assemblies. Module consolidation benefits mid-volume industrial and residential energy customers who lack in-house packaging expertise. Conversely, consumer-electronics ODMs still procure discrete MOSFETs for adapter designs to exploit board-level flexibility and price advantages. The coexistence of discrete, module, and IC formats enriches the power semiconductor market, enabling tailored performance-cost trade-offs.
Complete Report Scope:
- By Component
- Discrete
- Rectifier
- Bipolar
- MOSFET
- IGBT
- Other Discrete Components (Thyristor, HEMT, etc.)
- Modules
- Thyristor Module
- IGBT Module
- MOSFET Module
- Intelligent Power Module (IPM)
- Power IC
- PMIC (Multichannel)
- Switching Regulators (AC/DC, DC/DC, Iso/Non-iso)
- Linear Regulators
- Battery Management IC
- Other Power ICs
- Discrete
- By Material
- Silicon
- Silicon Carbide (SiC)
- Gallium Nitride (GaN)
- Others
- By End-user Industry
- Automotive
- Consumer Electronics and Appliances
- ICT (IT and Telecom)
- Industrial and Manufacturing
- Energy and Power (Renewables, Grid)
- Aerospace and Defense
- Healthcare Equipment
- Others (Rail, Marine)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia Pacific accounted for 51.35% of the power semiconductor market share in 2025 and sustained a 6.74% CAGR through 2031. China spearheads SiC and GaN capacity ramps, aided by state subsidies and vertically integrated supply chains. India fast-tracks an INR 7,600 crore OSAT campus targeting 15 million units per day, signaling intent to onshore assembly. Taiwan and South Korea guard leadership in advanced packaging and memory, respectively, while Japan fortifies upstream materials command.
North America benefits from USD 50 billion in CHIPS Act incentives that unlock brownfield conversions and greenfield fabs by Wolfspeed, Bosch, and overseas entrants. Automotive, defense, and data-center clusters concentrate demand, boosting local content requirements. SEMI projects regional fab-equipment outlays doubling to USD 24.7 billion by 2027, underscoring long-term scale-up .
Europe leverages its automotive and renewable energy policy alignment to catalyze SiC and GaN uptake. Germany's EUR 5 billion Dresden fab approval exemplifies public-private alignment to elevate self-sufficiency. France and Italy offer additional grant packages to preserve leading-edge module and substrate know-how. Emerging markets across the Middle East, Africa, and Latin America stay value-conscious, adopting mature silicon platforms while gradually trialing WBG for utility-scale solar and railway electrification.
- Infineon Technologies AG
- Texas Instruments Incorporated
- Qorvo Inc.
- STMicroelectronics N.V.
- NXP Semiconductors N.V.
- ON Semiconductor Corporation
- Renesas Electronics Corporation
- Broadcom Inc.
- Toshiba Corporation
- Mitsubishi Electric Corporation
- Fuji Electric Co., Ltd.
- Semikron Danfoss GmbH and Co. KG
- Wolfspeed Inc.
- ROHM Co., Ltd.
- Vishay Intertechnology Inc.
- Nexperia B.V.
- Alpha and Omega Semiconductor Ltd.
- Magnachip Semiconductor Corp.
- Microchip Technology Inc.
- Littelfuse Inc.
- Navitas Semiconductor Corp.
- Power Integrations Inc.
- Monolithic Power Systems Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for EVs and charging infrastructure
- 4.2.2 Proliferation of 5G base-stations
- 4.2.3 Renewables-led power conversion growth
- 4.2.4 Industrial automation and motor-drive upgrades
- 4.2.5 HAPS and all-electric aircraft powertrains
- 4.2.6 Fast-charging 2-/3-wheeler EV architectures in Asia
- 4.3 Market Restraints
- 4.3.1 Silicon wafer supply tightness cycles
- 4.3.2 High cost / design complexity of WBG devices
- 4.3.3 Thermal limits in high-density EV inverters
- 4.3.4 Export controls on GaN epitaxy tools
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Discrete
- 5.1.1.1 Rectifier
- 5.1.1.2 Bipolar
- 5.1.1.3 MOSFET
- 5.1.1.4 IGBT
- 5.1.1.5 Other Discrete Components (Thyristor, HEMT, etc.)
- 5.1.2 Modules
- 5.1.2.1 Thyristor Module
- 5.1.2.2 IGBT Module
- 5.1.2.3 MOSFET Module
- 5.1.2.4 Intelligent Power Module (IPM)
- 5.1.3 Power IC
- 5.1.3.1 PMIC (Multichannel)
- 5.1.3.2 Switching Regulators (AC/DC, DC/DC, Iso/Non-iso)
- 5.1.3.3 Linear Regulators
- 5.1.3.4 Battery Management IC
- 5.1.3.5 Other Power ICs
- 5.1.1 Discrete
- 5.2 By Material
- 5.2.1 Silicon
- 5.2.2 Silicon Carbide (SiC)
- 5.2.3 Gallium Nitride (GaN)
- 5.2.4 Others
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Consumer Electronics and Appliances
- 5.3.3 ICT (IT and Telecom)
- 5.3.4 Industrial and Manufacturing
- 5.3.5 Energy and Power (Renewables, Grid)
- 5.3.6 Aerospace and Defense
- 5.3.7 Healthcare Equipment
- 5.3.8 Others (Rail, Marine)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 United Kingdom
- 5.4.2.4 Italy
- 5.4.2.5 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 South Korea
- 5.4.3.4 India
- 5.4.3.5 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East
- 5.4.5.1 Israel
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 United Arab Emirates
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Infineon Technologies AG
- 6.4.2 Texas Instruments Incorporated
- 6.4.3 Qorvo Inc.
- 6.4.4 STMicroelectronics N.V.
- 6.4.5 NXP Semiconductors N.V.
- 6.4.6 ON Semiconductor Corporation
- 6.4.7 Renesas Electronics Corporation
- 6.4.8 Broadcom Inc.
- 6.4.9 Toshiba Corporation
- 6.4.10 Mitsubishi Electric Corporation
- 6.4.11 Fuji Electric Co., Ltd.
- 6.4.12 Semikron Danfoss GmbH and Co. KG
- 6.4.13 Wolfspeed Inc.
- 6.4.14 ROHM Co., Ltd.
- 6.4.15 Vishay Intertechnology Inc.
- 6.4.16 Nexperia B.V.
- 6.4.17 Alpha and Omega Semiconductor Ltd.
- 6.4.18 Magnachip Semiconductor Corp.
- 6.4.19 Microchip Technology Inc.
- 6.4.20 Littelfuse Inc.
- 6.4.21 Navitas Semiconductor Corp.
- 6.4.22 Power Integrations Inc.
- 6.4.23 Monolithic Power Systems Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment