|
시장보고서
상품코드
2122973
트랙터 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Tractor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
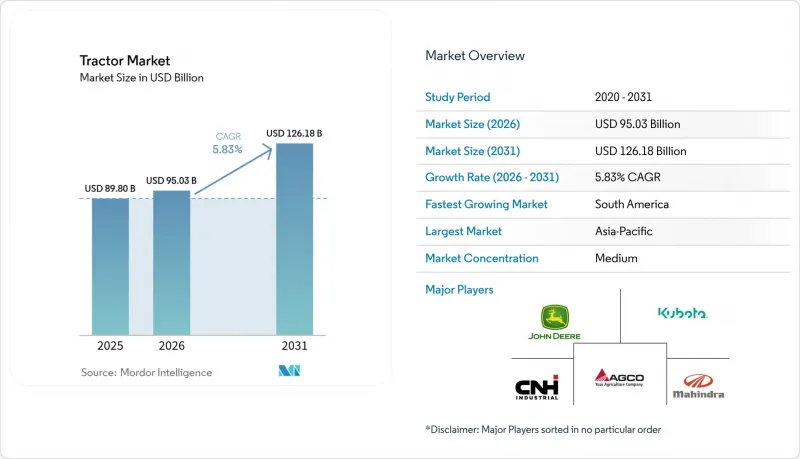
에 의하면, 2026년 트랙터 시장 규모는 950억 3,000만 달러로 추정되고, 2025년 898억 달러로 평가되었습니다.
또한, 2031년의 예측치는 1,261억 8,000만 달러로 예상되며, 2026-2031년 동안 연평균 성장률(CAGR) 5.83%로 성장할 것으로 전망됩니다.
본 보고서는 마력별(40HP 미만, 기타), 구동 방식별(이륜 구동(2WD), 사륜구동·사륜구동(4WD/AWD)), 추진 방식별(디젤, 배터리식 전기, 하이브리드), 용도별(농업, 건설, 임업, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 트랙터 시장 동향 및 인사이트
신흥국에서의 기계화 수요 증가
도시로의 인구 유출과 농촌 지역의 노동력 부족으로 인해, 아시아와 아프리카 전역에서 기계화는 전략적 필요성이 되고 있습니다. 인도의 기계화율은 40-45%로, 중국의 57%나 미국의 95%에 뒤처져 있어 분명히 따라잡을 여지가 있습니다. 중국의 새로운 보조금 제도에서는 스마트 4WD 트랙터가 우선시되고 있으며, 1에이커당 생산성을 향상시키는 고마력(HP) 트랙터로의 전환이 촉진되고 있습니다. 협동조합 소유 모델이나 장비 공유 앱은 비용을 분산시켜 도입을 더욱 뒷받침하는 한편, 비료 사용 최적화와 같은 정밀 시비 방식의 이점은 토양의 건전성을 향상시킵니다. 이러한 동향들이 맞물려 트랙터는 단순한 동력원이 아닌 다기능 자산으로 자리 잡으며, 세계 트랙터 시장의 장기적인 수요를 뒷받침하고 있습니다.
OECD 국가와 BRICS 국가에서 심화되는 농업 인력 부족
미국의 농업 종사자들은 심각한 노동력 부족에 직면해 있으며, 그 결과 인건비가 급등하여 이익률이 압박받고 있습니다. 유럽연합(EU)과 중국에서도 유사한 부족 현상이 나타나고 있습니다. 이에 대응하여 생산자들은 기계 구매를 가속화하고, 임금 상승에 앞서 노동력 절감 기술을 도입하고 있습니다. 자율 주행형 및 원격 조종형 트랙터는 원예 및 특산 작물 재배 부문에서 현저한 진전을 보이고 있으며, 특히 신뢰할 수 있는 계절 노동력을 확보하는 것이 지속적인 과제로 남아 있는 지역에서 이러한 경향이 두드러집니다. 이러한 지속적인 인력 부족은 세계 트랙터 시장의 근본적인 수요 기반을 형성하고 있으며, 농업 관행의 변혁적인 변화를 부각시키고 있습니다. 이러한 첨단 기계가 농장에 도입됨에 따라, 단순히 인력 부족을 메우는 것을 넘어 작물 재배 및 수확 방식을 혁신하고, 혁신이 필요한 이 산업에서 효율성과 생산성의 새로운 가능성을 열어가고 있습니다.
전자 부품 칩 공급 병목 현상
현재 진행 중인 반도체 부족은 파워트레인 컨트롤러와 센서 모듈의 생산에 심각한 영향을 미치고 있습니다. 2025년 초에는 32비트 마이크로컨트롤러의 리드타임이 무려 50주를 넘어섰으며, 이는 생산 라인 중단과 납기 지연과 같은 골치 아픈 사태를 초래했습니다. 일부 자동차용 칩 제조 시설이 드디어 가동을 재개하기 시작했지만, 생산 능력에 대한 부담은 여전히 지속되고 있어 전 세계 트랙터 시장에 지극히 중요한 당면 생산량을 제한하고 있습니다. 경쟁 구도가 격화되는 시장 환경 속에서 각 제조업체들이 수요를 따라잡기 위해 분주히 움직이는 가운데, 이러한 공급 제약으로 인한 파급 효과는 심각하게 느껴지고 있습니다.
부문 분석
40-100HP 등급은 범용성이 높은 주력 제품으로서, 2025년에는 트랙터 시장 규모의 46.93%를 차지했으며, 세계 트랙터 시장을 지탱하고 있습니다. 100HP를 초과하는 기종의 경우, 대규모 농장이 경작 면적의 효율화를 추구하는 가운데, 예측 기간 동안 연평균 성장률(CAGR) 7.16%를 나타낼 것으로 예측됩니다. 이러한 출력 향상은 첨단 유압 시스템과 더 넓은 작업기 폭을 뒷받침하여 통합된 정밀 기술의 실현을 가능하게 합니다. John Deere사가 9RX 시리즈 생산을 목적으로 아이오와주에서 확장을 추진하고 있는 것은 트랙터에 대한 수요의 대폭적인 증가에 대한 장기적인 확신을 뒷받침하고 있습니다.
대규모화에 초점을 맞춘 농업 비즈니스 모델은 텔레매틱스를 활용한 차량 군의 조정 능력을 활용하여, 마력을 탁월한 생산성 향상의 원동력으로 전환하고 있습니다. 한편, 40HP 이하의 소형 트랙터는 원예라는 특수 분야에서 여전히 독자적인 틈새 시장을 개척하고 있지만, 소규모 농지의 기계화 속도가 완만하기 때문에 그 장래성에 대해서는 불확실성이 감돌고 있습니다. 그 결과, 고마력 기계에 대한 수요 증가가 세계 트랙터 시장 규모에서 프리미엄 부문을 견인하며, 판매 대수보다 매출액의 성장을 가속화하고 있습니다.
2025년에는 비용 효율이 뛰어난 2WD 플랫폼이 트랙터 시장의 77.10% 점유율을 차지했습니다. 그러나 4WD의 채택은 견인력 향상이라는 장점이 있어, 습한 조건이나 경사지에서 경작할 때 토크를 분산시킬 수 있습니다. 2031년까지 4WD의 예상 연평균 성장률(CAGR) 7.69%는 일관된 휠 슬립이 종자 배치 정확도를 보장하는 보다 광범위한 정밀 농업의 보급과 일치합니다.
기후 변화의 예측 불가능성은 농업 관행의 양상을 완전히 바꾸고 있으며, 토양 수분 함량이 이상적인 수준 이하로 떨어질 때 밭 작업을 수행할 수 있는 기간이 더욱 짧아지고 있습니다. 이러한 변화는 교대 습윤 건조법(AWD)에 대한 투자의 가치를 부각시키고, 농업 종사자와 혁신적인 솔루션 간의 유대를 강화하고 있습니다. 연중 재배를 목표로 하는 가운데, 많은 농업인들이 사륜구동(4WD) 차량을 변덕스러운 날씨에 대비한 중요한 방어 수단으로 인식하고 있습니다. 이러한 인식의 변화는 4WD 도입과 수익성 향상 추구 간의 연관성을 더욱 공고히 하며, 현대 농업의 과제를 극복하는 데 있어 이러한 기술적 진보가 얼마나 필수적인지를 부각시키고 있습니다.
지역별 분석
2025년, 아시아태평양은 트랙터 시장 규모의 55.35%를 차지했습니다. 중국은 고마력 및 스마트 트랙터로의 전환을 추진하는 가운데 여전히 매우 중요한 역할을 하고 있습니다. 동남아시아 국가 정부들은 농기계 구매에 대해 우대 대출을 제공하며, 이 지역에서 세계 트랙터 시장의 견조한 성장 궤도를 유지하고 있습니다.
남미는 브라질의 대두 및 옥수수 재배 면적 확대와 장비 교체를 뒷받침하는 국내 대출 한도에 힘입어 연평균 성장률(CAGR) 6.89%라는 가장 빠른 성장세를 보이고 있습니다. Massey Ferguson, Valtra, New Holland는 브라질 내 판매에서 큰 점유율을 차지하고 있으며, 이는 현지 조립이 고객의 선호도에 미치는 영향을 여실히 보여주고 있습니다. 칠레와 콜롬비아는 과일 수출의 다각화를 통해 수요를 더욱 확대하며 대륙 전체의 성장세를 강화하고 있습니다.
북미와 유럽은 판매 대수 증가세가 비교적 완만하지만, 대당 가치가 높은 특징을 지닌 성숙한 시장입니다. 2024년, 유럽의 차량 등록 대수는 지난 10년 동안 최저 수준으로 급감하여 수익성 문제가 심각해지고 있음을 반영하고 있습니다. 그럼에도 불구하고 유럽은 전기차 실증 시험 및 자율주행 기술에 관한 규제 체계 정비에서 선구적인 역할을 수행하고 있습니다.
한편, 시장 개발 초기 단계에 있는 중동 및 아프리카는 세계 트랙터 산업의 장기적인 확대와 다각화에 있어 점점 더 중요한 존재가 되고 있습니다. 성장 기회가 풍부한 이 지역에서 새로운 기회를 상징하는 이들 지역은 그 전략적 중요성을 과소평가할 수 없습니다.
기타 혜택
- 엑셀 형식 시장 전망(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, tractor market size in 2026 is estimated at USD 95.03 billion, growing from 2025 value of USD 89.8 billion with 2031 projections showing USD 126.18 billion, growing at 5.83% CAGR over 2026-2031.
This report is Segmented by Horsepower (Below 40 HP, and More), Drive Type (Two-Wheel Drive and Four-/All-Wheel Drive), Propulsion Type (Diesel, Battery-Electric, and Hybrid), Application (Agriculture, Construction, Forestry, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Tractor Market Trends and Insights
Rising Mechanization Demand in Emerging Economies
Urban migration and shrinking rural labor pools make mechanization a strategic necessity across Asia and Africa. India's 40-45% mechanization rate trails China's 57% and the United States' 95%, offering clear catch-up potential. New subsidy schemes in China prioritize smart 4WD tractors, promoting a shift toward higher horsepower that lifts per-acre productivity. Cooperative ownership models and equipment-sharing apps further catalyze adoption by spreading costs, while precision-placement benefits such as optimized fertilizer use improve soil health. Collectively, these trends embed tractors as multifunctional assets rather than basic power units, reinforcing long-term demand for the global tractor market.
Escalating Farm-Labor Shortages in OECD and BRICS
United States farmers grapple with a significant labor shortage, leading to heightened wage costs and squeezed profit margins. Similar gaps exist in the European Union and China. Growers respond by accelerating machinery purchases, now adopting labor-saving technology ahead of wage hikes. Autonomous and remotely operated tractors are making significant strides in the realms of horticulture and specialty crop farming, particularly in areas where securing a reliable seasonal workforce has become an ongoing challenge. This persistent labor shortage creates a fundamental baseline for the demand in the global tractor market, underscoring a transformative shift in agricultural practices. As these advanced machines take to the fields, they are not just filling a gap; they are revolutionizing the way crops are cultivated and harvested, opening up new possibilities for efficiency and productivity in an industry in need of innovation.
Electronics-Grade Chip Supply Bottlenecks
The ongoing semiconductor shortages are casting a long shadow over the production of power-train controllers and sensor modules. In early 2025, the lead times for 32-bit microcontrollers soared beyond a staggering 50 weeks, leading to frustrating line stoppages and protracted delivery timelines. While some automotive chip fabrication facilities are finally beginning to open their doors, the strain on capacity persists, limiting the immediate output crucial for the global tractor market. The ripple effects of this constraint are felt deeply, as manufacturers scramble to keep pace with demand amid an increasingly competitive landscape.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Precision-Ag and Telematics Platforms
- Growth of Data-Driven Tractor-Rental Platforms
- New Localization and Content-Origin Rules in Trade Pacts
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 40-100 HP class supplied mainstream versatility and claimed 46.93% of the tractor market size in 2025, anchoring the global tractor market. Above-100 HP units are forecast to grow at a 7.16% CAGR during the forecast period, as larger farms seek acreage efficiency. This up-powering supports advanced hydraulic systems and greater implement widths, allowing integrated precision technologies. John Deere's Iowa expansion to build 9RX machines underscores long-term confidence in significant iron demand.
Farm business models focusing on larger scales harness the power of telematics-driven fleet coordination, transforming horsepower into a catalyst for extraordinary productivity. While smaller tractors with less than 40 HP continue to carve out their niche in the specialized realm of horticulture, the gradual pace of mechanization in micro-plots casts a shadow over their prospects. Consequently, high-horsepower momentum lifts the premium end of the global tractor market size, propelling revenue faster than unit volume.
Cost-efficient 2WD platforms held a 77.10% share of the tractor market in 2025. Yet 4WD adoption benefits from added traction, distributing torque for tillage under wetter or sloped conditions. The 7.69% CAGR projected for 4WD through 2031 aligns with broader precision-ag uptake, where consistent wheel slip protects seed placement accuracy.
The unpredictable nature of climate variability is reshaping the landscape of agricultural practices, extending the fleeting windows of opportunity for fieldwork when soil moisture levels fall below ideal conditions. This shift underscores the value of Alternate Wetting and Drying (AWD) investments, forging a stronger connection between farmers and innovative solutions. As they strive for year-round cultivation, many are now viewing four-wheel drive (4WD) vehicles as a vital safeguard against the whims of the weather. This evolving mindset deepens the relationship between the adoption of 4WD and the quest for greater profitability, highlighting how essential these advancements have become in navigating the challenges of modern farming.
Complete Report Scope:
- By Horsepower
- Below 40 HP
- 40 - 100 HP
- Above 100 HP
- By Drive Type
- Two-Wheel Drive (2WD)
- Four-/All-Wheel Drive (4WD/AWD)
- By Propulsion Type
- Diesel
- Battery-Electric
- Hybrid (Diesel-Electric)
- By Application
- Agriculture
- Construction
- Forestry
- Municipal & Grounds Maintenance
- Haulage & Logistics
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle-East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific contributed 55.35% of the tractor market size in 2025. China remains pivotal as it pivots toward high-horsepower and smart tractors. Southeast Asian governments channel concessional credit into machinery purchases, maintaining a solid growth runway for the global tractor market in the region.
South America delivers the fastest expansion at 6.89% CAGR, buoyed by Brazil's soy and corn acreage gains and domestic credit lines that spur equipment upgrades. Massey Ferguson, Valtra, and New Holland have a significant share of Brazilian sales, illustrating the influence of localized assembly on customer preference. Chile and Colombia inject incremental demand through fruit-export diversification, reinforcing continental momentum.
North America and Europe showcase well-established markets characterized by a more measured pace of volume growth, yet they boast a higher value per unit. In 2024, European vehicle registrations plummeted to a decade low, reflecting the tightening grip of profitability challenges. Despite this, Europe stands at the forefront of pioneering electric vehicle trials and developing regulatory frameworks for autonomous technology.
Meanwhile, the Middle East and Africa, still in their early stages of market development, are becoming increasingly vital to the long-term expansion and diversity of the global tractor industry. Their strategic importance cannot be understated as they represent emerging opportunities in a landscape ripe for growth.
- Deere & Company
- CNH Industrial N.V. (Case IH, New Holland)
- AGCO Corporation (Massey Ferguson, Valtra, Fendt)
- Mahindra & Mahindra Ltd.
- Kubota Corporation
- CLAAS KGaA mbH
- Escorts Kubota Ltd.
- TAFE Ltd.
- Sonalika (International Tractors Ltd.)
- SDF Group (Same Deutz-Fahr)
- Yanmar Co. Ltd.
- Argo Tractors S.p.A.
- LS Mtron Ltd.
- Daedong (Kioti)
- TYM Corporation
- Weichai Lovol Intelligent Agricultural Technology CO., LTD
- YTO Group Corp.
- XCMG Construction Machinery Co., Ltd.
- Zetor Tractors a.s.
- J C Bamford Excavators Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Mechanization Demand in Emerging Economies
- 4.2.2 Government Subsidies and Low-Interest Ag-Credit Lines
- 4.2.3 Escalating Farm-Labor Shortages in OECD and BRICS
- 4.2.4 Rapid Adoption of Precision-Ag and Telematics Platforms
- 4.2.5 Commercialization of Battery-Electric and Fuel-Cell Tractors
- 4.2.6 Growth of Data-Driven Tractor-Rental Platforms
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost and Commodity-Price Volatility
- 4.3.2 Seasonal Income Dependence on Monsoon/Weather Cycles
- 4.3.3 Electronics-Grade Chip Supply Bottlenecks
- 4.3.4 New Localization and Content-Origin Rules In Trade Pacts
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Horsepower
- 5.1.1 Below 40 HP
- 5.1.2 40 - 100 HP
- 5.1.3 Above 100 HP
- 5.2 By Drive Type
- 5.2.1 Two-Wheel Drive (2WD)
- 5.2.2 Four-/All-Wheel Drive (4WD/AWD)
- 5.3 By Propulsion Type
- 5.3.1 Diesel
- 5.3.2 Battery-Electric
- 5.3.3 Hybrid (Diesel-Electric)
- 5.4 By Application
- 5.4.1 Agriculture
- 5.4.2 Construction
- 5.4.3 Forestry
- 5.4.4 Municipal & Grounds Maintenance
- 5.4.5 Haulage & Logistics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle-East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Deere & Company
- 6.4.2 CNH Industrial N.V. (Case IH, New Holland)
- 6.4.3 AGCO Corporation (Massey Ferguson, Valtra, Fendt)
- 6.4.4 Mahindra & Mahindra Ltd.
- 6.4.5 Kubota Corporation
- 6.4.6 CLAAS KGaA mbH
- 6.4.7 Escorts Kubota Ltd.
- 6.4.8 TAFE Ltd.
- 6.4.9 Sonalika (International Tractors Ltd.)
- 6.4.10 SDF Group (Same Deutz-Fahr)
- 6.4.11 Yanmar Co. Ltd.
- 6.4.12 Argo Tractors S.p.A.
- 6.4.13 LS Mtron Ltd.
- 6.4.14 Daedong (Kioti)
- 6.4.15 TYM Corporation
- 6.4.16 Weichai Lovol Intelligent Agricultural Technology CO., LTD
- 6.4.17 YTO Group Corp.
- 6.4.18 XCMG Construction Machinery Co., Ltd.
- 6.4.19 Zetor Tractors a.s.
- 6.4.20 J C Bamford Excavators Ltd