

|
시장보고서
상품코드
2123278
지혈 제품 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hemostasis Products - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
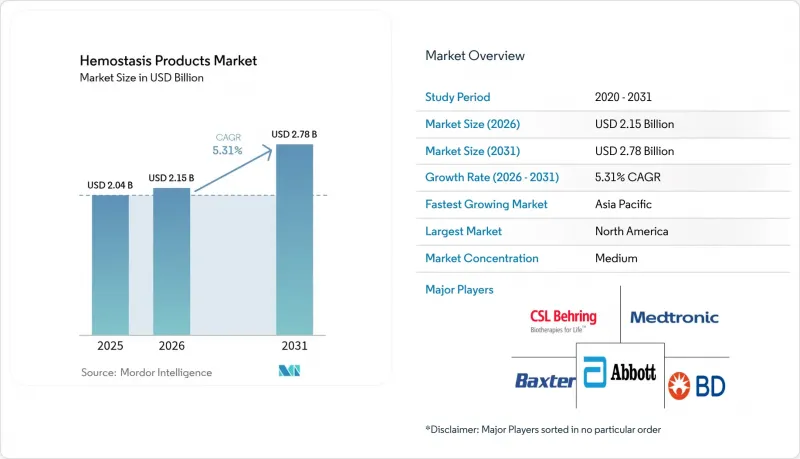
지혈 제품 시장 규모는 2026년에 21억 5,000만 달러로 추정되고 있어 2025년 20억 4,000만 달러에서 확대해, 2031년에는 27억 8,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.31%로 성장할 것으로 전망됩니다.
본 보고서는 제품별(외용 지혈제, 주입용 지혈제, 첨단 지혈제), 제형별(매트릭스·젤, 분말 등),용도별(외상, 외과 수술, 심근경색 등), 최종 사용자별(병원, 진료소 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 지혈 제품 시장 동향 및 인사이트
외상 및 외과 수술 건수 증가
세계 외과 수술 건수는 증가 추세를 보이고 있으며, 남아시아만 해도 16억 명의 환자가 의료 서비스 접근성 부족에 직면해 있어, 이는 현재 정책상의 우선 과제로 대두되고 있습니다. 개정된 손상 통제 소생 지침에서는 기도 관리보다 출혈 통제를 우선시하도록 규정하고 있으며, 이를 통해 출혈로 인한 사망을 65% 감소시키고, 신속한 국소 지혈제에 대한 일선 수요를 확대되고 있습니다. 군의 야전 의료, 특히 ‘합동 외상 시스템(Joint Trauma System)’에서는 조기 혈액 제제 사용이 표준화되어 있으며, 그 프로토콜은 민간 외상 의료 네트워크로도 확산되고 있습니다. 이러한 변화로 인해, 현장 트리아지부터 첨단 수술실에 이르기까지 환자 관리의 모든 단계에 출혈 통제가 통합됨에 따라 지혈 제품 시장이 확대되고 있습니다. 진단약, 국소용 젤, 응고 인자 농축액을 결합한 통합 키트를 제공하는 공급업체는 조달 프로세스의 효율화를 추구하는 병원 수요를 확보하게 될 것입니다.
국소용 및 첨단 지혈제 분야의 급속한 제품 혁신
자가 조직화 펩타이드 하이드로겔은 몇 초 만에 지혈을 달성하고, 가시화를 위해 투명성을 유지하며, 동물 조직으로 인한 병원체 전파 위험을 방지합니다. 순차 가교형 피브린 접착제는 15초 이내에 이중 네트워크 밀봉층을 형성하여, 중합에 수분이 소요되는 기존 피브린 실란트를 능가하는 성능을 발휘합니다. 공유 결합성 미립자는 동맥압 하에서도 견고한 혈전을 형성하며, 전임상 모델에서 20초 미만에 지혈을 달성했습니다. 식물 유래 ‘트라우마겔’이 FDA 승인을 획득함으로써, 생체 모방 활성 성분의 상용화를 위한 길이 열렸습니다. 이러한 혁신의 물결은 지연 작용형 혈장 유래 제제를 현대 외과 수술 워크플로우에 원활하게 통합되는 신속한 제제로 대체함으로써 지혈 제품 시장을 주도하고 있습니다.
전 세계적인 규제 및 보험 급여의 엄격한 장벽
FDA는 최근 점탄성 응고 분석 장치를 클래스 II로 재분류하여, 의료기기 제조업체에 품질 관리 시스템 및 임상 데이터와 관련된 부담을 추가했습니다. 유럽 의료기기 규정(MDR)으로 인해 심사 대기 목록이 길어지면서 중소기업의 제품 출시가 지연되는 한편, 지혈 제품 시장은 규제 대응 체계를 갖춘 기존 기업에 유리한 상황이 되고 있습니다. 지급 제도 개혁에도 마찬가지로 과제가 있습니다. CMS(미국 의료보험서비스센터)의 새로운 번들링 규정에 따라 자가혈 유래 드레싱에 대한 보험 적용 범위가 좁아질 가능성이 있으며, 병원은 구체적인 치료 성과를 통해 고액 지출의 정당성을 입증해야할 것입니다.
부문 분석
2025년, 지혈 제품 시장에서 수혈 요법은 35.12%의 점유율을 유지했습니다. 이는 대량 출혈이나 혈우병 관리에 있어 응고 인자 농축 제제가 여전히 필수적이기 때문입니다. 그러나 유전자 치료와 FXIa 억제제의 발전에 따라 수요는 정체기에 접어들고 있습니다. 지혈 제품 시장은 속도, 접착성, 면역원성 측면의 성능 격차를 해소하는 합성 및 생체 모방형 활성 실란트로 전환되고 있습니다.
선도적인 제품군은 2031년까지 연평균 성장률(CAGR) 9.84%를 나타낼 것으로 예측되며, 시장 확대의 견인차 역할을 할 전망입니다. VISTASEAL 및 식물 유래 Traumagel에 대한 FDA의 승인은 새로운 유효 성분을 승인하려는 규제 당국의 태도를 보여줍니다. 다국적 기업들이 기술 확보를 위해 신생 기업을 인수하는 움직임이 활발해지면서 경쟁이 심화되고 있습니다. 예를 들어, 스트라이커(Stryker)사의 49억 달러 규모 이나리(Inari)사 인수는 말초 혈관 분야에서의 사업 범위를 확대하기 위한 것입니다.
2025년 매출액 중 액체 및 스프레이 제형이 38.11%를 차지하고 있는데, 이는 외과의사들이 복강경 포트나 로봇 팔을 통해 사용할 수 있고 혼합이 필요 없는 시스템을 선호하는 경향을 반영한 것입니다. 지혈 제품 시장의 이 분야는 복잡한 해부학적 구조에 맞추어 유량을 조절할 수 있는 배터리 구동식 어플리케이터 등 투여 기기의 혁신으로 혜택을 보고 있습니다.
매트릭스 젤 시스템은 순차 가교 화학 기술을 통해 습윤 조직 위에서도 15초 만에 밀봉이 가능해짐에 따라 연평균 성장률(CAGR) 7.84%로 성장하고 있습니다. 초탄성 기질을 사용한 즉효성 접착 패치는 장기의 움직임으로 인해 기존 패드가 제대로 기능하기 어려운 흉부 및 심장 수복 분야로 지혈 제품 업계의 적용 범위를 확대되고 있습니다.
지역별 분석
북미는 2025년 매출의 42.38%를 차지하고 있으며, 이러한 위상은 높은 수술 시행률, 엄격한 임상시험 인프라, 그리고 합성 혈액 프로그램에 대한 대규모 국방 연구개발(R&D) 자금에 의해 강화되고 있습니다. FDA의 패스트 트랙 제도와 국방생산법은 공급 충격 이후 국내 생산의 회복력을 함께 촉진하여, 중요한 지혈제의 지역적 공급 안정화에 기여하고 있습니다.
유럽 시장은 계속해서 안전성 기준을 확립하고 있으며, 마스타시맙 및 에파네소크토그 알파에 대한 EMA의 승인은 혈우병 치료제 분야에서 이 지역의 리더십을 입증하고 있습니다. 다만, 도입 상황에는 편차가 있으며, 남유럽 국가들은 광범위한 도입에 앞서 비용 대비 효과를 면밀히 검토하고 있습니다. 의료기기 규정(MDR) 일정은 성숙한 품질 관리 시스템을 갖춘 기업에 유리하게 작용하며, 중견 기업과 관련 포트폴리오를 추구하는 대형 전략적 기업간의 제휴를 촉진하고 있습니다.
아시아태평양은 병원 인프라의 현대화와 선택적 수술의 대기 시간 해소로 인해 지혈 제품 시장에서 가장 빠르게 성장하고 있는 지역입니다. 일본이 유통기한 2년의 합성 혈액을 발표한 것은 이 지역의 혁신 역량을 입증하고 있습니다. 남아시아의 외과 수술 접근성 격차는 잠재적 수요를 창출하고 있으며, 보편적 의료 보장(UHC) 제도의 확대에 따라 그 수요가 표면화될 가능성이 있습니다. 현지 생산에 대한 인센티브로 인해 혈장 분획 및 펩타이드 합성 공장에 대한 투자가 유치되고 있으며, 수입 의존도가 낮아지고 전 세계 공급원의 다각화가 진행되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, hemostasis products market size in 2026 is estimated at USD 2.15 billion, growing from 2025 value of USD 2.04 billion with 2031 projections showing USD 2.78 billion, growing at 5.31% CAGR over 2026-2031.
This report is Segmented by Product (Topical Hemostasis, Infusible Hemostasis, and Advanced Hemostasis), Formulation (Matrix & Gel, Powder, and More), Application (Trauma, Surgery, Myocardial Infarction, and More), End User (Hospitals, Clinics, and More) and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hemostasis Products Market Trends and Insights
Rising Volume of Trauma & Surgical Procedures
Global surgical caseload is climbing, with South Asia alone facing a 1.6 billion patient access deficit that is now a policy priority. Updated damage-control resuscitation guidelines place hemorrhage control ahead of airway management, cutting exsanguination mortality by 65% and expanding front-line demand for rapid topical agents. Military field medicine-particularly the Joint Trauma System-has normalised early blood-product use, and its protocols are diffusing into civilian trauma networks. These changes enlarge the Hemostasis products market by embedding bleeding control into every step of patient management, from roadside triage to advanced operating suites. Suppliers offering integrated kits that combine diagnostics, topical gels, and factor concentrates will capture hospitals seeking streamlined procurement.
Rapid Product Innovation in Topical & Advanced Hemostats
Self-assembling peptide hydrogels reach hemostasis in seconds, remain transparent for visualisation, and avoid pathogen transmission risks tied to animal tissue. Sequential-crosslinking fibrin glues form dual-network seals within 15 seconds, outperforming legacy fibrin sealants that need minutes to polymerise. Covalently reactive microparticles create fortified clots even under arterial pressure, achieving sub-20-second control in preclinical models. FDA clearance of plant-derived Traumagel validates the commercial pathway for biomimetic actives. This innovation wave lifts the Hemostasis products market by replacing slow, plasma-based agents with agile formulations that integrate seamlessly into modern surgical workflows.
Stringent Global Regulatory & Reimbursement Hurdles
The FDA recently shifted viscoelastic coagulation analysers into Class II, adding quality-system and clinical-data burdens for device makers. Europe's Medical Device Regulation has lengthened review queues, delaying small-company launches and tilting the Hemostasis products market toward incumbents with regulatory infrastructure. Payment reform is equally challenging; new CMS bundling rules could narrow coverage for autologous blood-derived dressings, forcing hospitals to justify premium spend through hard outcomes.
Other drivers and restraints analyzed in the detailed report include:
- Growing Adoption of Minimally Invasive & Robotic Surgeries
- Aging Population-Linked Comorbidities Expanding Target Pool
- High Cost of Active Sealants in Low-Resource Settings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Infusible therapies retained 35.12% of the Hemostasis products market share in 2025 because factor concentrates remain essential during major bleeds and hemophilia management. Demand, however, is plateauing as gene therapy and FXIa inhibitors progress. The Hemostasis products market is pivoting toward synthetic and biomimetic active sealants that address performance gaps in speed, adhesion, and immunogenicity.
Advanced offerings are projected to grow at 9.84% CAGR through 2031, setting the pace for market expansion. FDA approval of VISTASEAL and plant-based Traumagel illustrates regulatory willingness to endorse novel actives. Competitive intensity is rising as multinationals acquire start-ups for technology access, with Stryker's USD 4.9 billion Inari acquisition broadening peripheral vascular reach.
Liquid and spray formats captured 38.11% of 2025 revenues, reflecting surgeon preference for no-mix systems that can be deployed through laparoscopic ports or robotic arms. This slice of the Hemostasis products market size benefits from delivery-device innovation, including battery-powered applicators that modulate flow rates for complex anatomy.
Matrix-gel systems are advancing at 7.84% CAGR as sequential-crosslinking chemistries deliver 15-second seals even on moist tissue. Instantly adhesive patches using ultra-elastic substrates extend the Hemostasis products industry to thoracic and cardiac repairs where organ motion frustrates traditional pads.
Complete Report Scope:
- By Product Type
- Topical Hemostasis (Collagen, ORC, Gelatin, Polysaccharides)
- Infusible Hemostasis (FFP, Platelet Conc, Factor VIII, PCC)
- Advanced Hemostasis (Flowable, Thrombin, Fibrin, Synthetic)
- By Formulation
- Matrix & Gel
- Sponge & Pad
- Powder
- Liquid / Spray
- By Application
- Trauma
- Surgery
- Hemophilia
- Myocardial Infarction
- Thrombosis
- Others
- By End User
- Hospitals
- Clinics & ASCs
- Others
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 42.38% of 2025 revenues, a position reinforced by high surgical density, rigorous clinical-trial infrastructure, and sizeable defence R&D funding for synthetic blood programmes. FDA fast-track pathways and the Defence Production Act have together promoted domestic production resilience after supply shocks, helping stabilise regional availability of critical hemostats.
European markets continue to set safety benchmarks; EMA approvals for marstacimab and efanesoctocog alfa confirm the region's leadership in hemophilia therapeutics. Adoption varies, however, with southern economies scrutinising cost-effectiveness before broad rollout. Medical Device Regulation timelines favour firms with mature quality systems, encouraging partnerships between mid-caps and large strategics seeking contiguous portfolios.
Asia-Pacific is the fastest growing area of the Hemostasis products market as hospital infrastructure modernises and elective surgery backlogs unwind. Japan's announcement of a two-year shelf-life synthetic blood underscores regional innovation capability. South Asia's surgical access gap creates latent demand likely to unlock as universal health-coverage schemes expand. Local manufacturing incentives are attracting investment into plasma fractionation and peptide synthesis plants, reducing import reliance and diversifying global supply.
- Abbott Laboratories
- Baxter
- Becton Dickinson (BD)
- CSL Behring
- Grifols
- Johnson & Johnson
- Medtronic
- Pfizer
- Tricol Biomedical
- CryoLife
- Integra LifeSciences
- B. Braun
- Teleflex
- Zimmer Biomet
- Hemostasis
- Marine Polymer Technologies
- LifeBond Ltd.
- KitoTech Medical
- Arch Biomedical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Volume of Trauma & Surgical Procedures
- 4.2.2 Rapid Product Innovation In Topical & Advanced Hemostats
- 4.2.3 Growing Adoption of Minimally-Invasive & Robotic Surgeries
- 4.2.4 Aging Population-Linked Comorbidities Expanding Target Pool
- 4.2.5 Military Demand For Shelf-Stable Plasma & Synthetic Blood
- 4.2.6 Breakthrough Self-Assembling Peptide Gels For GI Bleeding
- 4.3 Market Restraints
- 4.3.1 Stringent Global Regulatory & Reimbursement Hurdles
- 4.3.2 High Cost Of Active Sealants In Low-Resource Settings
- 4.3.3 Fragile Biologic Supply Chains (Bovine/Porcine Thrombin)
- 4.3.4 FXIa Inhibitor Pipeline Cannibalizing Infusible Products
- 4.4 Porter's Five Forces
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Topical Hemostasis (Collagen, ORC, Gelatin, Polysaccharides)
- 5.1.2 Infusible Hemostasis (FFP, Platelet Conc, Factor VIII, PCC)
- 5.1.3 Advanced Hemostasis (Flowable, Thrombin, Fibrin, Synthetic)
- 5.2 By Formulation
- 5.2.1 Matrix & Gel
- 5.2.2 Sponge & Pad
- 5.2.3 Powder
- 5.2.4 Liquid / Spray
- 5.3 By Application
- 5.3.1 Trauma
- 5.3.2 Surgery
- 5.3.3 Hemophilia
- 5.3.4 Myocardial Infarction
- 5.3.5 Thrombosis
- 5.3.6 Others
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Clinics & ASCs
- 5.4.3 Others
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Baxter International
- 6.3.3 Becton Dickinson (BD)
- 6.3.4 CSL Behring
- 6.3.5 Grifols S.A.
- 6.3.6 Johnson & Johnson (Ethicon)
- 6.3.7 Medtronic plc
- 6.3.8 Pfizer Inc.
- 6.3.9 Tricol Biomedical
- 6.3.10 CryoLife Inc.
- 6.3.11 Integra LifeSciences
- 6.3.12 B. Braun Melsungen
- 6.3.13 Teleflex Inc.
- 6.3.14 Zimmer Biomet
- 6.3.15 Hemostasis LLC
- 6.3.16 Marine Polymer Technologies
- 6.3.17 LifeBond Ltd.
- 6.3.18 KitoTech Medical
- 6.3.19 Arch Biomedical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


