|
시장보고서
상품코드
2123343
간질환 치료제 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Liver Diseases Therapeutics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
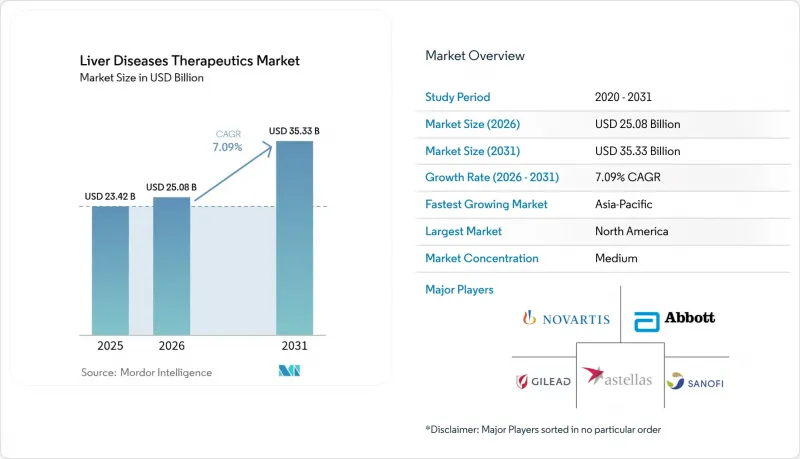
에 의하면, 간질환 치료제 시장 규모는 2025년 234억 2,000만 달러에서 2026년에는 250억 8,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 7.09%로 성장을 지속하여, 2031년에는 353억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 치료법별(항바이러스제, 면역억제제 등), 질환별(A형-E형 바이러스성 간염 등), 약물 분류별(저분자 경구약 등), 투여 경로별(경구, 주사제),최종 사용자별(병원 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
전 세계 간질환 치료제 시장 동향 및 인사이트
간질환 발생률 증가
간세포암은 전 세계적으로 암 사망 원인 중 3위를 차지하고 있으며, 한편 만성 간질환은 매년 450만 명 이상의 미국인에게 영향을 미치고 있습니다. 이러한 역학적 급증으로 인해 항바이러스제, 면역요법 및 질환 수정 항섬유화제에 대한 지속적인 수요가 촉진되고 있습니다. 아시아태평양은 바이러스성 간염의 부담이 더 무거운 반면, 서유럽 국가들은 비만 및 당뇨병과 관련된 MASLD 증가에 직면해 있습니다. 노화에 따라 간의 재생 능력이 저하되기 때문에 고령화는 질병 유병률을 더욱 악화시키고 있습니다. 각국의 공적 의료보험 제도는 질병을 조기에 발견하기 위한 선별 검사 프로그램을 확충함으로써 이에 대응하고 있으며, 이로 인해 근치적 치료 대상이 되는 환자층이 확대되어 간질환 치료제 시장을 뒷받침하고 있습니다.
알코올 섭취량 증가와 비만으로 인한 MASLD
MASLD는 전 세계 인구의 약 25%에 영향을 미치고 있으며, 간 이식 적응증 중 가장 빠르게 증가하고 있습니다. 2024년 임상 데이터에 따르면, 대사증후군 환자는 3-4기 섬유화로 진행될 위험이 3배 더 높으며, 이에 동반되는 알코올 섭취는 질환의 진행을 7년 앞당기는 것으로 나타났습니다. FGF21 작용제 및 PPAR 조절제를 포함한 이중 경로 약물은 현재 후기 임상시험 단계에 있습니다. 규제 당국은 MASLD의 다인자적 특성을 인식하고, 병용 요법을 검증하는 적응형 임상시험 설계를 적극적으로 채택하고 있습니다. 미국에서만 MASLD 관련 연간 의료비는 1,030억 달러를 초과하며, 보험사들은 말기 질환으로의 진행을 저지하는 치료법에 대해 고액의 보험료 설정을 수용하고 있습니다.
치료법의 이상반응 및 장기적 안전성 우려
면역억제 요법은 감염 위험을 40% 증가시킵니다. 또한, 새로운 항섬유화제의 경우 심장 및 신장 기능 모니터링이 필수적입니다. FDA는 현재 NASH 치료제에 대해 시판 후 5년간의 안전성 조사를 의무화하고 있습니다. 복잡한 투여 일정은 복약 순응도를 저해하므로, 의사들은 장기적인 실제 임상 데이터가 축적될 때까지 보수적인 처방을 하고 있습니다. 개발 중단을 방지하기 위해 각 제약사는 의약품 개발 초기 단계에서 안전성 위험을 파악할 수 있는 예측 독성학 및 미세생리학적 간 모델에 대한 투자를 추진하고 있습니다.
부문 분석
2025년, 항바이러스 요법은 간질환 치료제 시장에서 36.12%의 점유율을 유지했습니다. 이는 95%의 완치율을 유지하는 범유전자형 직접 작용 항바이러스제가 주도한 결과입니다. 2억 9,600만 명의 B형 만성 간염 보균자에 대한 바이러스 억제는 지속적인 수익을 보장하고 있습니다. 한편, 항섬유화·항지방간 치료제는 레스메틸롬의 ‘퍼스트-인-클래스’ 승인 및 MASLD 환자 수의 급증에 힘입어 2031년까지 연평균 성장률(CAGR) 10.22%를 나타낼 것으로 예측됩니다. 면역억제제는 자가면역성 간염 분야에서 틈새 시장 지위를 유지하고 있는 반면, 종양학에 초점을 맞춘 면역요법은 세포독성 화학요법을 대체하는 경향이 강해지고 있습니다. 대사 교정제와 항염증제를 조합한 병용 요법이 처방 패턴을 확대하고 있어, 간질환 치료제 시장 규모를 끌어올리고 있습니다.
파이프라인의 다각화가 진행됨에 따라 경쟁 환경도 변화하고 있습니다. 18개월 이내에 12종 이상의 이중 경로 후보 약물이 2상 임상시험 단계에 진입했습니다. 비침습적 섬유화 역전 점수와 연계된 성과 기반 계약은 특히 통합 의료 시스템에서 시장 침투를 촉진하고 있습니다. 후기 치료 단계에서 항바이러스제 내성은 여전히 드물기 때문에 라이프사이클 관리는 복용 부담을 경감하고 제네릭 의약품에 의한 시장 침식으로부터 제품군을 보호하는 고정 용량 복합제로 중점이 이동하고 있습니다.
2025년에는 환자 수가 많고 생명을 구하는 근치적 치료법 덕분에 바이러스성 간염이 간질환 치료제 시장 점유율의 42.35%를 차지했습니다. WHO의 근절 목표에 따라 조달 자금이 유지되고, 중국과 인도의 국내 생산 노력으로 인해 1회 치료 과정당 비용이 65% 절감되어 접근성이 확대되고, 간질환 치료제 시장이 강화되고 있습니다. 그러나 전 세계 비만 증가에 따라 MASLD(다인자성 지방간질환)는 연평균 성장률(CAGR) 11.28%를 기록할 전망입니다. 지방간질환의 다인자적 병인은 평균 판매 가격을 끌어올리는 병용 요법의 구축을 촉진하고 있습니다.
알코올 관련 간질환의 경우, 중증 알코올성 간염에서 90일 사망률을 25% 감소시킨 것으로 입증된 라스코스테롤이 FDA로부터 ‘획기적 치료제(Breakthrough Therapy)’ 지정을 받으면서 새로운 주목을 받고 있습니다. 자가면역성 간질환은 시장 규모는 작지만, 이식 필요성을 지연시키는 생물학적 제제에 대해 고액의 보험 급여가 인정되고 있습니다. 희귀 유전성 질환 및 소아 질환의 경우, 승인을 신속화하고 더 높은 가격 책정이 가능하도록 하는 희귀질환용 의약품(오펀) 우대 조치가 적용되어 연구 위험을 경감시키고 있습니다.
지역별 분석
북미는 2025년에 매출의 42.10%를 차지하며, 이는 새로 승인된 NASH 치료제의 급속한 보급과 모든 유전자형을 대상으로 하는 C형 간염 바이러스(HCV) 항바이러스제에 대한 광범위한 보험 적용에 힘입은 것입니다. 학술 연구센터의 존재가 후기 임상시험에 대한 피험자 등록을 가속화하고 있으며, 세액 공제가 연구 개발(R&D)을 지원하고 있습니다. 그러나 치료비 급등으로 인해 적응증에 따른 리베이트를 협상하는 약국 혜택 관리자(PBM)의 감시가 엄격해지고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 12.45%를 기록하며 가장 빠르게 성장하는 지역입니다. 중국에만 8,000만 명의 만성 B형 간염 환자가 있으며, 국가 보험 적용 범위에 1차 치료제인 테노포비르의 제네릭 의약품이 포함됨에 따라 치료 대상이 되는 환자층이 확대되고 있습니다. 일본의 신속 심사 제도는 획기적인 생물학적 제제의 승인 기간을 단축하고 있는 반면, 한국의 생명공학 세제 혜택 조치는 국내 RNAi 파이프라인을 뒷받침하고 있습니다.
유럽에서는 의료기술평가기관이 신규 진입을 승인하기 전에 비용 대비 효과를 중시하기 때문에 꾸준하기는 하지만 성장 속도는 완만합니다. EMA(유럽의약품청)가 FDA(미국 식품의약국)의 과학적 자문에 발맞춘 덕분에 병행 신청 절차는 원활해졌으나, 가격·수량 협정에 따라 각국에서의 출시가 1년 이상 지연될 가능성이 있습니다. 중동 및 아프리카 및 남미는 전 세계 매출에서 차지하는 비중은 작지만, 다자간 기부자 프로그램과 단계적 가격 책정 모델을 통해 WHO가 권장하는 치료법에 대한 접근성이 개선되면서 간질환 치료제 시장은 점차 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the liver diseases therapeutics market size is expected to grow from USD 23.42 billion in 2025 to USD 25.08 billion in 2026 and is forecast to reach USD 35.33 billion by 2031 at 7.09% CAGR over 2026-2031.
This report is Segmented by Treatment Type (Anti-Viral Drugs, Immunosuppressants, and More), Disease Type (Viral Hepatitis A-E, and More), Drug Class (Small-Molecule Orals, and More), Route of Administration (Oral, Injectable), End User (Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Liver Diseases Therapeutics Market Trends and Insights
Rise in the Incidence of Liver Diseases
Hepatocellular carcinoma ranks as the third-leading cause of cancer mortality worldwide, while chronic liver disease affects more than 4.5 million Americans each year. This epidemiological surge stimulates sustained uptake of antivirals, immunotherapies, and disease-modifying antifibrotics. Asia-Pacific carries a heavier viral hepatitis burden, whereas Western economies confront rising MASLD linked to obesity and diabetes. Aging populations compound disease prevalence because hepatic regenerative capacity declines with age. National payer systems respond by broadening screening programmes that detect disease earlier, expanding the addressable pool for curative therapies and boosting the liver disease therapeutics market.
Increase in Alcohol Consumption & Obesity-Driven MASLD
MASLD touches roughly 25% of the global population, making it the fastest-growing indication for liver transplantation. Clinical evidence from 2024 shows metabolic-syndrome patients possess triple the risk of advancing to stage 3-4 fibrosis, and concurrent alcohol use accelerates disease by seven years. Dual-pathway drugs, including FGF21 agonists and PPAR modulators, are now in late-phase trials. Regulators embrace adaptive designs that test combination regimens, acknowledging MASLD's multifactorial nature. In the United States alone, MASLD-related spending exceeds USD 103 billion annually, prompting insurers to accept premium pricing for therapies that avert progression to end-stage disease.
Adverse Events & Long-Term Safety Concerns of Therapies
Immunosuppressive regimens elevate infection risk by 40%; new antifibrotic agents mandate cardiac and renal monitoring. FDA now demands five-year post-marketing safety studies for NASH drugs. Complex dosing schedules undermine adherence, and physicians adopt conservative prescribing until long-term real-world data mature. To curb attrition, sponsors are investing in predictive toxicology and microphysiological liver models that flag safety liabilities earlier in drug development.
Other drivers and restraints analyzed in the detailed report include:
- Rising Government Vaccination & Screening Initiatives
- Breakthrough Approvals for NASH-Specific Drugs
- Stringent, Multi-Regional Regulatory Approval Timelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Anti-viral therapies retained 36.12% share of the liver disease therapeutics market in 2025, propelled by pan-genotypic direct-acting antivirals that sustain 95% cure rates. Chronic hepatitis B suppression for 296 million carriers assures durable revenue. Meanwhile, antifibrotic/antisteatotic agents are projected to log a 10.22% CAGR to 2031, benefitting from Resmetirom's first-in-class approval and a ballooning MASLD population. Immunosuppressants maintain a niche for autoimmune hepatitis, whereas oncology-focused immunotherapies increasingly supplant cytotoxic chemotherapies. Combination regimens blending metabolic correctors with anti-inflammatory agents are expanding prescribing patterns, lifting the liver disease therapeutics market size.
The competitive narrative is evolving as pipeline dispersion intensifies; more than a dozen dual-pathway candidates have entered Phase II within 18 months. Pay-for-performance contracts tied to non-invasive fibrosis regression scores bolster market uptake, especially among integrated health systems. As late-line antiviral resistance remains rare, lifecycle management pivots to fixed-dose combinations that lessen pill burden and shield franchises from generic erosion.
Viral hepatitis contributed 42.35% of liver disease therapeutics market share in 2025 due to sheer patient volume and life-saving curative regimens. WHO elimination targets sustain procurement funding, and domestic production efforts in China and India lower per-course costs by 65%, broadening access and reinforcing the liver disease therapeutics market. MASLD, however, will post an 11.28% CAGR as obesity climbs worldwide. Steatotic liver disease's multifactorial pathogenesis encourages combination therapy architectures that elevate average selling prices.
Alcohol-related liver disease receives fresh attention following FDA Breakthrough Therapy status for larsucosterol, which demonstrated 25% reduction in 90-day mortality in severe alcoholic hepatitis. Autoimmune liver diseases, although representing a smaller segment, achieve premium reimbursement for biologic agents that delay transplant need. Rare genetic and paediatric disorders benefit from orphan incentives that speed approvals and permit higher pricing benchmarks, cushioning research risk.
Complete Report Scope:
- By Treatment Type
- Anti-viral Drugs
- Immunosuppressants
- Targeted Therapy & Small Molecules
- Chemotherapy Drugs
- Antifibrotic/Antisteatotic Agents
- Vaccines
- Immunoglobulins
- By Disease Type
- Viral Hepatitis (A-E)
- Alcohol-Related Liver Disease (ARLD)
- Metabolic Dysfunction-Associated Steatotic Liver Disease (MASLD) / MASH
- Autoimmune Liver Diseases
- Genetic & Pediatric Disorders
- Other Disease Types
- By Drug Class
- Small-molecule Orals
- Biologics & Monoclonal Antibodies
- RNA-based Therapeutics
- Cell & Gene Therapy
- By Route of Administration
- Oral
- Injectable
- By End User
- Hospitals
- Ambulatory Surgery Centers
- Specialty Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 42.10% of revenue in 2025, underpinned by rapid adoption of newly approved NASH drugs and broad insurance coverage for pan-genotypic HCV antivirals. The presence of academic centres accelerates enrolment in late-phase trials, and tax credits support R&D. Yet ballooning therapy prices heighten scrutiny from pharmacy benefit managers that negotiate indication-based rebates.
Asia-Pacific is the fastest-growing territory at a 12.45% CAGR to 2031. China alone houses 80 million chronic hepatitis B patients, and national reimbursement now covers first-line tenofovir generics, expanding the treated population. Japan's fast-track review system shortens approval timelines for breakthrough biologics, while South Korea's biotech tax incentives spur domestic RNAi pipelines.
Europe witnesses steady, slower growth as health technology assessment agencies seek cost-effectiveness before authorising new entries. EMA alignment with FDA scientific advice has smoothed parallel submissions, but price-volume agreements can delay country-level launches by more than a year. Middle East & Africa and South America together account for minor share of global revenue; however, multilateral donor programmes and tiered pricing models improve access to WHO-preferred therapies, gradually enlarging the liver disease therapeutics market.
- Abbott Laboratories
- Abbvie
- Astellas Pharma
- Alnylam Pharmaceuticals
- Bristol-Myers Squibb
- Roche
- Gilead Sciences
- GlaxoSmithKline
- Merck
- Novartis
- Pfizer
- Sanofi
- Takeda Pharmaceutical Co.
- Endo International
- Provectus Biopharmaceuticals
- Intercept Pharmaceuticals
- Madrigal Pharmaceuticals Inc.
- Eiger BioPharmaceuticals Inc.
- Ionis Pharmaceuticals
- Aligos Therapeutics Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in the Incidence of Liver Diseases
- 4.2.2 Increase In Alcohol Consumption & Obesity-Driven MASLD
- 4.2.3 Rising Government Vaccination & Screening Initiatives
- 4.2.4 Breakthrough Approvals for Nash-Specific Drugs
- 4.2.5 Ai-Powered, Non-Invasive Diagnostics Enabling Early Detection
- 4.2.6 Combination RNAi-Immunotherapy Pipelines Accelerating Cures
- 4.3 Market Restraints
- 4.3.1 Adverse Events & Long-Term Safety Concerns of Therapies
- 4.3.2 Stringent, Multi-Regional Regulatory Approval Timelines
- 4.3.3 Escalating Therapy Costs & Reimbursement Hurdles
- 4.3.4 Limited Clinically Validated Biomarkers Delaying Adoption
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Treatment Type
- 5.1.1 Anti-viral Drugs
- 5.1.2 Immunosuppressants
- 5.1.3 Targeted Therapy & Small Molecules
- 5.1.4 Chemotherapy Drugs
- 5.1.5 Antifibrotic/Antisteatotic Agents
- 5.1.6 Vaccines
- 5.1.7 Immunoglobulins
- 5.2 By Disease Type
- 5.2.1 Viral Hepatitis (A-E)
- 5.2.2 Alcohol-Related Liver Disease (ARLD)
- 5.2.3 Metabolic Dysfunction-Associated Steatotic Liver Disease (MASLD) / MASH
- 5.2.4 Autoimmune Liver Diseases
- 5.2.5 Genetic & Pediatric Disorders
- 5.2.6 Other Disease Types
- 5.3 By Drug Class
- 5.3.1 Small-molecule Orals
- 5.3.2 Biologics & Monoclonal Antibodies
- 5.3.3 RNA-based Therapeutics
- 5.3.4 Cell & Gene Therapy
- 5.4 By Route of Administration
- 5.4.1 Oral
- 5.4.2 Injectable
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgery Centers
- 5.5.3 Specialty Clinics
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 AbbVie Inc.
- 6.3.3 Astellas Pharma Inc.
- 6.3.4 Alnylam Pharmaceuticals Inc.
- 6.3.5 Bristol-Myers Squibb Co.
- 6.3.6 F. Hoffmann-La Roche Ltd.
- 6.3.7 Gilead Sciences Inc.
- 6.3.8 GlaxoSmithKline plc
- 6.3.9 Merck & Co. Inc.
- 6.3.10 Novartis AG
- 6.3.11 Pfizer Inc.
- 6.3.12 Sanofi S.A.
- 6.3.13 Takeda Pharmaceutical Co.
- 6.3.14 Endo International plc
- 6.3.15 Provectus Biopharmaceuticals Inc.
- 6.3.16 Intercept Pharmaceuticals Inc.
- 6.3.17 Madrigal Pharmaceuticals Inc.
- 6.3.18 Eiger BioPharmaceuticals Inc.
- 6.3.19 Ionis Pharmaceuticals Inc.
- 6.3.20 Aligos Therapeutics Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment