

|
시장보고서
상품코드
2123389
세포배양 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Cell Culture - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
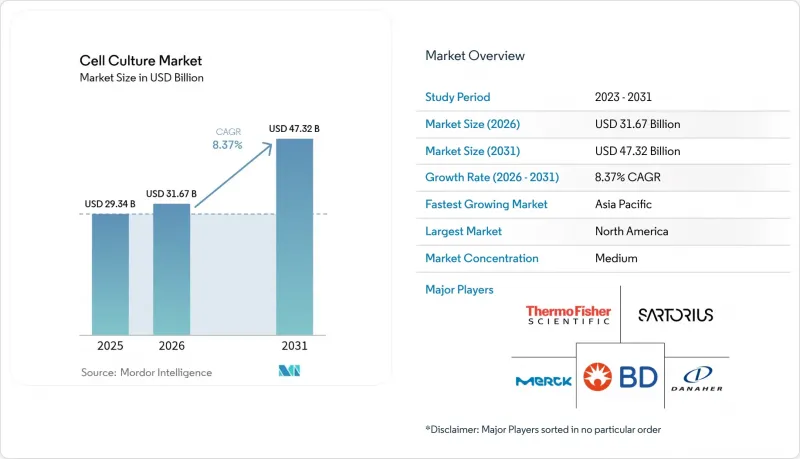
에 의하면, 세포배양 시장 규모는 2025년에 293억 4,000만 달러로 평가되었고, 2026년 316억 7,000만 달러에서 2031년까지 473억 2,000만 달러에 달할 것으로 예측됩니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 8.37%를 기록할 것으로 전망됩니다.
본 보고서는 제품별(장비 및 소모품), 세포 유형별(포유류 세포 등), 기술별(2차원 세포 배양 및 3차원 세포 배양), 용도별(바이오의약품 제조, 신약 개발 등),최종 사용자별(제약·바이오기술 기업 등), 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 세포 배양 시장 동향 및 인사이트
만성 질환의 전 세계적 부담 증가가 바이오의약품 수요를 견인
비감염성 질환 증가로 인해 바이오의약품 파이프라인은 지속적으로 확대되고 있으며, 각 제조업체는 단일클론 항체, 백신, GLP-1 제제를 뒷받침할 수 있는 배양 능력 확충을 불가피하게 하고 있습니다. 사노피는 수직 통합형 인슐린 제조 시설에 13억 유로를 투자하기로 결정했으며, 이는 환자 수가 많은 만성 질환의 적응증이 세포 배양 시장의 확대에 얼마나 직접적으로 기여하는지를 여실히 보여주고 있습니다. 암 분야가 이러한 압력을 더욱 가중시키고 있습니다. 전 세계적으로 60건 이상의 유도 만능 줄기세포(iPS 세포)를 이용한 임상시험이 진행 중이며, 그 중 약 3분의 1이 일본에서 이루어지고 있습니다. 일본에서는 신속 승인 제도를 통해 연구 단계에서 임상 적용까지의 기간이 단축되고 있습니다. 그 이유는 명백합니다. 만성 질환의 유병률이 확대됨에 따라, 세포 배양 시장은 사람들의 생산성을 유지하기 위한 치료의 기반을 제공해야 합니다.
자동화·고속 처리 세포 배양 시스템의 기술적 진보
밀폐형 일회용 바이오리액터와 AI를 통한 공정 제어의 급속한 보급으로 인해 오염 위험과 기술자의 작업 시간이 감소하는 동시에 배치 처리 능력이 두 배로 증가했습니다. 코펜하겐 시설 확장을 통해 2,000 L 용량의 일회용 용기 8기가 추가되어 연간 150배치 분량의 증산이 가능해졌습니다. 이는 기존의 물리적 설비 확장 없이도 자동화를 통해 생산 능력을 비약적으로 향상시킬 수 있음을 입증합니다. 액적 마이크로플루이딕스 기술을 통해 세포주 개발 리드타임이 더욱 단축되었으며, 수주가 걸리던 수작업에 의한 클론 선별이 수 분 만에 이루어지는 고정밀 디지털 선별로 대체되었습니다. 이러한 성과는 세포 배양 시장의 손익에 직접적인 영향을 미치며, 스폰서는 더 소규모의 환자 하위 그룹에 대해서도 경제적으로 접근할 수 있게 됩니다.
대규모 cGMP 세포 배양 시설의 막대한 자본 비용과 운영 비용
규정을 준수하는 생물제제 플랜트의 건설 비용은 1제곱피트당 500-1,400달러에 달할 전망입니다. 이러한 장벽으로 인해 스타트업 기업들은 아웃소싱 모델을 선택할 수밖에 없게 되었으며, 자금력이 제한적인 지역에서는 시설 확충이 지연되고 있습니다. 후지필름이나 론자 같은 자금력이 탄탄한 기존 기업조차도 확장을 위해 수억 단위의 비용을 지출해야만 하는 실정이며, 이것이 세포 배양 시장 진입을 가로막는 재정적 부담으로 작용하고 있음이 드러나고 있습니다.
부문 분석
2025년 기준, 소모품은 세포 배양 시장에서 59.20%라는 최대 점유율을 차지하고 있으며, 개발자들이 화학적으로 정의된 동물 유래 성분을 포함하지 않는 배지 조제로 전환함에 따라 이 부문은 2031년까지 연평균 성장률(CAGR) 8.27%로 확대될 것으로 예측됩니다. 이러한 변화는 다가오는 FBS(태아 소 혈청) 부족으로부터 사업자를 보호하는 것이며, 임상 자료에서 성분의 추적 가능성을 중시하는 규제 당국의 방침과도 부합합니다. 장비 측면에서는 일회용 바이오리액터, 퍼퓨전 플랫폼, 인라인 센서가 시설의 설계를 혁신적으로 변화시켜 가동 중단 시간과 자본 집약도를 줄이고 있습니다. 써모피셔가 41억 달러에 필터링 기술을 인수한 것은 견고한 연속 공정에서 정제 하드웨어가 얼마나 전략적인 요소가 되고 있는지를 여실히 보여줍니다. 자동화가 보급됨에 따라 소모품이 더 큰 수익 기반을 유지하더라도, 장비에 기인한 세포 배양 시장 규모는 과거 사이클보다 빠른 속도로 확대될 것입니다.
연구 개발(R&D) 실험실에서도 현미경과 이미징 시스템의 업데이트가 진행되고 있습니다. 요코가와 전기(Yokogawa Electric)의 CQ3000은 살아있는 세포의 3D 이미지를 촬영하여 이를 하류 AI 분석에 활용함으로써 분석법 개발 기간을 단축합니다. 일회용 튜브, 필터, 샘플링 포트는 일회용 생태계를 완성하며, 새로운 바이오리액터가 도입될 때마다 예측 가능한 소모품 수요를 확고히 하고 있습니다. 이러한 변화들이 맞물려 장비 혁신이 새로운 소모품 SKU를 창출하고, 그 반대의 경우도 마찬가지인 선순환이 확립되어 세포 배양 시장의 밸류체인을 풍요롭게 하고 있습니다.
2025년에는 포유류 플랫폼이 세포 배양 시장 점유율의 62.10%를 차지했습니다. 이는 주로 CHO 세포주가 여전히 단일 클론 항체의 주력으로 기능하고 있기 때문입니다. 그러나 줄기세포 분야가 가장 빠른 성장세를 보이고 있으며, 2024년 말 기준 전 세계 임상시험 건수가 115건에 달함에 따라 연평균 성장률(CAGR)은 8.25%로 성장을 지속하고, 있습니다. 일본의 규제 완화 조치와 공공 자금 투입으로 인해 iPS 세포 치료법은 상업적 승인 직전 단계에 이르렀으며, 이는 GMP 등급의 줄기세포 배지, 매트릭스 및 밀폐형 수확 시스템에 대한 수요의 전환점을 시사하고 있습니다.
포유류 세포주 중에서는 연구 측면에서 중요성이 높아지고 있는 것은 1세대 세포인 반면, 불사화 세포주는 신뢰성이 높은 생산용 주로서 공급되고 있습니다. 미생물 및 곤충 세포 시스템은 포유류 세포주로는 효율적으로 발현할 수 없는 틈새 단백질 표적이나 백신 항원에 대응하고 있으며, 보다 광범위한 세포 배양 시장에서 다양한 수요 패턴을 유지하고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 35.59%를 차지할 것으로 예상되며, 머크의 10억 달러 규모 ‘가다실’ 원료 제조 시설과 메릴랜드주에 위치한 아스트라제네카의 3억 달러 규모 세포 치료 공장 등 획기적인 확장 계획에 힘입고 있습니다. 2025년 이후 연간 20건의 첨단 치료법 승인이 예상되는 미국의 규제 환경은 새로 추가된 GMP 시설의 활용을 보장하고 있습니다. 캐나다는 CDMO를 유치하기 위한 세액 공제 제도를 통해 해당 지역의 성장을 뒷받침하고 있으며, 멕시코는 북미 대륙공급망을 지탱하는 충전·마감 및 부품 성형 능력을 제공합니다. 2040년까지 미국 화학물질 수요의 30%를 지속 가능한 바이오 제조로 충당하겠다는 연방 정부의 목표는 세포 배양 시장에 지속적인 정책적 호재로 작용하고 있습니다.
유럽에서는 강력한 추격세가 나타나고 있습니다. 독일의 생명공학 분야 자금 조달은 2024년에 19억 유로로 급증했으며, 영국은 팬데믹 위험을 헤지하기 위해 4억 5,000만 파운드 규모의 백신 허브를 출범시켰습니다. GMP 부속서 개정을 조화시키려는 EU의 노력은 국경을 초월한 제품 승인 절차를 간소화하고, 범유럽적 서비스 네트워크 구축을 뒷받침하고 있습니다. 또한 베를린에 위치한 바이엘의 유전자·세포 치료 센터와 같은 협력은 산업계 파트너들을 공공 과학 생태계로 끌어들이고 있습니다.
아시아태평양은 9.27%의 연평균 성장률(CAGR)을 기록하며 가장 빠른 성장세를 보이고 있습니다. 7억 6,000만 달러 규모의 일본 재생의학 프로그램은 60건 이상의 iPS 세포 임상시험을 창출하며, 사전 정의된 배지, 밀폐형 바이오리액터 및 다운스트림 공정 정제 스키드에 대한 국내 수요를 촉진하고 있습니다. 중국은 업스트림 공정의 항체 제조 플랜트와 신흥 mRNA 생산 라인을 모두 확대하고 있는 반면, 인도는 비용 면에서의 우위를 활용하여 위탁 제제 및 분석 분야에서 점유율 확대를 도모하고 있습니다. 한국과 호주는 각각 선진적인 줄기세포 제조 기술과 지원적인 보험 급여 제도를 통해 이 지역의 다양성을 한층 더 강화하고 있습니다. 전반적으로 아시아태평양의 인구 동향-고령화 진행과 만성 질환 발생률 증가-은 예측 기간을 넘어 지속될 세포 배양 시장 수요 증가를 확고히 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the cell culture market size was valued at USD 29.34 billion in 2025 and estimated to grow from USD 31.67 billion in 2026 to reach USD 47.32 billion by 2031, at a CAGR of 8.37% during the forecast period (2026-2031).
This report is Segmented by Product (Equipment and Consumables), Cell Type (Mammalian Cells, and More), Technology (2-D Cell Culture and 3-D Cell Culture), Application (Biopharmaceutical Production, Drug Discovery & Development, and More), End-User (Pharmaceutical & Biotechnology Companies, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cell Culture Market Trends and Insights
Rising Global Burden of Chronic Diseases Propelling Biologics Demand
Non-communicable diseases continue to swell biologics pipelines, compelling manufacturers to expand culture capacity that underpins monoclonal antibodies, vaccines, and GLP-1 therapeutics. Sanofi committed EUR 1.3 billion to a vertically integrated insulin facility, highlighting how large-volume chronic disease indications directly translate to cell culture market expansion. Oncology heightens this pressure; more than 60 induced-pluripotent-stem-cell trials are active worldwide, nearly one-third in Japan, where fast-track approvals shorten the path from bench to bedside. The arithmetic is clear: as chronic disease prevalence scales, the cell culture market must supply the therapeutic backbone that keeps populations productive.
Technological Advances in Automated & High-Throughput Cell-Culture Systems
Rapid uptake of closed, single-use bioreactors and AI-orchestrated process control cuts contamination risk and technician hours while doubling batch throughput. An expansion in Copenhagen added eight 2,000 L single-use vessels, enabling 150 extra batches each year and proving that automation can deliver step-change capacity without conventional brick-and-mortar scale-up. Droplet microfluidics further compresses cell-line development timelines, replacing weeks of manual clone picking with minutes of digital selection accuracy. These gains flow straight to the cell culture market P&L, letting sponsors pursue smaller patient sub-groups economically.
High Capital & Operating Costs of Large-Scale cGMP Cell-Culture Facilities
Constructing a compliant biologics plant can cost USD 500-1,400 per square foot, a hurdle that pushes start-ups toward outsourcing models and slows facility deployment in cash-limited geographies. Even deep-pocketed incumbents such as Fujifilm and Lonza accept nine-figure price tags for expansions, underscoring the financial gravity that drags on cell culture market entry.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Government & Private Funding for Cell-Based Research
- Growth in Cell- & Gene-Therapy Clinical Trial Pipeline Worldwide
- Stringent Regulatory & Quality-Compliance Requirements Across Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables retained the largest slice of the cell culture market in 2025 at 59.20%, and the segment is forecast to compound at 8.27% through 2031 as developers switch to chemically-defined, animal-free media formulations. This evolution protects operators against the looming FBS crunch and lines up with regulators who prefer traceable ingredients in clinical dossiers. On the equipment side, single-use bioreactors, perfusion platforms, and inline sensors are rewriting facility blueprints, trimming downtime and capital intensity. Thermo Fisher's USD 4.1 billion filtration acquisition underlines how purification hardware has become strategic to robust continuous processing. As automation proliferates, the cell culture market size attributable to equipment will rise faster than in prior cycles-even if consumables keep the larger revenue base.
R&D labs are likewise refreshing microscopes and imaging systems; Yokogawa's CQ3000 captures live 3D images that feed downstream AI analytics, shortening assay development. Disposable tubing, filters, and sampling ports complete the single-use ecosystem, locking in predictable consumables demand with every new bioreactor install. Together, these shifts cement a feedback loop where equipment innovation unlocks new consumables SKUs, and vice versa, enriching the cell culture market value chain.
Mammalian platforms generated 62.10% of the cell culture market share in 2025, in large part because CHO lines remain the workhorse for monoclonal antibodies. Yet stem cells post the fastest rise, tracking an 8.25% CAGR as global trials hit 115 at the end of 2024. Japan's regulatory accelerators and public funding have pulled induced-pluripotent-stem-cell therapies to the cusp of commercial approval, signaling a demand inflection for GMP-grade stem-cell media, matrices, and closed harvesting systems.
Within mammalian lines, primary cells win research relevance while immortalized lines supply reliable production titles. Microbial and insect cell systems address niche protein targets and vaccine antigens that mammalian lines fail to express efficiently, preserving a diversified demand pattern inside the broader cell culture market.
Complete Report Scope:
- By Product
- Equipment
- Biosafety Cabinets
- Centrifuges
- Cryostorage Equipment
- Culture Systems / Bioreactors
- Incubators
- Pipetting Instruments
- Microscopes & Imaging Systems
- Cell Counters & Analyzers
- Filtration Systems
- Accessories (Tubing, Connectors, Fittings)
- Consumables
- Media
- Serum-Free Media
- Sera (FBS & Alternatives)
- Reagents
- Buffers & Salts
- Supplements & Growth Factors
- Cryoprotective Agents
- Plasticware (Flasks, Plates, Dishes)
- Equipment
- By Cell Type
- Mammalian Cells
- Primary Cells
- Continuous Cell Lines
- Stem Cells
- Embryonic Stem Cells
- Adult Stem Cells
- Induced Pluripotent Stem Cells
- Microbial Cells
- Bacterial
- Yeast & Fungal
- Insect Cells
- Mammalian Cells
- By Technology
- 2-D Cell Culture
- 3-D Cell Culture
- Scaffold-Based
- Scaffold-Free
- By Application
- Biopharmaceutical Production
- Drug Discovery & Development
- Gene & Cell Therapy Manufacturing
- Vaccine Production
- Tissue Engineering & Regenerative Medicine
- Cancer Research
- Diagnostics & Assay Development
- Toxicity Testing & Safety Assessment
- By End-User
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutes
- CROs & CDMOs
- Hospitals & Diagnostic Laboratories
- Cell Banks & Biobanks
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 35.59% of global revenue in 2025, supported by landmark expansions such as Merck's USD 1 billion Gardasil ingredient facility and AstraZeneca's USD 300 million cell-therapy plant in Maryland. The U.S. regulatory climate, forecasting 20 annual advanced-therapy approvals from 2025 onward, guarantees utilization of newly added GMP suites. Canada bolsters the region with tax credits that entice CDMOs, and Mexico offers fill-finish and component-molding capacities that support continental supply chains. Federal ambitions to meet 30% of U.S. chemical demand with sustainable biomanufacturing by 2040 provide an enduring policy tailwind for the cell culture market.
Europe presents strong catch-up momentum. German biotech financing rocketed to EUR 1.9 billion in 2024, and the United Kingdom unveiled a GBP 450 million vaccine hub to hedge pandemic risk. EU efforts to harmonize GMP annex updates streamline cross-border product release and favor pan-European service networks. Furthermore, collaborations such as Bayer's gene- and cell-therapy center in Berlin pull industrial partners into public-science ecosystems.
Asia-Pacific registers the fastest climb, clocking a 9.27% CAGR. Japan's USD 760 million regenerative-medicine program spawns more than 60 iPSC trials and primes domestic demand for defined media, closed bioreactors, and downstream purification skids. China scales both upstream antibody plants and emergent mRNA lines, while India monetizes cost advantages to capture contract formulation and analytics. South Korea and Australia round out the regional mosaic with advanced stem-cell manufacturing and supportive reimbursement regimes, respectively. Collectively, APAC's demographic profile-aging populations and growing chronic disease incidence-cements a demand runway for the cell culture market that stretches beyond the forecast period.
- Thermo Fisher Scientific
- Merck
- Sartorius
- Danaher
- Corning
- Lonza Group Ltd.
- Eppendorf
- Beckton Dickinson
- Agilent Technologies
- Bio-Rad Laboratories
- PromoCell
- Tecan Group
- CellGenix
- FUJIFILM Irvine Scientific Inc.
- Greiner Bio One International
- Hi-Media Laboratories Pvt Ltd.
- Biospherix Ltd.
- XenoTech
- Miltenyi Biotec B.V. & Co. KG
- Advanced Instrumentations
- Stem Cell Technologies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Burden of Chronic Diseases Propelling Biologics Demand
- 4.2.2 Technological Advances in Automated & High-Throughput Cell-Culture Systems
- 4.2.3 Expanding Government & Private Funding for Cell-Based Research
- 4.2.4 Growth in Cell- & Gene-Therapy Clinical Trial Pipeline Worldwide
- 4.2.5 Increasing Adoption of Cell-Based Assays in Drug Discovery & Toxicity Testing
- 4.2.6 Shift Toward Animal-Component-Free and Sustainable Biomanufacturing Practices
- 4.3 Market Restraints
- 4.3.1 High Capital & Operating Costs of Large-Scale cGMP Cell-Culture Facilities
- 4.3.2 Stringent Regulatory & Quality-Compliance Requirements Across Regions
- 4.3.3 Contamination Risk and Batch-Failure Impact on Production Economics
- 4.3.4 Supply-Chain Vulnerabilities for Critical Media, Plastics, and Reagents
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Buyers
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Equipment
- 5.1.1.1 Biosafety Cabinets
- 5.1.1.2 Centrifuges
- 5.1.1.3 Cryostorage Equipment
- 5.1.1.4 Culture Systems / Bioreactors
- 5.1.1.5 Incubators
- 5.1.1.6 Pipetting Instruments
- 5.1.1.7 Microscopes & Imaging Systems
- 5.1.1.8 Cell Counters & Analyzers
- 5.1.1.9 Filtration Systems
- 5.1.1.10 Accessories (Tubing, Connectors, Fittings)
- 5.1.2 Consumables
- 5.1.2.1 Media
- 5.1.2.2 Serum-Free Media
- 5.1.2.3 Sera (FBS & Alternatives)
- 5.1.2.4 Reagents
- 5.1.2.5 Buffers & Salts
- 5.1.2.6 Supplements & Growth Factors
- 5.1.2.7 Cryoprotective Agents
- 5.1.2.8 Plasticware (Flasks, Plates, Dishes)
- 5.1.1 Equipment
- 5.2 By Cell Type
- 5.2.1 Mammalian Cells
- 5.2.1.1 Primary Cells
- 5.2.1.2 Continuous Cell Lines
- 5.2.2 Stem Cells
- 5.2.2.1 Embryonic Stem Cells
- 5.2.2.2 Adult Stem Cells
- 5.2.2.3 Induced Pluripotent Stem Cells
- 5.2.3 Microbial Cells
- 5.2.3.1 Bacterial
- 5.2.3.2 Yeast & Fungal
- 5.2.4 Insect Cells
- 5.2.1 Mammalian Cells
- 5.3 By Technology
- 5.3.1 2-D Cell Culture
- 5.3.2 3-D Cell Culture
- 5.3.2.1 Scaffold-Based
- 5.3.2.2 Scaffold-Free
- 5.4 By Application
- 5.4.1 Biopharmaceutical Production
- 5.4.2 Drug Discovery & Development
- 5.4.3 Gene & Cell Therapy Manufacturing
- 5.4.4 Vaccine Production
- 5.4.5 Tissue Engineering & Regenerative Medicine
- 5.4.6 Cancer Research
- 5.4.7 Diagnostics & Assay Development
- 5.4.8 Toxicity Testing & Safety Assessment
- 5.5 By End-User
- 5.5.1 Pharmaceutical & Biotechnology Companies
- 5.5.2 Academic & Research Institutes
- 5.5.3 CROs & CDMOs
- 5.5.4 Hospitals & Diagnostic Laboratories
- 5.5.5 Cell Banks & Biobanks
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Thermo Fisher Scientific Inc.
- 6.3.2 Merck KGaA
- 6.3.3 Sartorius AG
- 6.3.4 Danaher Corporation
- 6.3.5 Corning Incorporated
- 6.3.6 Lonza Group Ltd.
- 6.3.7 Eppendorf SE
- 6.3.8 Becton, Dickinson and Company
- 6.3.9 Agilent Technologies Inc.
- 6.3.10 Bio-Rad Laboratories Inc.
- 6.3.11 Promocell GmbH
- 6.3.12 Tecan Group Ltd.
- 6.3.13 CellGenix GmbH
- 6.3.14 FUJIFILM Irvine Scientific Inc.
- 6.3.15 Greiner Bio-One International GmbH
- 6.3.16 Hi-Media Laboratories Pvt Ltd.
- 6.3.17 Biospherix Ltd.
- 6.3.18 Sekisui XenoTech LLC
- 6.3.19 Miltenyi Biotec B.V. & Co. KG
- 6.3.20 Advanced Instruments LLC
- 6.3.21 STEMCELL Technologies Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


