|
시장보고서
상품코드
2124209
중동 및 아프리카의 디지털 옥외광고(DOOH) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Middle East And Africa Digital Out Of Home (DOOH) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
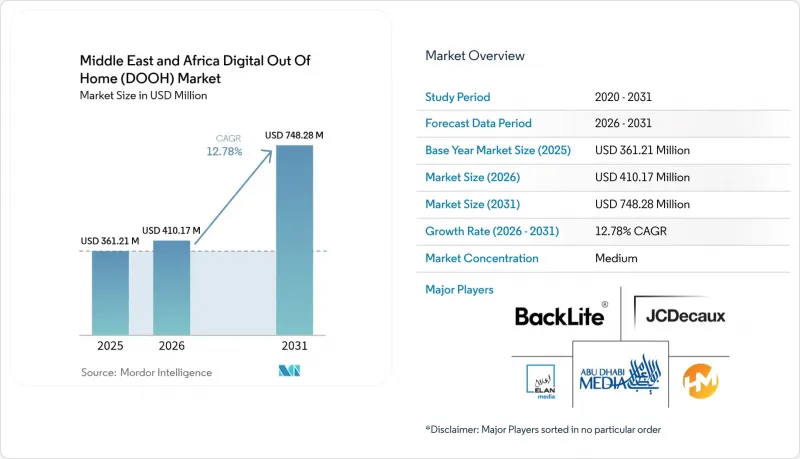
에 의하면, 중동 및 아프리카의 디지털 옥외광고(DOOH) 시장 규모는 2025년 3억 6,121만 달러로 평가되었고, 2026년 4억 1,017만 달러에서 2031년까지 7억 4,828만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 12.78%를 나타낼 전망입니다.
본 보고서는 서비스 유형별(프로그래매틱 DOOH 및 비프로그래매틱 DOOH), 용도별(빌보드, 대중교통, 가로 시설물, 기타), 입지 환경별(도로변 옥외, 공항, 쇼핑몰 및 교통 거점, 기타), 최종 사용자 산업별(자동차, 소매, 헬스케어, 은행 및 금융 서비스(BFSI), 미디어 및 엔터테인먼트, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 아프리카의 디지털 옥외광고(DOOH) 시장 동향 및 인사이트
디지털 광고로의 지속적인 전환
광고 예산은 비닐 간판에서 측정 가능한 노출과 신속한 크리에이티브 교체가 가능한 네트워크화된 스크린으로 이동하고 있습니다. 이집트의 DOOH 재고는 2023-2024년 두 배로 증가했으며, 2025년 11월에는 디지털 점유율이 90.1%에 달한 것으로 나타나, 매체 형태의 대체가 진행되고 있음을 여실히 보여주었습니다. 아랍에미리트에서는 규제 당국이 정적 광고 매체의 폐지 기한을 명확히 정한 결과, 2025년 말까지 옥외 광고 면적의 70% 이상이 디지털화된 것으로 확인되었습니다. ELAN Media 등 광고 슬롯을 공급측 플랫폼(SSP)에 연결한 사업자의 경우, 2025년에 디지털 광고 매출 비중이 50%를 넘어 2020년의 거의 제로 수준에서 극적인 전환을 이루었습니다. 이러한 성장은 스크린 노출을 계기로 소셜 채널에서 후속 광고가 표시되는 ‘모바일 리타게팅’에 의해 더욱 가속화되고 있으며, 브랜드가 소비자의 구매 과정을 추적하는 데 도움이 되고 있습니다. 이러한 요인들이 복합적으로 작용하여 중동 및 아프리카의 DOOH 시장은 급격한 전환 곡선을 그리고 있습니다.
대중교통 인프라 확충
디지털 스크린용 배선이 사전에 구축된 지하철, 공항, 버스 정류장에 수십억 달러가 투자되고 있습니다. 리야드 메트로는 6개 노선에 걸쳐 2,688대의 디스플레이를 통합하고, Saudi Signs Media에 독점적인 미디어 권리를 제공합니다. 두바이에서는 2025년 12월까지 595개의 스마트 버스 정류장이 가동될 예정이며, 각 버스 정류장에는 승객용 Wi-Fi와 프로그래매틱 광고 트리거에 대응하는 패널이 설치되어 있습니다. 주요 걸프 국가들의 공항도 유사한 구상을 채택하고 있으며, 두바이 국제공항만 해도 Play+ 플랫폼을 통해 제어 가능한 JCDecaux제 패널 378기가 설치되어 있습니다. 카타르의 ‘플레이스 방돔(Place Vendome)’과 같은 플래그십 쇼핑몰 내 평균 체류 시간이 100분에 달하는 점도 교통과 연계된 환경에 대한 광고 지출을 더욱 촉진하고 있습니다. 이러한 시설들은 예측 가능한 방문객 수를 확보하고 있으며, 이는 프리미엄 CPM(노출당 단가)을 정당화하고 자산 소유주에게 장기적인 수익 전망을 뒷받침하고 있습니다.
GCC의 엄격한 광고 규제
두바이의 제6-2020호 행정령에 따르면, 모든 광고 크리에이티브는 여러 기관의 심사를 통과해야 하며, 이로 인해 리드타임이 길어질 뿐만 아니라 규정 준수 관련 비용도 증가하고 있습니다. 또한, RTA(두바이 도로교통청) 매뉴얼에는 밝기, 애니메이션 길이, 기밀성이 높은 시설과의 근접성에 대한 상한선이 정해져 있습니다. 사우디아라비아에서는 사이버 보안법에 따라 특정 DOOH 네트워크가 중요 인프라로 분류되어 있으며, 사업자는 보안 감사 및 사고 보고서 제출을 의무화하고 있습니다. 수동 컨텐츠 심사는 실시간 입찰 논리와 상충되므로, 프로그래매틱의 매력을 뒷받침하는 유연성의 일부가 훼손되고 있습니다. 그 결과, 법무 자원이 부족한 중소 광고주는 정적 광고 공간 구매에 그치거나 이 매체 자체를 피할 가능성이 있어, 중동 및 아프리카 DOOH 시장이 100% 디지털화로 전환되는 속도를 늦추는 요인이 되고 있습니다.
부문 분석
프로그래매틱 광고는 여전히 매출에서 소수파이지만, 그 연평균 성장률(CAGR)은 기존 계약 방식을 상회하고 있습니다. 2025년 현재, 중동 및 아프리카 DOOH 시장 점유율의 70.88%를 비프로그래매틱 인벤토리가 차지했으며, 이는 대형 광고주와 미디어 소유자 간의 직접적인 관계가 정착되어 있음을 반영합니다. Saudi Signs Media와 리야드 메트로 간의 계약과 같은 독점적 운영권 계약은 다년간의 보장을 통해 수익원을 확보하고 있으며, 이러한 모델이 여전히 뿌리 깊게 남아 있는 이유를 설명해 줍니다. Play+와 같은 플랫폼에서는 구매자가 예산을 시간 단위나 일 단위로 유연하게 배분할 수 있어, 성과 중심의 브랜드에게 매력적인 선택지가 되고 있습니다.
향후 5년 동안 자동 구매가 연평균 13.29%의 지속적인 성장을 기록함에 따라 그 격차는 점차 줄어들 것으로 예측됩니다. 사업자들이 전 세계 SSP와 연계함에 따라 통합 장벽은 낮아지고 있으며, 옴니채널 트레이더들은 셰이크 자이드 로드, 바레인 국제공항, 도하의 고급 쇼핑몰 등에 원클릭으로 접근할 수 있게 되었습니다. 통신 사업자들이 GCC 도시 지역의 90% 이상을 커버하는 5G를 구축함에 따라, 지연으로 인한 제약이 실시간 최적화를 방해하는 일은 더 이상 없습니다. 그 결과, 중동 및 아프리카 DOOH 시장 규모 중 프로그래매틱 광고가 차지하는 비중은 수 배로 확대될 것으로 예상되지만, 주요 교통 시설에서의 장기 스폰서십 여지도 여전히 남아 있습니다.
임팩트가 큰 도로변 간판 덕분에 2025년 매출의 45.79%를 빌보드가 차지했지만, 도시 시설물 및 역 내 디스플레이는 연평균 성장률(CAGR) 14.17%라는 빠른 속도로 확대되고 있습니다. Wi-Fi, QR 코드, 승객 정보 화면을 갖춘 버스 정류장은 지나가는 행인의 순간적인 관심을 측정 가능한 참여로 전환합니다. 지하철 승강장은 더 큰 가치를 제공합니다. 통근자가 열차를 기다리는 시간은 최대 8분에 달하며, 승객 1인당 여러 번의 노출 기회가 생성됩니다.
향후 공공시설의 디지털화로 인해, 과거 도로변의 정적 간판에 고정되어 있던 예산이 재분배될 것입니다. 지자체는 천 소재 비닐에 비해 시각적인 어수선함이 적은 슬림형 LED를 선호하며, 광고주는 재인쇄 비용을 들이지 않고 시간대별로 광고 컨텐츠를 변경할 수 있는 점을 높이 평가했습니다. 이러한 양측 수요로 인해 중동 및 아프리카의 DOOH 시장에서 ‘기타 용도’ 부문 시장 규모가 기존 간판의 주요 부문에 비해 비례적으로 확대되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the Middle East and Africa DOOH market size size is projected to expand from USD 361.21 million in 2025 and USD 410.17 million in 2026 to USD 748.28 million by 2031, registering a CAGR of 12.78% between 2026 to 2031.
This report is Segmented by Service Type (Programmatic-DOOH, and Non-Programmatic-DOOH), Application (Billboard, Transit, Street Furniture, and More), Location Environment (Roadside Outdoor, Airports, Mall and Transit Hubs, and More), End-User Industry (Automotive, Retail, Healthcare, BFSI, Media and Entertainment, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Digital Out Of Home (DOOH) Market Trends and Insights
Ongoing Shift Toward Digital Advertising
Ad budgets are moving from vinyl billboards to networked screens that deliver measurable impressions and quick creative swaps. Egypt's DOOH inventory doubled between 2023 and 2024 and digital occupancy hit 90.1% in November 2025, underscoring format substitution momentum. The UAE confirmed that more than 70% of its outdoor faces were digital by end-2025 after regulators set firm retirement dates for static units. Operators that connected inventory to supply-side platforms, such as ELAN Media, saw digital contributions pass 50% of revenue in 2025, a dramatic swing from negligible levels in 2020. The growth is reinforced by mobile-retargeting, where a screen exposure triggers a follow-up ad on social channels, helping brands trace the consumer journey. Together, these factors keep the Middle East and Africa DOOH market on a steep replacement curve.
Expansion of Public-Transit Infrastructure
Billions of U.S. dollars are flowing into metros, airports, and bus shelters that are pre-wired for digital screens. Riyadh Metro integrates 2,688 displays across six lines, offering exclusive media rights to Saudi Signs Media. In Dubai, 595 smart bus shelters were in service by December 2025, each featuring passenger Wi-Fi and panels ready for programmatic triggers. Major Gulf airports have adopted a similar blueprint, with Dubai International alone hosting 378 JCDecaux panels addressable through the Play+ platform. Average dwell times of 100 minutes inside flagship malls such as Place Vendome in Qatar further tilt spend toward transit-linked environments. These venues offer predictable footfall that justifies premium CPMs and underpins long-run revenue visibility for asset owners.
Stringent Advertising Regulations in GCC
Dubai's Decree 6-2020 requires every creative to clear multiple agencies, stretching lead times and adding compliance expenses. The RTA manual further caps brightness, animation length, and proximity to sensitive sites. In Saudi Arabia, cybersecurity laws classify certain DOOH networks as critical infrastructure, obliging operators to file security audits and incident reports. Manual content reviews clash with real-time bidding logic, muting some of the flexibility that makes programmatic attractive. Smaller advertisers lacking legal resources may therefore stick to static buys or avoid the medium altogether, tempering the pace at which the Middle East and Africa DOOH market migrates to 100% digital.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Adoption of Programmatic DOOH
- Saudi Giga-Projects Boosting Smart-City Media
- Persistence of Traditional OOH in Rural Areas
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Programmatic still represents a minority of sales, yet its CAGR outpaces that of traditional contracts. Non-programmatic inventory accounted for 70.88% of Middle East and Africa DOOH market share in 2025, reflecting entrenched direct media-owner relationships with large advertisers. Exclusive concessions, such as Saudi Signs Media's Riyadh Metro deal, lock in revenue streams through multi-year guarantees, explaining why the model endures. Nevertheless, platforms like Play+ let buyers pulse budgets by hour or day, which is proving persuasive for performance-led brands.
In the next five years, sustained 13.29% growth for automated buying will compress that gap. Integration friction is falling as operators connect to global SSPs, giving omnichannel traders one-click access to Sheikh Zayed Road, Bahrain International Airport, or Doha's luxury malls. With telecom operators rolling out 5G that covers more than 90% of GCC urban centers, latency constraints no longer block real-time optimisation. As a result, the Middle East and Africa DOOH market size attributable to programmatic lines is forecast to multiply while still leaving room for long-duration sponsorships in flagship transit estates.
Billboards retained 45.79% of 2025 revenue thanks to high-impact roadside canvases, yet street furniture and in-station displays are scaling faster at a 14.17% CAGR. Bus shelters fitted with Wi-Fi, QR codes, and passenger information screens convert fleeting passerby attention into measurable engagements. Metro platforms add further value, as commuters spend up to eight minutes awaiting trains, creating multiple impression windows per passenger.
Over time, digital enablement of public furniture will redirect budgets once locked into static roadside walls. Municipalities prefer the low visual clutter of slim LED to fabric vinyl, and advertisers appreciate creative rotation by daypart without re-printing costs. This twin preference supports a proportional rise in the Middle East and Africa DOOH market size generated by "other applications" relative to legacy billboard strongholds.
Complete Report Scope:
- By Service Type
- Programmatic-DOOH
- Non-Programmatic-DOOH
- By Application
- Billboard
- Transit
- Street Furniture
- Other Applications
- By Location Environment
- Roadside Outdoor
- Airports
- Malls and Transit Hubs
- In-Store and Indoor Venues
- Other Location Environments
- By End-User Industry
- Automotive
- Retail
- Healthcare
- Banking and Financial Services (BFSI)
- Media and Entertainment
- Other End-User Industries
- By Geography
- Saudi Arabia
- United Arab Emirates
- Kuwait
- Qatar
- Morocco
- Egypt
- Rest of Middle East and Africa
List of Companies Covered in this Report:
- JCDecaux SE
- ELAN Media W.L.L.
- BackLite Media LLC
- Hypermedia FZ LLC
- Abu Dhabi Media Company PJSC
- Dooha Media W.L.L.
- EyeMedia Advertising W.L.L.
- Pikasso SARL
- Elevision Media FZ LLC
- Al Arabia Outdoor Advertising CJSC
- Faden Media Company Ltd.
- Hills Advertising LLC
- Arabian Outdoor Advertising LLC
- MBC Media Solutions FZ LLC
- Al Barq Digital Media LLC
- Publicity Qatar W.L.L.
- Sahara Media Advertising Co. LLC
- Ethraa Advertising Company LLC
- Wow Media LLC
- Al Fahad Advertising LLC
- Blue Rhine Media LLC
- Pixcom Technologies LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ongoing Shift Toward Digital Advertising
- 4.2.2 Expansion of Public-Transit Infrastructure
- 4.2.3 Accelerating Adoption of Programmatic DOOH
- 4.2.4 Saudi Giga-Projects Boosting Smart-City Media
- 4.2.5 5G-Enabled Real-Time Dynamic Creative Triggers
- 4.2.6 ESG Push for Renewable-Powered LED Displays
- 4.3 Market Restraints
- 4.3.1 Stringent Advertising Regulations in GCC
- 4.3.2 Persistence of Traditional OOH in Rural Areas
- 4.3.3 Fragmented Audience-Measurement Standards
- 4.3.4 High Ambient-Temperature Maintenance Costs
- 4.4 Impact of Macroeconomic Factors
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Programmatic-DOOH
- 5.1.2 Non-Programmatic-DOOH
- 5.2 By Application
- 5.2.1 Billboard
- 5.2.2 Transit
- 5.2.3 Street Furniture
- 5.2.4 Other Applications
- 5.3 By Location Environment
- 5.3.1 Roadside Outdoor
- 5.3.2 Airports
- 5.3.3 Malls and Transit Hubs
- 5.3.4 In-Store and Indoor Venues
- 5.3.5 Other Location Environments
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Retail
- 5.4.3 Healthcare
- 5.4.4 Banking and Financial Services (BFSI)
- 5.4.5 Media and Entertainment
- 5.4.6 Other End-User Industries
- 5.5 By Geography
- 5.5.1 Saudi Arabia
- 5.5.2 United Arab Emirates
- 5.5.3 Kuwait
- 5.5.4 Qatar
- 5.5.5 Morocco
- 5.5.6 Egypt
- 5.5.7 Rest of Middle East and Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 JCDecaux SE
- 6.4.2 ELAN Media W.L.L.
- 6.4.3 BackLite Media LLC
- 6.4.4 Hypermedia FZ LLC
- 6.4.5 Abu Dhabi Media Company PJSC
- 6.4.6 Dooha Media W.L.L.
- 6.4.7 EyeMedia Advertising W.L.L.
- 6.4.8 Pikasso SARL
- 6.4.9 Elevision Media FZ LLC
- 6.4.10 Al Arabia Outdoor Advertising CJSC
- 6.4.11 Faden Media Company Ltd.
- 6.4.12 Hills Advertising LLC
- 6.4.13 Arabian Outdoor Advertising LLC
- 6.4.14 MBC Media Solutions FZ LLC
- 6.4.15 Al Barq Digital Media LLC
- 6.4.16 Publicity Qatar W.L.L.
- 6.4.17 Sahara Media Advertising Co. LLC
- 6.4.18 Ethraa Advertising Company LLC
- 6.4.19 Wow Media LLC
- 6.4.20 Al Fahad Advertising LLC
- 6.4.21 Blue Rhine Media LLC
- 6.4.22 Pixcom Technologies LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment