|
시장보고서
상품코드
2124343
인도의 냉장고 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Refrigerator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
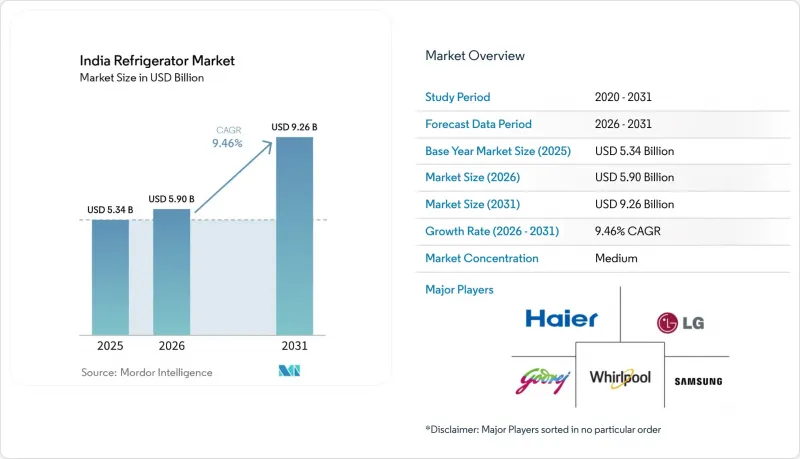
에 의하면, 인도의 냉장고 시장 규모는 2025년 53억 4,000만 달러로 평가되었고, 2026년에는 59억 달러로 추정되고, 2026-2031년 CAGR 9.46%로 성장을 지속할 전망이며, 2031년에는 92억 6,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 제품별(싱글도어, 더블도어 등), 구조별(빌트인형 및 프리스탠딩형), 용량별(15입방피트 미만 및 15입방피트 이상과), 최종 사용자별(가정용 및 상업용), 유통 채널별(B2C/소매 및 B2B), 지역별(북인도, 남인도, 서인도, 동인도)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도의 냉장고 시장 동향 및 인사이트
가처분 소득 증가 및 2·3선 도시의 전력 보급률 향상
인도의 냉장고 시장은 가처분 소득 증가와 2·3선 도시의 전기 보급률 향상에 힘입어 강력한 성장을 이루고 있습니다. 신뢰할 수 있는 전력 공급이 더 많은 가구에 확대됨에 따라, 현대적이고 에너지 효율이 높은 냉장고에 대한 수요는 기존의 도심 지역을 넘어 확장되고 있습니다. 중소도시의 소비자들도 양문형 및 다문형 냉장고를 포함한 중급에서 고급 모델까지 구매할 수 있게 되었습니다. 이러한 변화는 에너지 효율과 성능을 향상시키는 스마트 인버터 기술의 보급을 뒷받침하고 있습니다. 소매업체와 제조업체는 이러한 신흥 시장에서 유통 네트워크와 전자상거래를 확대함으로써 이러한 추세에 대응하고 있습니다. 전반적으로 2·3급 도시는 중요한 성장 동력이 되고 있으며, 인도 전체 냉장고 시장의 확대에 크게 기여하고 있습니다.
압축기 제조에 대한 PLI 제도 및 ‘메이크 인 인디아’를 통한 지원
인도 정부의 PLI 제도 및 ‘메이크 인 인디아’ 이니셔티브는 냉장고 부품, 특히 압축기의 국내 생산을 크게 촉진하고 있습니다. 하이얼의 그레이터 노이다 지역 확장 및 인쇄 회로 기판과 사출 성형 부품에 걸친 부품 내재화를 심화하기 위한 계획적인 생산 능력 투자에서 볼 수 있듯이, 국내 기업들은 설비 업그레이드와 신규 생산 라인 도입에 힘입어 냉장고의 현지 조달률을 높이고 있습니다. 마찬가지로, 삼성은 타밀나두주 스리펠룸부두르에 냉장고용 압축기 제조 공장을 설립하기 위해 약 2억 달러를 투자하겠다고 발표했으며, 현지 부품 생태계를 확대하기 위해 주 정부와 양해각서(MoU)를 체결했습니다. 22에이커 규모의 새로운 시설에서는 삼성의 인도산 냉장고용 및 수출용 압축기를 생산하여 국내 생산 능력을 강화하게 될 것입니다. 이러한 투자는 수입 의존도를 낮출 뿐만 아니라, 견고한 현지 부품 생태계를 구축하고, 공급망의 회복력을 높이며, 생산 비용을 절감하는 데에도 기여할 것입니다. 중소 제조업체들도 참여하고 있으며, 정부의 우대 조치를 활용하여 자동화, 에너지 절약형 생산, 숙련된 인력 양성에 투자함으로써 품질 기준을 향상시키고 있습니다. 이러한 노력들이 결합되어 생산 능력 확대를 가속화하고, 혁신을 촉진하며, 경쟁력을 높여 Tier 1, Tier 2, Tier 3 각 도시에서 인도 냉장고 시장의 급속한 성장을 뒷받침할 것으로 기대됩니다.
전력 및 전압의 불안정성이 준도시 지역의 송전망에 계속해서 영향을 미치고 있습니다.
전압 변동은 특히 여름 성수기에 인도 북부 및 동부의 준도시 지역과 소규모 마을에서 뿌리 깊은 문제로 대두되고 있습니다. 이러한 변동으로 인해 종종 안정기 사용이 필요하게 되며, 그 결과 실질적인 구매 비용이 증가하고, 안정기가 필요 없는 저가형 모델의 선택지가 제한되고 있습니다. 폭염 시 부하 급증은 저가형 냉장고의 압축기 부품에 손상을 줄 수 있으며, 이는 보증 청구 증가로 이어지고, 구매 결정에 입소문이 큰 영향을 미치는 시장에서 브랜드 신뢰도를 떨어뜨리는 요인이 되고 있습니다. 중저가 및 고급 모델에서는 인버터 기술이나 전압 안정기가 필요 없는 작동 방식이 점점 더 많이 채택되고 있지만, 합리적인 가격대의 부문에서는 이러한 기능이 여전히 부족하여 농촌 및 준도시 지역 가정에서의 보급을 지연시키고 있습니다. 게다가 사후 서비스망이 미비하여 수리에 시간이 오래 걸리고 물류 비용도 증가하고 있어, 전력망에서 벗어난 지역이나 서비스가 제대로 제공되지 않는 지역의 소비자들을 더욱 멀어지게 하고 있습니다. 태양광 발전 및 축전지에 대응하는 냉장고 도입을 위한 노력은 진행되고 있으나, 높은 가격으로 인해 저소득층에 대한 보급은 여전히 제한되고 있습니다.
부문 분석
2025년, 인도 냉장고 시장에서 양문형 냉장고는 39.46%의 시장 점유율을 차지했습니다. 또한, 프리미엄 모델의 보급이 가속화됨에 따라 2031년까지 사이드 바이 사이드형이 11.46%라는 가장 높은 성장률을 보일 것으로 예측됩니다. 프렌치 도어형 냉장고는 넉넉한 신선도 유지실과 사용하기 편리한 하단에 배치된 냉동실을 원하는 가정들 사이에서 인기가 높아지고 있습니다. 각 브랜드는 일상적인 사용 편의성을 높이고, 계획적인 식료품 구매를 위한 사전 냉각 습관을 지원하기 위해 냉동실 용도 변경 기능, 급속 냉각 모드, 소음 저감 등의 기능에 주력하고 있습니다. 사이드 바이 사이드 부문의 가격대 폭이 넓기 때문에 각 브랜드는 가성비를 중시하는 구매자층과 첨단 연결성 및 스마트 디스플레이 기능을 갖춘 하이엔드층을 모두 타겟으로 삼을 수 있습니다. 한편, 소규모 마을에서는 여전히 보급형 싱글 도어 직접 냉각식 냉장고에 대한 수요가 있지만, 냉장고를 처음 구매하는 계층에서는 대용량의 노프rost식 더블 도어 모델을 선택하는 경향이 강해지고 있습니다. 이러한 변화는 신흥 도시 지역의 가정이 대형 냉장고를 더 쉽게 구입할 수 있도록 해주는 유연한 금융 옵션에 의해 더욱 가속화되고 있습니다.
인도의 냉장고 라인업은 진화하는 소비자의 기대에 부응하기 위해 에너지 효율, 스마트 진단 기능, 더 빠른 냉각 주기에 중점을 두고 개편되고 있습니다. 프렌치 도어 디자인은 기능적인 용량과 고급스러운 외관을 겸비하고 있으며, 무광 마감, 유리문, 신선식품용 팬트리 스타일 수납 공간 등을 갖추고 있습니다. 사이드 바이 사이드 모델은 특히 가처분 소득이 높고 효율적인 인버터 시스템에 적합한 전기 요금 체계를 갖춘 도시 지역에서 대가족이나 손님을 자주 초대하는 사람들로부터 계속해서 지지를 받고 있습니다. 디자이너 마감 처리 덕분에 구조 변경 없이 주방을 업그레이드할 수 있어, 하이엔드 모델의 사후 도입 장벽이 낮아지고 있습니다. 프리미엄 가격대에서는 고도화된 커넥티드 기능이 제공되는 반면, 인버터 압축기를 탑재한 중급형 냉장고가 여전히 가장 널리 보급되어 있습니다. 전반적으로 시장에서는 기본적인 엔트리 모델에서 용량, 편의성, 라이프스타일 선호도를 균형 있게 겸비한 기능이 풍부한 냉장고로 서서히 전환되고 있습니다.
2025년 시장 규모에서 독립형 냉장고는 81.58%를 차지했으나, 인도 냉장고 시장에서 모듈식 캐비닛이 주요 대도시권 이외의 지역으로도 보급됨에 따라 빌트인형 제품은 2031년까지 10.84%의 성장 궤도에 올라 있습니다. 이 유형의 채택이 가장 활발한 곳은 시각적인 통일감을 중시하며, 위치 조정, 통풍, 패널 통합 등의 설치 요건을 충족할 수 있는 가구입니다. 각 브랜드는 빌트인형의 미관을 재현한 패널 지원형 독립형 냉장고를 출시하여, 주방 레이아웃을 변경할 수 없는 임대 주택 거주자나 이사가 잦은 비즈니스맨들에게 어필하고 있습니다. 스테인리스, 유리, 무광 마감의 채택이 증가하고 있는 것은 가전제품이 인테리어 전체의 디자인을 보완하는 디자인 요소로 기능한다는 추세를 반영하고 있습니다. 그럼에도 불구하고, 설치의 복잡성이나 높은 가격과 같은 요인으로 인해 많은 중소 도시에서는 본격적인 빌트인형 냉장고의 보급이 제한되고 있으며, 독립형 냉장고가 여전히 주류를 이루고 있습니다. 모듈러 주방의 개념이 확산됨에 따라, 특히 프리미엄층 소비자를 중심으로 빌트인 대응 모델에 대한 관심이 점차 높아지고 있습니다.
모듈형 주방을 표준 설비로 제공하는 개발사를 포함해 각 기업은 빌트인형 및 패널 호환 모델의 구매 주기를 가속화하고 있습니다. 소매업체와 브랜드 스튜디오는 현재 컬러 패널과 디자인에 조화를 이루는 마감을 강조하고 있으며, 이를 통해 제품의 가시성이 향상되고 주방 전면 리모델링을 계획할 때 소비자의 불안을 완화하고 있습니다. 서비스 파트너는 전문적인 설치 및 정확한 패널 정렬을 지원할 수 있는 체계를 갖추고 있어, 설치 후 문제를 최소화하고 전반적인 만족도를 높이고 있습니다. 부품의 현지 조달률 향상으로 생산 비용이 절감되어 프리미엄 라인공급 안정성이 강화되었습니다. 한편, 이동의 편의성, 임대 주택의 사정, 비용 측면을 고려하여 대부분의 지역에서는 여전히 독립형 냉장고가 선호되고 있습니다. 전반적으로 빌트인형 냉장고는 도시 지역 및 고소득층 시장에서 입지를 다지고 있지만, 예측 기간 동안 인도 전역에서는 독립형 냉장고가 주류를 이어갈 것으로 예측됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the India refrigerator market size is expected to grow from USD 5.34 billion in 2025 to USD 5.90 billion in 2026 and is forecast to reach USD 9.26 billion by 2031 at a 9.46% CAGR over 2026-2031.
This report is Segmented by Product (Single-Door, Double-Door, and More), Structure (Built-In and Freestanding), Capacity (Less Than 15 Cu. Feet and More Than 15 Cu. Feet), End User (Residential and Commercial), Distribution Channel (B2C/Retail and B2B), and Geography (North India, South India, West India, and East India). The Market Forecasts are Provided in Terms of Value (USD).
India Refrigerator Market Trends and Insights
Rising Disposable Incomes and Enhanced Electrification in Electrification in Tier -⅔ Towns
The India refrigerator market is experiencing strong growth, driven in part by rising disposable incomes and increasing electrification in tier-2 and tier-3 towns. As more households gain access to reliable electricity, demand for modern and energy-efficient refrigerators has expanded beyond traditional urban centers. Consumers in smaller cities are increasingly able to afford mid- to premium-range models, including double-door and multi-door refrigerators. This shift is also fueling the adoption of smart, inverter-based technologies, which offer improved energy efficiency and performance. Retailers and manufacturers are responding by expanding their distribution networks and e-commerce presence in these emerging markets. Overall, tier-2 and tier-3 towns are becoming key growth engines, contributing significantly to the country's overall refrigerator market expansion.
Support From PLI Schemes and 'Make in India' for Compressor Manufacturing
The Indian government's PLI scheme and Make in India initiatives are significantly boosting domestic manufacturing of refrigerator components, particularly compressors. Domestic players increased localization in refrigerators, supported by facility upgrades and new lines, as seen in Haier's Greater Noida expansion and planned capacity investments that deepen component in-sourcing across printed circuit boards and injection molded parts. Similarly, Samsung has announced an investment of around USD 200 million to establish a refrigerator compressor manufacturing plant in Sriperumbudur, Tamil Nadu, and has signed an MoU with the state government to expand the local component ecosystem. The new 22-acre facility will produce compressors for Samsung's India-manufactured refrigerators and for export, strengthening domestic production capacity. These investments not only reduce dependency on imports but also create a robust local component ecosystem, enhancing supply chain resilience and lowering production costs. Smaller manufacturers are also participating, leveraging government incentives to invest in automation, energy-efficient production, and skilled workforce development, which improves quality standards. Collectively, these initiatives are expected to accelerate capacity expansion, promote innovation, and drive competitiveness, supporting the rapid growth of the India refrigerator market across tier-1, tier-2, and tier-3 cities.
Power-Voltage Instability Continues to Affect Semi-Urban Grids
Voltage fluctuations are a persistent challenge in semi-urban and smaller towns across North and East India, especially during peak summer periods. These fluctuations often necessitate the use of stabilizers, which increases the effective purchase cost and limits the availability of stabilizer-free budget models. Load spikes during heat waves can damage compressor components in basic refrigerators, leading to higher warranty claims and affecting brand trust in markets where word-of-mouth strongly influences purchase decisions. While mid-range and premium models increasingly incorporate inverter technology and stabilizer-free operation, these features remain scarce in the affordable segment, slowing adoption among rural and semi-urban households. In addition, sparse after-sales service networks prolong repair times and increase logistical costs, further discouraging consumers in off-grid or underserved regions. Efforts to introduce solar- and battery-compatible refrigerators are underway, but high prices continue to restrict penetration in lower-income segments.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Inverter Technology and AI-Enabled Compressors
- Increased Demand for Premium Multi-Door and Designer Appliances
- Rural Regions Experience Significant After-Sales Service Deficiencies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Double-door refrigerators captured a 39.46% market share in the India refrigerator market in 2025, and side-by-side models are projected to grow the fastest at 11.46% through 2031, as premium adoption accelerates. French-door refrigerators are gaining popularity among families seeking spacious, fresh compartments and convenient lower-positioned freezers. Brands are focusing on features like convertible freezer logic, quick-cool modes, and noise reduction to enhance daily usability and support pre-chill routines for planned grocery purchases. Price tiers in the side-by-side segment allow brands to target both value-conscious buyers and high-end consumers with advanced connectivity and smart display options. Meanwhile, entry-level single-door direct-cool refrigerators remain relevant in smaller towns, although first-time buyers increasingly opt for frost-free double-door units with higher capacities. This shift is further supported by flexible financing options that make larger refrigerators more accessible to emerging urban households.
Refrigerator portfolios in India are being refreshed with emphasis on energy efficiency, smart diagnostics, and faster cooling cycles to meet evolving consumer expectations. French-door designs combine functional capacity with premium aesthetics, offering matte finishes, glass doors, and pantry-style compartments for fresh foods. Side-by-side models continue to appeal to large families and frequent entertainers, particularly in cities with higher disposable incomes and electricity tariffs that favor efficient inverter systems. Designer finishes allow kitchens to be upgraded without structural changes, lowering the barrier for retrofitting high-end models. Premium price bands extend to advanced connected features, while mid-tier refrigerators with inverter compressors remain the most widely adopted. Overall, the market is witnessing a gradual shift from basic entry-level models to feature-rich refrigerators that balance capacity, convenience, and lifestyle preferences.
Freestanding refrigerators held 81.58% of the 2025 market size, while built-in lines are on a 10.84% growth path through 2031, as modular cabinetry spreads beyond large metros within the India refrigerator market. Adoption is strongest among households that prioritize seamless visual continuity and can accommodate installation requirements such as alignment, ventilation, and panel integration. Brands are introducing panel-ready freestanding units that mimic built-in aesthetics, appealing to renters and mobile professionals who cannot modify their kitchen layouts. The growing use of stainless steel, glass, and matte finishes reflects the trend of appliances serving as design elements that complement overall interior schemes. Despite this, higher installation complexity and price premiums limit mass adoption of true built-ins in many smaller cities, keeping freestanding refrigerators in the lead. As modular kitchen concepts spread, consumer interest in built-in-compatible formats is gradually increasing, especially among premium buyers.
Developers, including those offering modular kitchens as standard amenities, are accelerating the purchase cycle for built-in and panel-ready models. Retailers and brand studios now emphasize color panels and design-matched finishes, improving product discovery and reducing consumer uncertainty when planning full kitchen upgrades. Service partners are better equipped for professional installation and precise panel alignment, which minimizes post-installation issues and improves overall satisfaction. Higher localization of components has reduced production costs and strengthened supply stability for premium lines. At the same time, portability, rental patterns, and cost considerations continue to favor freestanding units in most regions. Overall, while built-in refrigerators are gaining a foothold in urban and high-income markets, freestanding formats are expected to remain dominant across India during the forecast period.
Complete Report Scope:
- By Product
- Single-Door Refrigerator
- Double-Door Refrigerator
- Top Freezer
- Bottom Freezer
- Side-By-Side Door Refrigerator
- French-Door Refrigerator
- Other Refrigerators
- By Structure
- Built-In
- Freestanding
- By Capacity
- Less Than 15 cu. Feet
- More Than 15 cu. Feet
- By End user
- Residential
- Commercial
- By Distribution Channel
- B2C/Retail
- Multi-brand Stores
- Exclusive Brand Outlets
- Online
- Other Distribution Channels
- B2B/Directly from the Manufacturers
- B2C/Retail
- By Geography
- North India
- South India
- West India
- East India
List of Companies Covered in this Report:
- Samsung Electronics
- LG Electronics
- Whirlpool Corporation
- Godrej Appliances
- Haier India
- Panasonic Corporation
- Voltas Beko
- Hitachi Global Life Solutions
- Videocon Industries
- BSH Hausgerate GmbH
- Blue Star
- IFB Appliances
- Hisense
- Kelvinator India
- Onida (Mirc Electronics)
- Lloyd (Havells)
- Carrier-Midea
- Croma (Infiniti Retail)
- MarQ (Flipkart Private Label)
- Voltas Beko Home Appliances Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Disposable Incomes and Enhanced Electrification in Electrification in Tier -2/3 Towns
- 4.2.2 Support From PLI Schemes and 'Make in India' for Compressor Manufacturing
- 4.2.3 Adoption of Inverter Technology and AI-Enabled Compressors
- 4.2.4 Increased Demand for Premium Multi-Door and Designer Appliances
- 4.2.5 Focus on Energy-Efficient and BEE-Certified Products
- 4.2.6 Expansion of Organized Retail and E-Commerce Networks
- 4.3 Market Restraints
- 4.3.1 Power-Voltage Instability Continues to Affect Semi-Urban Grids
- 4.3.2 Rural Regions Experience Significant After-Sales Service Deficiencies
- 4.3.3 Smart Metering Infrastructure Adoption Remains Minimal
- 4.3.4 Seasonal Agricultural Loads Drive High Dependency in Certain Areas
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Suppliers
- 4.5.3 Bargaining Power Of Buyers
- 4.5.4 Threat Of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Insights Into The Latest Trends And Innovations In The Market
- 4.7 Insights On Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, Etc.)
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product
- 5.1.1 Single-Door Refrigerator
- 5.1.2 Double-Door Refrigerator
- 5.1.2.1 Top Freezer
- 5.1.2.2 Bottom Freezer
- 5.1.3 Side-By-Side Door Refrigerator
- 5.1.4 French-Door Refrigerator
- 5.1.5 Other Refrigerators
- 5.2 By Structure
- 5.2.1 Built-In
- 5.2.2 Freestanding
- 5.3 By Capacity
- 5.3.1 Less Than 15 cu. Feet
- 5.3.2 More Than 15 cu. Feet
- 5.4 By End user
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.5 By Distribution Channel
- 5.5.1 B2C/Retail
- 5.5.1.1 Multi-brand Stores
- 5.5.1.2 Exclusive Brand Outlets
- 5.5.1.3 Online
- 5.5.1.4 Other Distribution Channels
- 5.5.2 B2B/Directly from the Manufacturers
- 5.5.1 B2C/Retail
- 5.6 By Geography
- 5.6.1 North India
- 5.6.2 South India
- 5.6.3 West India
- 5.6.4 East India
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Samsung Electronics
- 6.4.2 LG Electronics
- 6.4.3 Whirlpool Corporation
- 6.4.4 Godrej Appliances
- 6.4.5 Haier India
- 6.4.6 Panasonic Corporation
- 6.4.7 Voltas Beko
- 6.4.8 Hitachi Global Life Solutions
- 6.4.9 Videocon Industries
- 6.4.10 BSH Hausgerate GmbH
- 6.4.11 Blue Star
- 6.4.12 IFB Appliances
- 6.4.13 Hisense
- 6.4.14 Kelvinator India
- 6.4.15 Onida (Mirc Electronics)
- 6.4.16 Lloyd (Havells)
- 6.4.17 Carrier-Midea
- 6.4.18 Croma (Infiniti Retail)
- 6.4.19 MarQ (Flipkart Private Label)
- 6.4.20 Voltas Beko Home Appliances Pvt. Ltd.
7 Market Opportunities & Future Outlook
- 7.1 Rural Electrification & Affordable Models