

|
시장보고서
상품코드
2124494
아프리카의 매니지드 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Africa Managed Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
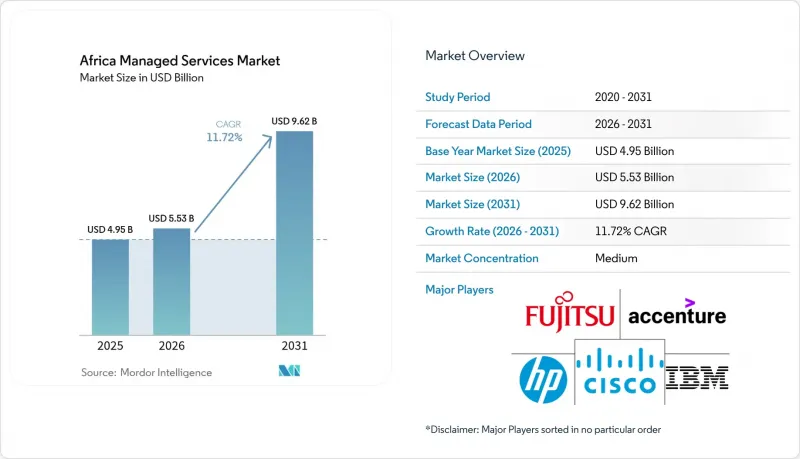
에 의하면, 아프리카의 매니지드 서비스 시장 규모는 2025년에 49억 5,000만 달러로 평가되었고, 2026년 55억 3,000만 달러에서 2031년까지 96억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 11.72%를 기록할 전망입니다.
본 보고서는 서비스 유형(매니지드 네트워크 서비스, 매니지드 보안 서비스,매니지드 모빌리티 서비스 등), 도입 모델(프라이빗 클라우드, 퍼블릭 클라우드, 하이브리드 클라우드), 조직 규모(대기업, 중소기업), 최종 사용자 산업(IT 및 통신, 은행, 금융서비스 및 보험(BFSI), 헬스케어 등), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아프리카의 매니지드 서비스 시장 동향 및 인사이트
중소기업 주도의 매니지드 클라우드 도입 급증
통화 약세로 인해 On-Premise형 하드웨어 도입이 어려워지는 가운데, 아프리카의 매니지드 서비스 시장에서 중소기업이 점점 더 중요한 역할을 담당하고 있습니다. 나이지리아의 중소기업들은 현재 환율 변동 위험을 회피할 수 있는 나이라(Naira) 표시 클라우드 번들을 선택하고 있으며, 이를 통해 총 소유 비용을 최대 40%까지 절감하고 있습니다. 가나에서도 유사한 변화가 관찰되는데, 세디(Cedi) 강세로 인해 기업들은 절감된 비용을 구독형 분석 플랫폼에 투자할 수 있게 되었습니다. Nebula나 Nobus와 같은 제공업체들은 볼륨 할인을 활용하여 수천 개에 달하는 소규모 고객에게 수익성 높은 서비스를 제공하고 있으며, 아프리카의 매니지드 서비스 시장 전체에 걸쳐 예측 가능한 지속적인 수익을 창출하고 있습니다. 확장 가능한 멀티테넌트 아키텍처 덕분에, 이러한 MSP들은 평균 계약 금액이 감소하더라도 이익률을 유지할 수 있습니다. 향후 2년 동안 온보딩 및 지원 기능을 자동화할 수 있는 제공업체에게 중소기업 수요는 가장 시급한 성장 동력으로 남아 있을 것입니다.
국내 데이터 주권 정책이 현지 MSP 수요를 견인
이집트, 나이지리아, 남아프리카공화국, 케냐의 국내 데이터 거주지 관련 법률로 인해 조달 우선순위가 재검토되고 있습니다. 이집트의 120페타바이트 규모 ‘정부 데이터·클라우드 컴퓨팅 센터’는 현지 워크로드 호스팅 의무의 기반이 되고 있으며, 아프리카의 관리형 서비스 시장을 강화하는 하이퍼스케일러와의 파트너십을 유도하고 있습니다. 마찬가지로, 나이지리아의 금융 기관들도 2024년 데이터 보호 규정을 준수하기 위해 워크로드를 현지 사업자로 이전하고 있으며, 이로 인해 현지 MSP에 전략적 우위가 부여되고 있습니다. Liquid Intelligent Technologies는 규제 대상 고객을 위해 규정 준수가 완료된 클라우드, 연결 및 보안 서비스를 패키지화한 결과, 10.3%의 매출 성장을 기록했습니다. 점점 더 많은 정부가 현지화를 공식적으로 도입함에 따라, 국내 처리 능력은 입찰의 필수 조건이 되어 벤더의 최종 후보 목록을 재편하는 동시에 중기적인 시장 확대를 촉진하고 있습니다.
만성적인 전력 공급 불안정이 OPEX를 상승시키고 있다.
잦은 정전으로 인해 나이지리아의 데이터센터에서는 하루 8-12시간 동안 디젤 발전기를 가동해야 하며, 그 결과 전력 요금은 송전망에 의존하는 동종 업계 경쟁사보다 60-80% 더 높아져 아프리카의 전체 매니지드 서비스 시장에서 이익률이 압박받고 있습니다. 남아프리카공화국에서는 계획 정전이 여전히 시행되고 있어 이중 전원 공급 설계를 도입할 수밖에 없으며, 이는 설비 투자 증가로 이어지고 있습니다. 제공업체들은 배터리 저장 및 마이크로그리드 솔루션을 도입하고 있지만, 높은 자본 집약도로 인해 중소기업 시장 진입이 저해되고 있습니다. 또한, 통신 사업자가 이중화 투자를 상각하기 위해 접속 요금이 급등하면서 고객들도 숨겨진 비용을 부담하고 있습니다. 재생에너지 도입이 개선을 가져올 것으로 예상되지만, 2027년까지는 불안정한 전력 공급이 여전히 운영 비용 측면에서 가장 큰 걸림돌이 될 것입니다.
부문별 분석
2025년에도 매니지드 데이터센터 및 호스팅 서비스가 매출의 37.02%라는 최대 점유율을 유지하며, 인프라의 기초적인 역할이 부각되고 있습니다. 한편, 매니지드 보안 솔루션은 연평균 성장률(CAGR) 12.28%로 성장하고 있으며, 아프리카의 매니지드 서비스 시장에서 그 중요성이 커지고 있습니다. 은행 및 통신 사업자에 대한 공격 빈도가 증가함에 따라 지속적인 모니터링, 사고 대응 및 제로 트러스트 아키텍처에 대한 수요가 증가하고 있습니다. 아프리카의 매니지드 서비스 업계는 만성적인 사이버 보안 인력 부족의 혜택을 받고 있으며, 이로 인해 기업들은 고급 보안 스택을 외부에 위탁하고 있습니다.
랜섬웨어 피해 증가는 규제 당국의 감시를 강화시키고, 규정 준수를 충족하는 관리형 감지 및 대응(MDR)에 대한 지출을 촉진하고 있습니다. 동시에, 멀티테넌트형 SOC 플랫폼을 통해 제공업체는 수십 개 고객사에 도구 비용을 분산시킬 수 있어 이익률 향상으로 이어지고 있습니다. 아프리카 기업 이사회가 정보 유출에 대해 금전적 제재를 부과하게 됨에 따라, 보안 정액제 계약 기간이 연간 갱신에서 수년 이상의 연장으로 장기화되고 있으며, 이는 아프리카의 관리형 서비스 시장에 안정적인 현금 흐름을 가져다주고 있습니다.
퍼블릭 클라우드는 2025년 매출의 76.65%를 차지하며 연평균 성장률(CAGR) 12.75%로 확대될 것으로 예상되지만, 데이터 주권에 관한 규제가 하이브리드형 프레임워크로의 전환을 촉진하고 있습니다. 나이지리아 기업들은 현재 탄력성을 저해하지 않으면서 데이터 상주 요건을 준수하기 위해 하이퍼스케일 컴퓨팅과 로컬 노드를 결합하고 있습니다. 서비스 제공업체들은 엣지 디바이스와 지역 가용성 영역을 통합하여 소비자용 용도에서 50밀리초 미만의 지연 시간을 유지하고 있으며, 이는 아프리카 관리형 서비스 시장의 민첩성을 보여줍니다.
규제가 엄격한 은행 및 정부 워크로드의 경우, 직접적인 관리가 여전히 최우선으로 간주되므로 프라이빗 클라우드가 계속해서 활용되고 있습니다. 그 결과, 마이크로소프트와 VMware의 하이브리드 오케스트레이션 도구 채택이 확대되고 있으며, 이는 도입 결정이 ‘퍼블릭인가 프라이빗인가’라는 이분법적 선택이 아니라 워크로드별로 최적화되는 방향으로 변화하고 있음을 보여줍니다. 향후 절대적인 규모는 확대되는 한편, 하이브리드 모델로 인해 퍼블릭 클라우드의 점유율은 축소될 전망이며, 아프리카의 매니지드 서비스 시장에서 아키텍처 설계 원칙이 재구축될 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the Africa managed services market size was valued at USD 4.95 billion in 2025 and estimated to grow from USD 5.53 billion in 2026 to reach USD 9.62 billion by 2031, at a CAGR of 11.72% during the forecast period (2026-2031).
This report is Segmented by Service Type (Managed Network Services, Managed Security Services, Managed Mobility Services, and More), Deployment Model (Private Cloud, Public Cloud, Hybrid Cloud), Organization Size (Large Enterprises, Smes), End-User Industry (IT and Telecom, BFSI, Healthcare, and More), and by Country. The Market Forecasts are Provided in Terms of Value (USD).
Africa Managed Services Market Trends and Insights
SME-led Surge in Managed Cloud Adoption
Small and medium enterprises increasingly anchor the Africa managed services market as currency depreciation makes on-premises hardware unaffordable. Nigerian SMEs now choose naira-denominated cloud bundles that avoid foreign-exchange shocks, lowering total cost of ownership by up to 40%. Similar shifts appear in Ghana where a stronger cedi lets firms channel savings into subscription-based analytics platforms. Providers such as Nebula and Nobus use volume pricing to profitably serve thousands of small customers, fuelling predictable recurring revenue across the Africa managed services market. Scalable multi-tenant architectures let these MSPs maintain margins even as average contract value falls. Over the next two years, SME demand remains the most immediate growth catalyst for providers that can automate onboarding and support functions.
National Data-sovereignty Policies Driving Local MSP Demand
Domestic data-residency laws in Egypt, Nigeria, South Africa and Kenya have re-ordered procurement priorities. Egypt's 120-petabyte Government Data and Cloud Computing Center anchors local workload hosting mandates and draws hyperscaler partnerships that reinforce the Africa managed services market.Financial institutions in Nigeria similarly divert workloads to local operators to comply with 2024 data-protection rules, granting indigenous MSPs strategic advantage. Liquid Intelligent Technologies posted 10.3% revenue growth after packaging compliance-ready cloud, connectivity and security services for regulated clients. As more governments formalise localisation, in-country capacity becomes a non-negotiable tender criterion, reshaping vendor shortlists and underwriting mid-term market expansion.
Chronic Power-supply Instability Increasing OPEX
Frequent outages mean Nigerian data centres operate diesel generators 8-12 hours daily, driving energy bills 60-80% higher than grid-reliant peers and compressing margins across the Africa managed services market. South Africa's scheduled load-shedding still forces dual-feed designs that raise capital outlays. Providers deploy battery storage and micro-grid solutions yet capital intensity limits entry for smaller firms. Clients also bear hidden costs through higher connectivity pricing as operators amortise redundancy investments. Although renewable deployments promise relief, unreliable power remains the single largest operational expense headwind through 2027.
Other drivers and restraints analyzed in the detailed report include:
- Rise of Pan-African Fibre Networks Lowering Latency
- Mining and Resource Sector's OT-IT Convergence Needs
- Depreciating Local Currencies Squeezing ICT Budgets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Managed data-centre and hosting services retained the largest 37.02% revenue slice in 2025, underscoring infrastructure's foundational role. Managed security solutions, however, are growing at 12.28% CAGR, elevating their importance within the Africa managed services market. Heightened attack frequency against banks and telcos drives continuous monitoring, incident response and zero-trust architecture demand. The Africa managed services industry also benefits from chronic cybersecurity talent shortages, prompting enterprises to outsource advanced protection stacks.
Increasing ransomware claims spur regulatory scrutiny, bolstering spend on compliance-aligned managed detection and response. At the same time, multi-tenant SOC platforms allow providers to amortise tooling across dozens of clients, lifting margins. As African boards attach financial penalties to breaches, security retainer contracts lengthen from annual renewals to multi-year-plus extensions, embedding steady cash flow into the Africa managed services market.
Public cloud captured 76.65% of 2025 revenues and is projected to climb with a 12.75% CAGR, yet data-sovereignty rules catalyse a pivot toward hybrid frameworks. Nigerian firms now blend hyperscale compute with local nodes to comply with residency mandates without sacrificing elasticity. Providers integrate edge devices and regional availability zones to maintain sub-50 ms latency for consumer applications, demonstrating the Africa managed services market's agility.
Private cloud persists in heavily regulated banking and government workloads where direct control remains paramount. Hybrid orchestration tools from Microsoft and VMware thus experience rising adoption, indicating that deployment decisions are becoming workload-specific rather than binary. Over time, hybrid models are likely to narrow the public-cloud share even as absolute volumes expand, reshaping architecture design principles within the Africa managed services market.
Complete Report Scope:
- By Service Type
- Managed Network Services
- Managed Security Services
- Managed Mobility Services
- Managed Cloud Services
- Managed Data-centre and Hosting Services
- Other Services
- By Deployment Model
- Private Cloud
- Public Cloud
- Hybrid Cloud
- By Organization Size
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
- By End-user Industry
- IT and Telecom
- BFSI
- Retail and E-commerce
- Healthcare
- Government and Public Sector
- Manufacturing
- Other Industries
- By Country
- South Africa
- Kenya
- Nigeria
- Egypt
- Rest of Africa
List of Companies Covered in this Report:
- Accenture PLC
- BCX (Telkom SA SOC)
- Castlerock Managed IT Services
- Cisco Systems Inc.
- CMC Networks
- Dimension Data (NTT Ltd.)
- Ericsson AB
- Fujitsu Ltd.
- Hewlett Packard Enterprise (HPE)
- Huawei Technologies Co.
- IBM Corporation
- Internet Solutions (IS)
- LanDynamix
- Liquid Intelligent Technologies
- MTN Business
- NEC Corporation
- Orange Business Services
- SEACOM Ltd.
- T-Systems South Africa
- Vodacom Business
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Favorable trends in big data and analytics and growing ICT spend
- 4.2.2 SME-led surge in managed cloud adoption
- 4.2.3 Rise of pan-African fibre networks lowering latency
- 4.2.4 National data-sovereignty policies driving local MSP demand
- 4.2.5 Mining and resource sector's OT-IT convergence needs
- 4.2.6 Greenfield smart-city projects (e.g., Konza, Eko Atlantic) requiring outsourced IT
- 4.3 Market Restraints
- 4.3.1 Chronic power-supply instability increasing OPEX
- 4.3.2 Data-privacy and cybersecurity skill gaps
- 4.3.3 Slow cross-border bandwidth upgrades in Central Africa
- 4.3.4 Depreciating local currencies squeezing ICT budgets
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (AI-ops, SASE, Edge)
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Managed Network Services
- 5.1.2 Managed Security Services
- 5.1.3 Managed Mobility Services
- 5.1.4 Managed Cloud Services
- 5.1.5 Managed Data-centre and Hosting Services
- 5.1.6 Other Services
- 5.2 By Deployment Model
- 5.2.1 Private Cloud
- 5.2.2 Public Cloud
- 5.2.3 Hybrid Cloud
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-sized Enterprises (SMEs)
- 5.4 By End-user Industry
- 5.4.1 IT and Telecom
- 5.4.2 BFSI
- 5.4.3 Retail and E-commerce
- 5.4.4 Healthcare
- 5.4.5 Government and Public Sector
- 5.4.6 Manufacturing
- 5.4.7 Other Industries
- 5.5 By Country
- 5.5.1 South Africa
- 5.5.2 Kenya
- 5.5.3 Nigeria
- 5.5.4 Egypt
- 5.5.5 Rest of Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, Partnerships)
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Accenture PLC
- 6.4.2 BCX (Telkom SA SOC)
- 6.4.3 Castlerock Managed IT Services
- 6.4.4 Cisco Systems Inc.
- 6.4.5 CMC Networks
- 6.4.6 Dimension Data (NTT Ltd.)
- 6.4.7 Ericsson AB
- 6.4.8 Fujitsu Ltd.
- 6.4.9 Hewlett Packard Enterprise (HPE)
- 6.4.10 Huawei Technologies Co.
- 6.4.11 IBM Corporation
- 6.4.12 Internet Solutions (IS)
- 6.4.13 LanDynamix
- 6.4.14 Liquid Intelligent Technologies
- 6.4.15 MTN Business
- 6.4.16 NEC Corporation
- 6.4.17 Orange Business Services
- 6.4.18 SEACOM Ltd.
- 6.4.19 T-Systems South Africa
- 6.4.20 Vodacom Business
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


