

|
시장보고서
상품코드
2124876
전문 오디오 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Professional Audio - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
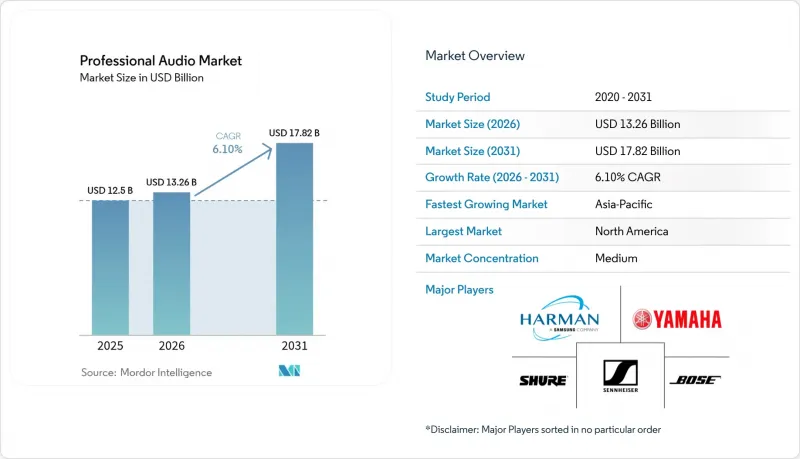
에 의하면, 전문 오디오 시장 규모는 2025년에 125억 달러로 평가되었습니다. 2026년 132억 6,000만 달러에서 2031년까지 178억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.1%를 나타낼 전망입니다.
본 보고서는 제품별(스피커, 파워 앰프, 믹싱 콘솔, 마이크, 헤드폰, 기타),연결 방식별(유선, 무선), 최종 사용자별(기업, 행사장·이벤트, 소매 및 호스피탈리티, 미디어 및 엔터테인먼트, 기타), 용도별(라이브 음향 증폭, 녹음 스튜디오, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 전문 오디오 시장 동향 및 인사이트
라이브 이벤트 및 체험형 마케팅의 급속한 확대
2024년, 주요 콘서트의 티켓 판매량은 전년 대비 26% 증가했으며, 이에 따라 렌탈 업체와 공연장 운영사는 임팩트를 유지하면서도 더욱 엄격해진 소음 규제를 충족하는 카디오이드형 서브 어레이 시스템으로 노후화된 어레이를 교체하고 있습니다. 페스티벌 운영사는 2025년 ‘울트라 뮤직 페스티벌’에서 볼 수 있었던 것처럼, 체험형 마케팅과 스폰서 수익을 연결하는 프리미엄 사운드 존을 통해 수익 창출을 꾀하고 있습니다. 하이브리드 형태의 기업 행사에서는 행사장 관객과 가상 시청자 사이를 저지연으로 연결하는 브리징 기능이 요구되고 있으며, 이에 따라 확장성이 높은 디지털 콘솔의 판매가 촉진되고 있습니다. 스피어 엔터테인먼트의 16만 7,000개 스피커 설치 사례는 몰입형 아키텍처가 브랜드 참여도를 어떻게 높이는지를 보여줍니다. 따라서 프로 오디오 시장에서는 유연한 스피커 구성과 신속한 쇼 전환을 효율화하는 고밀도 무선 채널에 대한 수요가 증가하고 있습니다.
크리에이터 경제에서 스튜디오급 장비에 대한 수요 급증
중국에서는 2024년에 7억 4,700만 명의 온라인 오디오 사용자가 기록되어 688억 6,000만 달러 규모 시장을 형성했습니다. 이는 개인 컨텐츠 크리에이터가 전문가용 장비 구매 결정에 미치는 영향이 얼마나 큰지를 여실히 보여줍니다. 같은 해, 전 세계 팟캐스트 수익은 300억 달러를 돌파했으며, 마이크 제조업체들은 편의성과 확장성을 겸비한 USB-XLR 하이브리드 제품 출시를 단행했습니다. 브랜드의 시각적 미학도 중요합니다. 대형 방송용 스타일의 마이크는 카메라 화면에 비칠 때의 신뢰성을 높여주며, 실시간 음성 처리 기능을 통합한 Shure의 MV7i와 같은 제품의 보급을 뒷받침하고 있습니다. 중견 제조업체들은 하드웨어에 소프트웨어 플러그인을 번들로 제공함으로써 이러한 기회를 활용하고, 첫 구매 사용자를 구독 고객으로 전환하고 있습니다. 이러한 요인으로 인해 최종 사용자층이 기존 스튜디오의 범위를 넘어 확대되고, 프로 오디오 시장의 잠재 규모가 커지고 있습니다.
반도체 공급망의 지속적인 변동
DSP 코어와 RF 트랜시버의 리드타임이 60주를 초과함에 따라, 설계 팀은 대체 부품을 인증하거나 고급 기능을 제거할 수밖에 없는 상황에 처해 있습니다. 관세 인상으로 인해 입고 비용이 상승하는 가운데, 2024년 미국의 반도체 수입액은 1,390억 달러에 달했습니다. 중소 오디오 브랜드들은 대형 기술 기업들과 웨이퍼 할당을 놓고 경쟁할 수밖에 없는 상황이며, 많은 경우 할증료를 지불하거나 생산 로트를 축소하고 있습니다. 부품의 노후화가 가속화되고 있으며, 일부 공급업체는 칩 수를 줄일 수 있는 아날로그 제품 라인을 우선시하고 디지털 제품의 SKU를 단종하는 움직임도 보이고 있습니다. 그 결과, 프로 오디오 시장에서는 팹의 생산 능력이 수요와 균형을 맞출 때까지 이익률 압박이 지속될 전망입니다.
부문별 분석
2025년, 프로 오디오 시장 규모의 38.02%를 스피커가 차지하며, 투어, 고정 설치, 하이브리드 공연장 등 모든 분야에서 그 중심적인 위치를 확인했습니다. 팬데믹으로 인한 가동 중단 기간을 거치며 교체 주기가 가속화되었고, 많은 아레나에서는 지자체의 소음 규제를 준수하면서도 저주파 방향성을 향상시키는 카디오이드형 서브 어레이가 채택되고 있습니다. 한편, 무선 마이크는 규제에 따른 주파수 대역 재할당으로 인해 사용자가 아날로그 UHF 기기 사용을 중단할 수밖에 없게 된 것을 배경으로 연평균 성장률(CAGR) 7.45%로 확대되고 있습니다. 각 제조업체는 좁아지는 주파수 대역에 적합하고, 혼신이 심한 RF 환경에서도 성능을 유지할 수 있는 암호화된 디지털 플랫폼으로 이에 대응하고 있습니다.
스피커 부문에서는 FIR(유한 임펄스 응답) 기반의 빔 스티어링을 통해 시스템 성능을 향상시키는 증폭 장치, 리깅, 제어 소프트웨어에 대한 고부가가치 수요가 시장을 견인하고 있습니다. 각 벤더는 예측 모듈을 활성화하는 소프트웨어 구독 서비스를 전개하여, 하드웨어의 일시적인 판매를 지속적인 수익으로 전환하고 있습니다. 각 마이크 제조업체들은 젠하이저의 ‘Spectera’와 같은 WMAS(무선 마이크 액세스 시스템) 기반의 생태계를 모색하고 있으며, 이는 단일 6MHz 블록 내에서 64개 채널을 제공함으로써 첨단 변조 기술이 주파수 대역 부족 문제를 어떻게 해결할 수 있는지 보여주고 있습니다. Dante 브레이크아웃 박스나 PoE 지원 스테이지 박스와 같은 액세서리는 통합상의 격차를 메워주며, 프로 오디오 시장에서 벤더의 점유율을 더욱 확대되고 있습니다.
유선 솔루션은 정부 의회나 방송 스튜디오 등 RF 위험에 대한 내성이 필요한 미션 크리티컬한 용도 덕분에 2025년 프로 오디오 시장 규모에서 56.85%의 점유율을 유지했습니다. Cat6a 케이블과 이중화 링 토폴로지는 지연을 거의 제로로 억제하고 PoE++를 통한 전원 공급을 가능하게 합니다. 그러나 Wi-Fi 7이 6GHz 대역의 채널을 개방하고 결정론적 스케줄링을 개선함에 따라, 무선 기기는 2031년까지 연평균 성장률(CAGR) 7.22%를 나타낼 것으로 예측됩니다. 초기 Dante-over-Wi-Fi 프로토타입은 5밀리초 미만의 지연을 입증하며 이더넷과의 성능 격차를 좁히고 있습니다.
배터리 기술의 혁신으로 휴대용 PA 박스의 가동 시간이 중간 수준의 SPL에서 40시간으로 연장되어, 야외 이용 사례가 확대되고 있습니다. 클라우드 데이터베이스를 활용한 주파수 관리 및 조정 앱은 도입을 간소화하여, 자원봉사 운영자에게 필요한 전문 지식의 장벽을 낮추고 있습니다. 위조 RF 모듈이 상황을 복잡하게 만들고 있지만, 산업 단체의 계몽 활동을 통해 표준화된 스캔 프로토콜을 이용한 간섭 저감이 진행되고 있습니다. 통합 업체가 유선과 무선을 융합한 페일오버 아키텍처를 설계함으로써, 유선 및 무선 생태계가 공존하고, 프로 오디오 시장이 신뢰성과 유연성이라는 두 가지 기대를 동시에 충족할 수 있도록 보장하고 있습니다.
지역별 분석
2025년, 북미는 프로 오디오 시장의 33.12%를 차지했습니다. 이는 지속적인 기술 갱신이 필요한 경기장, 메가처치, 방송 시설이 전 세계에서 가장 고밀도로 집중되어 있다는 점에 기인합니다. FCC에 의한 주파수 대역 재할당으로 인해 무선 장비의 교체가 시급해진 반면, 접근성 관련 법률에 따라 행사장에서는 청각 보조 송신기의 도입이 진행되고 있습니다. 기업의 부동산 부서는 AES67 네트워크를 통해 행사장 내와 원격지의 음성을 통합하는 회의실 현대화를 우선순위로 두고 있습니다. 캘리포니아주와 일리노이주의 지역 제조 클러스터는 전 세계적인 공급 차질 시 리드 타임을 단축함으로써 지역의 회복탄력성을 강화하고 있습니다.
아시아태평양은 가장 빠른 성장세를 기록하며 2031년까지 연평균 성장률(CAGR) 7.22%로 확대되고 있습니다. 이는 중국과 인도의 국립 경기장 건설 프로젝트에서 설계 단계부터 Dante 네이티브 PA 시스템이 통합되고 있기 때문입니다. 중국의 ‘청각 경제’는 소비자용 시설에 대해 경쟁적 차별화 요소로서 프리미엄 오디오 도입을 의무화함으로써 조달 동향을 형성하고 있습니다. 인도의 통합업체들은 조립 현지화를 촉진하는 정부의 우대 조치의 혜택을 받아 수입 부품에 대한 관세가 인하되고 있습니다. 이 지역의 크리에이티브 계층이 급증하면서 합리적인 가격의 스튜디오용 인터페이스에 대한 수요가 증가했고, 긱 경제에 속한 뮤지션과 팟캐스터들 사이에서 프로 오디오 시장의 기반이 확대되고 있습니다. 환율 변동은 여전히 계획상의 위험 요소이지만, 제조업체들은 가능한 한 계약 통화를 달러(USD)로 설정하여 위험을 헤지하고 있습니다.
유럽에서는 문화 시설 및 기업 캠퍼스 전반에 걸쳐 안정적인 수요가 나타나고 있습니다. 역사적인 극장의 리모델링에서는 EU의 지속가능성 목표에 부합하기 위해 재활용 가능한 스피커 캐비닛과 저전력 앰프가 우선적으로 채택되고 있습니다. 브렉시트로 인해 이중 인증 비용은 증가하고 있지만, 한편으로는 유럽 대륙의 유통업체들이 공급의 연속성을 유지하기 위해 완충 재고를 확보하도록 권장받고 있습니다. Prolight+Sound와 같은 독일 전시회는 제품 인지도 제고에 기여하고 있는 반면, 영국의 방송 산업에서는 ST 2110 지원 콘솔의 도입이 가속화되고 있습니다. 이처럼 유럽의 프로 오디오 시장은 대규모 생산 능력 확대가 아닌, 규제 준수 및 친환경 설계를 통해 진화하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the professional audio market size was valued at USD 12.50 billion in 2025 and estimated to grow from USD 13.26 billion in 2026 to reach USD 17.82 billion by 2031, at a CAGR of 6.1% during the forecast period (2026-2031).
This report is Segmented by Product (Loudspeakers, Power Amplifiers, Mixing Consoles, Microphones, Headphones, and More), Connectivity (Wired, Wireless), End-User (Corporate, Venues and Events, Retail and Hospitality, Media and Entertainment, and More), Application (Live Sound Reinforcement, Recording Studios, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Professional Audio Market Trends and Insights
Rapid Expansion of Live-Events and Experiential Marketing
Ticket volumes at major concerts increased 26% year over year in 2024, spurring rental firms and venues to replace aging arrays with cardioid sub-array systems that meet stricter noise ordinances while preserving punch. Festival operators monetize premium sound zones that tie experiential marketing to sponsorship revenue, as seen at Ultra Music Festival 2025. Hybrid corporate shows need low-latency bridging between onsite and virtual audiences, driving sales of scalable digital consoles. Sphere Entertainment's 167,000-speaker install illustrates how immersive architecture elevates brand engagement. The professional audio market therefore sees elevated demand for flexible loudspeaker configurations and high-density wireless channels that streamline quick show turnovers.
Surging Creator-Economy Demand for Studio-Grade Gear
China logged 747 million online audio users in 2024, generating a sector worth USD 68.86 billion, underlining how individual content creators influence professional purchasing decisions. Global podcast revenue surpassed USD 30 billion the same year, pushing microphone makers to launch USB-XLR hybrids that combine convenience with expandability. Visual brand aesthetics matter; larger broadcast-style microphones improve on-camera credibility, boosting uptake of units such as Shure's MV7i that integrate real-time voice processing. Mid-tier manufacturers capitalize by bundling software plug-ins alongside hardware, converting first-time buyers into subscription clients. This driver enlarges the addressable professional audio market by expanding the end-user base beyond traditional studios.
Persistent Semiconductor Supply-Chain Volatility
Lead times for DSP cores and RF transceivers extend past 60 weeks, forcing design teams to qualify substitute parts or strip advanced features. U.S. semiconductor imports reached USD 139 billion in 2024 amid tariff hikes that raised landed costs. Smaller audio brands compete against large tech firms for wafer allocation, often paying premiums or shrinking production runs. Component obsolescence accelerates, leading some vendors to sunset digital SKUs in favor of analog lines requiring fewer chips. The professional audio market thus faces margin compression until fab capacity aligns with demand.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Networked-AV and AES67/Dante Interoperability
- Shift to Immersive and Spatial-Audio Formats
- High Total Cost of Ownership for Tour-Grade Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Loudspeakers contributed 38.02% of the professional audio market size in 2025, confirming their centrality across touring, fixed install, and hybrid venues. Replacement cycles accelerated after pandemic-era downtime, with many arenas adopting cardioid sub-arrays that improve low-frequency directionality while complying with municipal noise codes. Meanwhile, wireless microphones advance at an 7.45% CAGR on the back of regulatory spectrum reallocations that compel users to retire analog UHF units. Manufacturers answer with encrypted digital platforms that fit within shrinking frequency bands, safeguarding performance in congested RF environments.
The loudspeaker segment drives value-added demand for amplification, rigging, and control software that elevate system performance through FIR-based beam steering. Vendors unlock software subscriptions that activate prediction modules, converting one-time hardware sales into recurring revenue. Microphone makers explore WMAS-based ecosystems, such as Sennheiser's Spectera, which delivers 64 channels inside a single 6 MHz block and illustrates how advanced modulation counters spectrum scarcity. Accessories like Dante breakout boxes and PoE-powered stage boxes fill integration gaps, rounding out wallet share captured by vendors inside the professional audio market.
Wired solutions retained 56.85% share of the professional audio market size in 2025 thanks to mission-critical applications that resist RF risk, including government chambers and broadcast studios. Cat6a cable and redundant ring topologies guarantee near-zero latency and facilitate power distribution through PoE++. Yet wireless units are forecast to post a 7.22% CAGR to 2031 as Wi-Fi 7 unlocks 6 GHz channels and improves deterministic scheduling. Early Dante-over-Wi-Fi prototypes demonstrate sub-5 ms latency, narrowing the performance gap against Ethernet.
Battery innovation extends runtime to 40 hours at moderate SPL for portable PA boxes, widening addressable outdoor use cases. Managed-frequency coordination apps powered by cloud databases simplify deployment, lowering expertise barriers for volunteer operators. Despite counterfeit RF modules adding complexity, educational initiatives by industry bodies help mitigate interference through standardized scanning protocols. Wired and wireless ecosystems coexist as integrators design fail-over architectures that blend both, ensuring the professional audio market satisfies reliability and flexibility expectations simultaneously.
Complete Report Scope:
- By Product
- Loudspeakers
- Power Amplifiers
- Mixing Consoles
- Microphones
- Headphones
- Accessories and Others
- By Connectivity
- Wired
- Wireless
- By End-User
- Corporate
- Venues and Events
- Retail and Hospitality
- Media and Entertainment
- Education and Houses-of-Worship
- By Application
- Live Sound Reinforcement
- Recording Studios
- Broadcast and Streaming
- Installed Sound / Public-Address
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Chile
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Singapore
- Australia
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 33.12% of the professional audio market in 2025, backed by the world's densest concentration of arenas, megachurches, and broadcast facilities requiring rolling technology refreshes. FCC spectrum reallocation compels wireless replacements, while accessibility laws push venues to adopt assistive-listening transmitters. Corporate real-estate teams prioritize conference-room modernization that unifies in-room and remote voices via AES67 networks. Regional resilience is reinforced by local manufacturing clusters in California and Illinois that shorten lead times during global supply disruptions.
Asia-Pacific records the fastest pace, advancing at a 7.22% CAGR through 2031 as national stadium programs in China and India embed Dante-native public-address systems from blueprint stages. China's "ear economy" shapes procurement by requiring consumer-facing venues to adopt premium audio as a competitive differentiator. Indian integrators benefit from government incentives that localize assembly, lowering tariffs on imported components. The region's creative-class boom fuels demand for affordable studio interfaces, expanding the professional audio market base among gig-economy musicians and podcasters. Currency fluctuations remain a planning risk, yet manufacturers hedge by denominating contracts in USD where possible.
Europe demonstrates stable demand across cultural institutions and corporate campuses. Renovation of heritage theaters prioritizes recyclable loudspeaker cabinets and low-power amplifiers to align with EU sustainability targets. Brexit spurs dual-certification costs but also motivates continental distributors to hold buffer stock, maintaining supply continuity. German trade fairs like Prolight + Sound drive product visibility, while the United Kingdom broadcast sector accelerates adoption of ST 2110-compatible consoles. The professional audio market in Europe thus evolves through regulatory compliance and green design, rather than large-scale capacity increases.
- Shure Incorporated
- Sennheiser electronic GmbH & Co. KG
- Harman International Industries Inc. (JBL Professional)
- Yamaha Corporation
- Bose Corporation
- QSC LLC
- Audio-Technica Corporation
- LEWITT GmbH
- RCF Group S.p.A
- Music Tribe (Global Brands Ltd.)
- PreSonus Audio Electronics Inc.
- Mackie (LOUD Audio LLC)
- Allen and Heath Limited
- DiGiCo UK Ltd.
- Focusrite plc
- Avid Technology Inc.
- Powersoft S.p.A
- d&b audiotechnik GmbH
- L-Acoustics Group
- Meyer Sound Laboratories Inc.
- Electro-Voice (Bosch Security Systems Inc.)
- Crown International (Harman)
- TASCAM (TEAC Corporation)
- Rode Microphones (Free-fly Pty Ltd)
- Zoom Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid expansion of live-events and experiential marketing
- 4.2.2 Surging creator-economy demand for studio-grade gear
- 4.2.3 Growth of networked-AV and AES67/Dante interoperability
- 4.2.4 Shift to immersive and spatial-audio formats (Dolby Atmos, MPEG-H)
- 4.2.5 Corporate hybrid-work investments in high-fidelity audio
- 4.2.6 Government funding for smart-city public-address upgrades
- 4.3 Market Restraints
- 4.3.1 Persistent semiconductor supply-chain volatility
- 4.3.2 High total-cost-of-ownership for tour-grade systems
- 4.3.3 Proliferation of counterfeit/grey-market components
- 4.3.4 Rising e-waste regulations increasing compliance costs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Loudspeakers
- 5.1.2 Power Amplifiers
- 5.1.3 Mixing Consoles
- 5.1.4 Microphones
- 5.1.5 Headphones
- 5.1.6 Accessories and Others
- 5.2 By Connectivity
- 5.2.1 Wired
- 5.2.2 Wireless
- 5.3 By End-User
- 5.3.1 Corporate
- 5.3.2 Venues and Events
- 5.3.3 Retail and Hospitality
- 5.3.4 Media and Entertainment
- 5.3.5 Education and Houses-of-Worship
- 5.4 By Application
- 5.4.1 Live Sound Reinforcement
- 5.4.2 Recording Studios
- 5.4.3 Broadcast and Streaming
- 5.4.4 Installed Sound / Public-Address
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Chile
- 5.5.2.3 Argentina
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Singapore
- 5.5.4.5 Australia
- 5.5.4.6 Malaysia
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Shure Incorporated
- 6.4.2 Sennheiser electronic GmbH & Co. KG
- 6.4.3 Harman International Industries Inc. (JBL Professional)
- 6.4.4 Yamaha Corporation
- 6.4.5 Bose Corporation
- 6.4.6 QSC LLC
- 6.4.7 Audio-Technica Corporation
- 6.4.8 LEWITT GmbH
- 6.4.9 RCF Group S.p.A
- 6.4.10 Music Tribe (Global Brands Ltd.)
- 6.4.11 PreSonus Audio Electronics Inc.
- 6.4.12 Mackie (LOUD Audio LLC)
- 6.4.13 Allen and Heath Limited
- 6.4.14 DiGiCo UK Ltd.
- 6.4.15 Focusrite plc
- 6.4.16 Avid Technology Inc.
- 6.4.17 Powersoft S.p.A
- 6.4.18 d&b audiotechnik GmbH
- 6.4.19 L-Acoustics Group
- 6.4.20 Meyer Sound Laboratories Inc.
- 6.4.21 Electro-Voice (Bosch Security Systems Inc.)
- 6.4.22 Crown International (Harman)
- 6.4.23 TASCAM (TEAC Corporation)
- 6.4.24 Rode Microphones (Free-fly Pty Ltd)
- 6.4.25 Zoom Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


