

|
시장보고서
상품코드
2125256
아시아태평양의 전문용 AV 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asia-Pacific Professional Audio-Visual Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
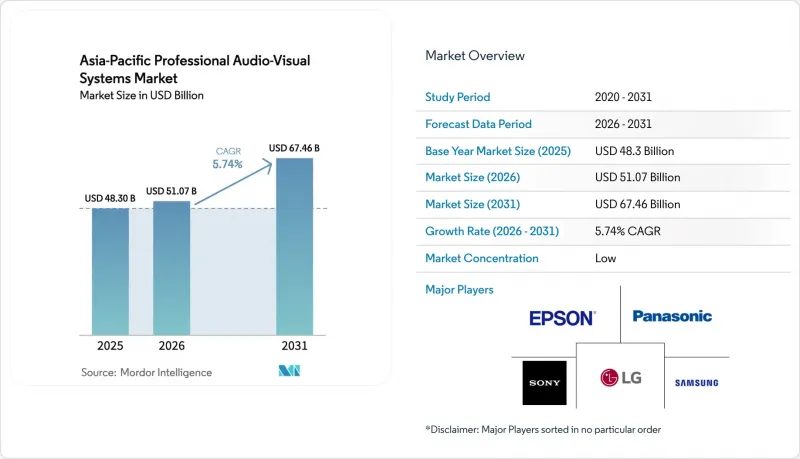
에 의하면, 아시아태평양의 전문용 AV 시스템 시장 규모는 2025년 483억 달러로 평가되었습니다. 2026년에는 510억 7,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.74%로 성장을 지속하여, 2031년에는 674억 6,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(촬영·제작 장비, 기타), 구성 요소별(오디오 장비, 디스플레이 및 프로젝션 시스템, 기타), 최종 사용자 산업별(기업, 행사장·이벤트, 소매, 교육, 기타), 지역별(중국, 일본, 인도, 한국, 동남아시아, 기타 아시아태평양)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아시아태평양의 전문용 AV 시스템 시장 동향 및 인사이트
하이브리드 업무 환경에서의 클라우드 네이티브 UC&C 스위트에 대한 수요
아시아태평양 프로페셔널 AV 시스템 시장의 기업들은 Microsoft Teams Rooms 및 유사한 플랫폼을 표준화하고 있으며, 이에 따라 통합 업체들은 카메라, 마이크, 인터랙티브 디스플레이, AI 기반 음향 처리를 융합한 턴키 패키지를 제공해야 하는 상황에 놓여 있습니다. 공간 오디오 기능과 자동 프레이밍을 통해 원격지에 있는 직원들도 회의에 쉽게 참여할 수 있게 됩니다. 이는 국경을 초월한 팀을 관리하는 중국 및 일본의 다국적 기업들에게 우선순위로 자리 잡고 있습니다. 또한, AV와 IT의 통합 네트워크는 매니지드 서비스의 효율성을 높여 시설 관리자의 현장 대응 비용을 절감하는 동시에, 전력 소비를 최적화한 기기의 일정 관리를 통해 기업이 사내 탄소 배출 감축 목표를 달성할 수 있도록 지원합니다.
체험형 소매업에서의 디지털 사이니지 네트워크 확대
인터랙티브 LED 파사드와 8K 비디오월이 플래그십 매장을 혁신하고 있으며, 지역 소매업체들은 대형 디스플레이를 활용하여 오프라인 매장 쇼핑과 소셜 커머스의 참여도를 연결하고 있습니다. 아시아태평양의 전문용 AV 시스템 시장은 픽셀 피치 가격 하락과 밝기를 저하시키지 않으면서도 지속가능성 관련 규제를 충족하는 고효율 마이크로 LED 모듈의 등장으로 혜택을 보고 있습니다. 팬데믹 이후 안전 관련 메시지 전달이 디스플레이 도입을 가속화했으며, 컨텐츠 관리 소프트웨어에는 현재 재실감지 센서가 통합되어 실시간 시각적 안내를 촉발하는 기능을 갖추고 있습니다. 이는 싱가포르와 서울의 소매업체들이 현지 위생 규정을 준수하기 위해 도입하고 있는 기능입니다.
복잡한 AV 프로젝트에 수반되는 높은 운영 비용 및 규정 준수 비용
통합 솔루션은 영상, 음성, 제어, 사이버 보안 대책이 하나로 통합되어 있어, 특히 주요 대도시권 이외의 지역에서는 설계 공수와 전문 기술자의 인건비가 증가하고 있습니다. 인재 양성 체계가 수요를 따라가지 못하고 있습니다. 아시아태평양에서 고급 SDVoE 인증을 취득한 엔지니어는 3,000명 미만이며, 기업들은 보증 기간 동안 계속 근무하지 않을 가능성이 있는 프리랜서에 의존할 수밖에 없는 상황입니다. ‘AV-as-a-Service’ 계약은 설비 투자(Capex)를 운영 비용(OpEx)으로 전환하지만, 가동률이나 데이터 보호 감사와 연계된 SLA 위반 벌금이 포함되어 있어 중소규모 통합 업체들은 재무 측면에서 신중한 태도를 취하고 있습니다.
부문별 분석
스트리밍 미디어, 스토리지, 전송은 아시아태평양의 전문용 AV 시스템 시장에서 35.15%의 점유율을 차지하며, 원격 협업 및 소비자용 직접 전송 엔터테인먼트의 기반으로서의 역할을 두드러지게 하고 있습니다. 공장 전체로 확산되는 5G 프라이빗 네트워크의 물결은 4K 컨텐츠를 1초 미만으로 캡처, 트랜스코딩 및 전송하는 클라우드 게이트웨이의 정착을 더욱 촉진하고 있으며, 현장 직원을 배치하지 않고도 원격으로 품질 보증 검토를 가능하게 하고 있습니다. ‘촬영·제작 장비’는 연평균 성장률(CAGR) 6.62%가 예상되며, 인플루언서 경제의 성장과 AI 자동 추적 기능이 탑재된 삼각대와 결합된 합리적인 가격의 미러리스 카메라의 보급으로 시장이 활기를 띠고 있습니다. 기존 비디오 프로젝터는 밝은 램프 없는 장비를 필요로 하며, 최소한의 유지보수만으로 연중무휴 24시간 가동 가능한 강의실이나 호텔 연회장에서 여전히 중요한 역할을 수행하고 있습니다.
2세대 엣지 인코더는 HEVC 스트림을 절반의 비트레이트로 압축하여 원격 교육 제공업체의 대역폭 비용을 절감합니다. 관리형 서비스 공급업체들은 이를 컨텐츠 전송 네트워크(CDN) 구독과 함께 판매하고 있으며, 아시아태평양의 전문용 AV 시스템 시장을 하드웨어 판매에서 지속적인 수익 모델로 전환시키고 있습니다. 실험적인 홀로그래픽 디스플레이가 수술 계획실에 등장하고 있지만, 대부분의 기업에서는 아직 주류로 도입되지 않았으며, 연구 개발 예산 범위 내에서 시범 운영을 진행하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Asia-Pacific professional audio-visual system market size is expected to grow from USD 48.3 billion in 2025 to USD 51.07 billion in 2026 and is forecast to reach USD 67.46 billion by 2031 at 5.74% CAGR over 2026-2031.
This report is Segmented by Type (Capture and Production Equipment, and More), Component (Audio Equipment, Display and Projection Systems, and More), End-User Vertical (Corporate, Venues and Events, Retail, Education, and More), and Geography (China, Japan, India, South Korea, South-East Asia, Rest of Asia-Pacific). The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Professional Audio-Visual Systems Market Trends and Insights
Hybrid-workplace demand for cloud-native UC suites
Enterprises across the Asia-Pacific professional audio-visual system market are standardizing on Microsoft Teams Rooms and similar platforms, prompting integrators to deliver turnkey packages that blend cameras, microphones, interactive displays, and AI-driven sound processing. Spatial audio functions and automated framing make meetings more inclusive for distributed employees, a priority for Chinese and Japanese multinationals managing cross-border teams. Converged AV-IT networks also streamline managed services, cutting truck-roll costs for facility managers and helping corporations meet internal carbon-reduction goals through power-optimized device scheduling.
Expansion of digital signage in experiential retail
Interactive LED facades and 8K videowalls are transforming flagship stores, with regional retailers using large-format displays to bridge physical shopping and social-commerce engagement. The Asia-Pacific professional audio-visual system market benefits from falling pixel-pitch pricing and higher-efficiency micro-LED modules that meet sustainability regulations without sacrificing brightness. Post-pandemic safety messaging hastened display roll-outs, and content management software now integrates occupancy sensors to trigger real-time visual prompts, a feature retailers in Singapore and Seoul deploy to comply with local health codes.
High operating and compliance costs of complex AV projects
Integrated solutions now blend video, audio, control, and cybersecurity safeguards, raising design hours and specialist wages, particularly outside primary metro areas. Training pipelines lag demand: fewer than 3,000 Asia-Pacific engineers hold advanced SDVoE certification, prompting firms to rely on freelancers who may not stay through warranty periods. AV-as-a-Service contracts transfer capex to opex but include SLA penalties tied to uptime and data-protection audits, making smaller integrators financially cautious.
Other drivers and restraints analyzed in the detailed report include:
- Government-led "smart classroom" capex
- Live-event rebound lifts rental and staging
- Carbon-border tariffs inflate export BOM costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Streaming Media, Storage, and Distribution holds a 35.15% share of the Asia-Pacific professional audio-visual system market, underlining its role as the backbone for distance collaboration and direct-to-consumer entertainment. The wave of 5G private networks across factories further entrenches cloud gateways that ingest, transcode, and forward 4K content in under a second, unlocking remote quality-assurance reviews without on-site staff. Capture and Production Equipment, projected to clock a 6.62% CAGR, thrives on influencer-economy growth and affordable mirrorless cameras paired with AI auto-tracking tripods. Legacy video projection remains relevant for lecture halls and hotel ballrooms craving bright, lamp-free units able to run 24/7 with minimal maintenance.
Second-generation edge encoders compress HEVC streams at half the bit-rate, shrinking bandwidth fees for distance-learning providers. Managed-service vendors bundle them with content-delivery-network subscriptions, shifting the Asia-Pacific professional audio-visual system market from hardware sales toward recurring revenue models. Experimental holographic displays surface in surgical-planning labs, yet most enterprises still pilot them under research and development budgets rather than mainstream roll-outs.
Complete Report Scope:
- By Type
- Capture and Production Equipment
- Video Projection
- Streaming Media, Storage and Distribution
- Services
- Other Types
- By Component
- Audio Equipment (mics, mixers, amps)
- Display and Projection Systems
- Control and Processing
- Storage and Distribution Hardware
- By End-user Vertical
- Corporate
- Venues and Events
- Retail
- Media and Entertainment
- Education
- Government
- Healthcare
- Other End-user Vertical
- By Country
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Sony Corporation
- Samsung Electronics
- Panasonic Corporation
- LG Electronics
- Epson
- Barco NV
- Alpine Electronics Inc.
- Kramer Electronics
- Crestron Electronics
- Bose Professional
- Shure Incorporated
- Extron Electronics
- Planar Systems Inc.
- Vega Global
- Elmo
- Guangzhou Baolun Electronic Co.
- Guangzhou DSPPA Audio Co.
- Sennheiser Electronic
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hybrid-Workplace Demand for Cloud-Native UC and C Suites
- 4.2.2 Expansion of Digital Signage Networks in Experiential Retail
- 4.2.3 Government-Led "Smart Classroom" Capex Across Emerging Asia
- 4.2.4 Live-Event Rebound Accelerating Rental and Staging Spend
- 4.2.5 5G-Enabled Remote Production and AVoIP Workflows
- 4.2.6 Carbon-Neutral Procurement Mandates for Energy-Efficient AV
- 4.3 Market Restraints
- 4.3.1 High Operating and Compliance Costs of Complex AV Projects
- 4.3.2 Persistent Chipset and Optical-Component Supply Bottlenecks
- 4.3.3 Shortage of Certified AV Technicians in Tier-2 Asian Cities
- 4.3.4 Carbon-Border Tariffs Inflating Export BOM Costs
- 4.4 Impact of Macroeconomic Factors
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers/Consumers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Capture and Production Equipment
- 5.1.2 Video Projection
- 5.1.3 Streaming Media, Storage and Distribution
- 5.1.4 Services
- 5.1.5 Other Types
- 5.2 By Component
- 5.2.1 Audio Equipment (mics, mixers, amps)
- 5.2.2 Display and Projection Systems
- 5.2.3 Control and Processing
- 5.2.4 Storage and Distribution Hardware
- 5.3 By End-user Vertical
- 5.3.1 Corporate
- 5.3.2 Venues and Events
- 5.3.3 Retail
- 5.3.4 Media and Entertainment
- 5.3.5 Education
- 5.3.6 Government
- 5.3.7 Healthcare
- 5.3.8 Other End-user Vertical
- 5.4 By Country
- 5.4.1 China
- 5.4.2 Japan
- 5.4.3 India
- 5.4.4 South Korea
- 5.4.5 South-East Asia
- 5.4.6 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sony Corporation
- 6.4.2 Samsung Electronics
- 6.4.3 Panasonic Corporation
- 6.4.4 LG Electronics
- 6.4.5 Epson
- 6.4.6 Barco NV
- 6.4.7 Alpine Electronics Inc.
- 6.4.8 Kramer Electronics
- 6.4.9 Crestron Electronics
- 6.4.10 Bose Professional
- 6.4.11 Shure Incorporated
- 6.4.12 Extron Electronics
- 6.4.13 Planar Systems Inc.
- 6.4.14 Vega Global
- 6.4.15 Elmo
- 6.4.16 Guangzhou Baolun Electronic Co.
- 6.4.17 Guangzhou DSPPA Audio Co.
- 6.4.18 Sennheiser Electronic
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


