|
시장보고서
상품코드
2124940
자동판매기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vending Machine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
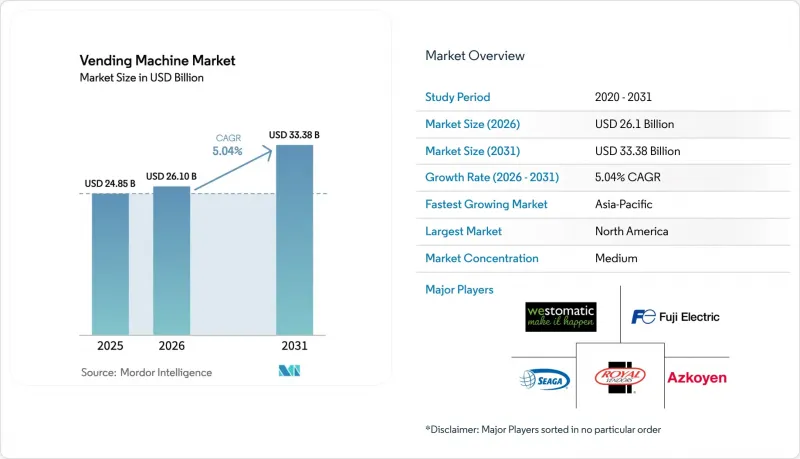
에 의하면, 자동판매기 시장 규모는 2025년 248억 5,000만 달러로 평가되었습니다. 2026년에는 261억 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.04%로 성장을 지속하여, 2031년에는 333억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 기술별(자동, 반자동, 스마트/IoT 지원), 제품 유형별(스낵·포장 식품, 음료, 기타), 용도/설치 장소별(상업용 건물·사무실,교통 거점, 교육 기관, 기타), 결제 수단별(현금, 카드형 무현금 결제, 모바일 지갑·QR 코드, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동판매기 시장 동향 및 인사이트
외출 시 소비를 목적으로 하는 포장 식품 및 신선 식품에 대한 수요 증가
통근자, 사무직 근로자, 학생들이 기존 소매점보다 속도와 편의성을 우선시하는 가운데, 푸드서비스의 편의성이 전 세계 자동판매기 시장을 지속적으로 견인하고 있습니다. 미국 노동통계국의 기록에 따르면, 1997년부터 2025년에 걸쳐 자동판매기 식품 가격은 140.66% 상승했으며, 특히 2023년에는 14.81%의 현저한 상승이 나타나 이 카테고리의 가격 결정력이 입증되었습니다. 도쿄의 AI 탑재 샐러드 자동판매기는 손실(재고 감소)을 최소화하고 이익률을 높이기 위해 가격을 동적으로 조정하고 있습니다. 운영 사업자는 예측 수요 모델을 활용하여 각 세부 입지별로 SKU를 미세 조정함으로써 폐기물을 줄이고, 1제곱피트당 수익을 향상시키고 있습니다. 또한, CA 포장(Controlled Atmosphere Packaging) 공급업체와의 제휴를 통해 신선 식품의 유통 기한을 5일로 연장할 수 있게 되어, 교통 허브나 고등 교육 기관 캠퍼스에서 취급하는 상품의 폭이 넓어지고 있습니다.
무현금 및 비접촉식 결제 기술의 급속한 보급
세계 자동판매기 시장의 두 번째 호재는 동전과 지폐가 ‘탭 앤 고(Tap & Go)’나 QR 코드 기반 결제 수단으로 꾸준히 대체되고 있다는 점이며, 2030년까지 연평균 성장률(CAGR) 12.65%로 확대될 것으로 전망됩니다. 칸타로프(Kantarope)는 2024년, 북미·남미 및 유럽 전역에서 115만 대 이상의 연결 단말기를 처리하며, 결제 현대화를 뒷받침하는 규모의 경제성을 부각시켰습니다. 2024년 7월 일본의 지폐 디자인 변경은 기존 기기의 개조가 얼마나 복잡한지를 여실히 보여줍니다. 도입 초기, 개조가 완료된 자동판매기는 전체의 고작 30%에 불과했으며, 사업자들은 업그레이드 비용과 매출에 미치는 영향을 저울질할 수밖에 없었습니다. 인도에서는 인도 중앙은행이 진행한 QR 코인 시범 사업에서 유동 인구가 많은 장소에 디지털 지갑이 설치되어, 신흥 시장이 지폐와 동전을 건너뛰고 디지털 결제로 전환될 가능성이 있음을 시사하고 있습니다. 2-5%의 결제 수수료가 매출 총이익률을 압박하고 있지만, 사업자들은 평균 고객당 매출액 상승과 현금 취급에 따른 간접비 절감을 통해 그 가치를 회수하고 있습니다.
막대한 자본 지출, 설치비 및 유지 관리비
초기 투자는 여전히 전 세계 자동판매기 시장에 새로 진입하는 업체들에게 장벽이 되고 있습니다. 냉장 기능, 비전 센싱, 멀티 결제 모듈을 갖춘 최신 스마트 단말기는 기존 코일식 자동판매기에 비해 상당히 높은 설비 투자가 필요합니다. 또한 사업자는 소프트웨어 라이선스, 통신 환경, EMV-Co 인증 리더기 등 규제 준수를 위한 업그레이드 비용도 예산에 반영해야 합니다. 원자재 가격 변동도 추가적인 부담이 되고 있습니다. 미국 재무부의 2024년 구리 가격 재검토에 따르면, 2024년 거래의 69.5%를 차지하는 동전 처리 장치의 이익률 압박이 부각되었습니다. 많은 신흥국에서 대출 기준이 엄격해짐에 따라 투자 회수 기간이 길어지고 있어, 소규모 노선 소유자들은 차량 교체를 미룰 수밖에 없는 상황입니다.
부문별 분석
오랫동안 세계 자동판매기 시장의 주류를 이루었던 자동판매기는 2025년에 세계 시장 점유율의 55.12%를 차지했습니다. 광범위한 도입 기반은 예측 가능한 수익의 토대가 되고 있지만, 성장을 가속하는 요인은 제한적입니다. 한편, 스마트/IoT 단말기는 연평균 성장률(CAGR) 9.78%로 확대되고 있으며, 이는 소프트웨어 중심의 비즈니스 모델로의 장기적인 전환을 시사합니다. 커넥티드 단말기에 기인한 전 세계 자동판매기 시장 규모는 2025년 79억 달러에서 2031년까지 138억 4,000만 달러로 확대될 것으로 예측됩니다. 이러한 성장을 통해 클라우드 기반 차량 관리 대시보드 및 프로그래매틱 광고와 같은 부가 수익이 창출되어, 하드웨어의 이익률 압박을 완화할 것입니다.
특허 출원 현황 또한 혁신의 여지가 있음을 뒷받침하고 있습니다. 코카콜라의 미량 성분 관리 관련 특허로 인해 원격으로 맛을 조절할 수 있게 되어 서비스 요청 횟수가 감소하고 있습니다. 또한, 블록 단위의 세밀한 수준에서 상품 구성을 최적화하는 알고리즘을 활용한 플래노그램은 모바일 데이터 통신 요금 하락에 따라 상업적 실현 가능성이 높아지고 있습니다. AI 모듈이 실시간 수요에 따라 SKU의 진열 배치를 재구성하면, 조기 도입 기업들로부터 매출 전환율이 두 자릿수 성장을 보였다는 보고가 접수되고 있습니다. 이러한 배경으로 인해, ROI가 제한적인 과도기적 형태인 반자동 자동판매기는 점차 감소하는 추세에 있습니다.
음료는 2025년 매출의 32.85%를 차지하며 여전히 중심적인 위치를 유지했습니다. 그러나 지속가능성에 관한 법규제로 인해 리버스 벤딩 머신은 연평균 성장률(CAGR) 10.71%라는 가장 빠른 성장세를 보이고 있습니다. 더 많은 관할 구역에서 보증금 제도가 의무화됨에 따라, 전 세계 자동판매기 시장 규모에서 이 부문이 차지하는 비중은 2031년까지 3배로 증가할 것으로 예측됩니다. 기존의 스낵 및 포장 식품 자동판매기는 여전히 주요 식사 상황에서 이용되고 있지만, 염분 및 당분에 대한 규제로 인해 상품 라인업의 재검토가 요구되고 있습니다. PPE(개인보호구(PPE))나 휴대폰 액세서리와 같은 비식품 계열 일용품은 취급량 감소가 가격 탄력성에 의해 상쇄되고 있는 점도 있어, 더 이상 틈새 시장이 아닙니다.
TOMRA가 연간 480억 개의 용기를 회수하고 있다는 사실은 규모 확대가 폐기물 관리의 경제성에 얼마나 기여하는지를 여실히 보여줍니다. 2025년에는 EU의 여러 식료품점이 매장 내에 압축기를 도입하여 반환 과정에서 물류 비용을 절감함으로써 사업자의 투자 수익률(ROI)을 향상시켰습니다. 이와 병행하여, 도쿄에서는 AI를 활용한 신선식품 판매 유닛이 동적 가격 책정 엔진을 사용하여 신선식품 재고 감소라는 역풍을 극복할 수 있음을 입증함으로써, 메뉴의 추가적인 다양화가 효과적이라는 사실이 뒷받침되고 있습니다.
지역별 분석
북미는 널리 보급된 광대역 및 카드 결제 인프라를 활용하여 2025년 전 세계 자동판매기 시장 매출의 32.74%를 차지했습니다. 미국에서는 팬데믹 이후 위생 대책을 우선시하여 정부 청사 전체에 비접촉식 개인보호구(PPE)(PPE) 디스펜서를 도입했습니다. 한편, 캐나다에서는 탄소 배출 감축 목표를 계기로 에너지 효율이 높은 냉장 설비로 개조가 진행되었습니다. 멕시코는 시장 규모는 작지만, 주요 음료 제조업체들이 예상되는 생산자책임회수(EPR)법에 대비하는 가운데, 리버스 벤딩 시범 사업을 확대되고 있습니다. 인건비 급등으로 인해 이 세 시장 모두에서 자동화 도입이 가속화되고 있으며, 시장 성숙화에 따른 압박에도 불구하고 한 자릿수 중반대의 성장률을 유지하고 있습니다.
아시아태평양은 9.86%라는 가장 높은 연평균 성장률(CAGR)이 예상되며, 도시로의 인구 이동과 모바일 머니의 보급을 통해 세계 자동판매기 시장에 중요한 규모를 기여하고 있습니다. 중국에서는 QR 코드를 중시하는 소비자 문화가 스마트 단말기의 보급을 가속화하고 있지만, 일본에서는 지폐·동전 디자인 변경으로 인해 구형 기기의 70%가 일시적으로 규격에 부합하지 않게 되는 과제에 직면해 있습니다. 태국의 ‘타오 빈’ 네트워크는 6,000대의 단말기를 통해 하루 20만 잔의 음료를 판매하고 있으며, 이는 노동력 대체의 경제적 효과를 보여주는 좋은 사례입니다. 인도 중앙은행의 QR 코인 도입 노력은 소규모 소매 결제의 현대화를 위한 정부 주도의 추진을 시사합니다.
유럽의 동향은 보다 꾸준하지만, 규제 측면에서의 지원에 힘입고 있습니다. 영국의 2027년 보증금 반환 제도(Deposit Return Scheme)에 따라 리버스 벤딩 머신의 설치가 확대되고 있는 한편, 독일 브레멘 공항에서는 2025년 6월 AI를 통한 모니터링이 이루어지는 자율형 매장이 문을 열었습니다. 이미 거의 현금 없는 사회로 전환된 스칸디나비아의 사업자들은 현재 기업 캠퍼스를 대상으로 ESG 기준을 준수하는 스낵 상품을 판매하고 있습니다. 남유럽은 모바일 지갑 보급률에서는 뒤처져 있지만, 공항이나 기차역에서의 관광 관련 도입을 통해 격차를 좁혀가고 있으며, 해당 지역은 한 자릿수 후반대의 높은 성장 속도를 유지하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the vending machine market size is expected to grow from USD 24.85 billion in 2025 to USD 26.1 billion in 2026 and is forecast to reach USD 33.38 billion by 2031 at 5.04% CAGR over 2026-2031.
This report is Segmented by Technology (Automatic, Semi-Automatic, and Smart/IoT-Enabled), Product Type (Snacks and Packaged Food, Beverages, and More), Application (Commercial Buildings and Offices, Transportation Hubs, Educational Institutions, and More), Payment Mode (Cash, Card-Based Cashless, Mobile Wallet and QR, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Vending Machine Market Trends and Insights
Increasing Demand for Packaged and Fresh Food for On-the-Go Consumption
Food-service convenience continues to lift the global vending machine market as commuters, office staff, and students prioritize speed and accessibility over traditional retail. The U.S. Bureau of Labor Statistics recorded a 140.66% jump in vending-food prices between 1997 and 2025, with a notable 14.81% increase in 2023, confirming the category's pricing power. Tokyo's AI-equipped salad units adjust prices dynamically to minimize shrinkage and elevate margins. Operators overlay predictive-demand models that fine-tune SKUs by micro-location, cutting waste and boosting revenue per square foot. Partnerships with controlled-atmosphere-packaging suppliers now make fresh produce viable for five-day shelf lives, broadening product scope at transportation hubs and higher-education campuses.
Rapid Adoption of Cashless and Contactless Payment Technologies
A second tailwind for the global vending machine market is the steady replacement of coins and bills with tap-and-go or QR-based options, advancing 12.65% CAGR through 2030. Cantaloupe processed more than 1.15 million connected endpoints across the Americas and Europe in 2024, underscoring scale economics behind payment modernization. Japan's July 2024 banknote redesign illustrates the retro-fit complexity: only 30% of machines were reconfigured at launch, forcing operators to weigh upgrade costs against possible sales disruption. In India, the Reserve Bank's QR-coin pilot places digital wallets at high-footfall locations, an early indication that emerging markets may leapfrog physical cash. Although processor fees of 2-5% compress gross margins, operators recoup value via higher average tickets and lower cash-handling overhead.
High Capital, Installation, and Maintenance Expenditures
Up-front investment remains a gating factor for new entrants to the global vending machine market. Modern smart units with refrigeration, vision sensing, and multi-payment modules require meaningfully higher capital outlays than legacy coil machines. Operators must also budget for software licences, connectivity, and regulatory compliance upgrades such as EMV-co-certified readers. Raw-material volatility adds further strain; the U.S. Department of the Treasury's 2024 copper cost review highlighted margin pressure on coin mechanisms that still serve 69.5% of 2024 transactions. Tight lending standards in many emerging economies elongate payback periods, causing smaller route owners to defer fleet renewal.
Other drivers and restraints analyzed in the detailed report include:
- Deployment of IoT-Enabled Smart Vending Fleets for Predictive Maintenance
- Extended-Producer-Responsibility Rules Spurring Reverse-Vending Installations
- Cyber-Security and Data-Privacy Risks for Connected Machines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automatic machines, long the workhorse of the global vending machine market, held 55.12% global vending machine market share in 2025. Their wide installed base anchors predictable revenue but offers fewer upside levers. Smart/IoT units, meanwhile, are scaling at a 9.78% CAGR, signaling a secular shift toward software-centric business models. The global vending machine market size attributed to connected machines is projected to expand from USD 7.9 billion in 2025 to USD 13.84 billion by 2031. This growth unlocks ancillary revenue for cloud-based fleet dashboards and programmatic advertising, cushioning hardware margin compression.
Patent filings corroborate the innovation runway. Coca-Cola's micro-ingredient management patents enable remote flavor tweaks, lowering service calls. Algorithmic planograms that localize assortments at street-block granularity are hitting commercial viability as cellular data prices fall. Early adopters report double-digit upticks in sales conversion when AI modules reorder the SKU face according to real-time demand. Against that backdrop, semi-automatic machines are tapering as a transitional form factor with limited ROI.
Beverages remained kingpin at 32.85% of 2025 revenues; nevertheless, sustainability legislation positions reverse-vending machines as the fastest clip at 10.71% CAGR. Their contribution to global vending machine market size is forecast to triple by 2031 as more jurisdictions introduce mandatory deposit schemes. Traditional snack and packaged-food machines continue to serve core meal occasions, yet salt- and sugar-content regulations require portfolio revamps. Non-food essentials-think PPE and phone accessories-are no longer niche, aided by price elasticity that offsets lower volume throughput.
TOMRA's 48 billion annual container capture underscores how scale addresses waste-management economics. During 2025, several EU grocers integrated on-site compactors, pulling logistics costs out of the return loop and raising operator ROI. Parallel to that, AI-driven fresh-food units in Tokyo are proving that perishables can beat shrinkage headwinds with dynamic pricing engines, validating broader menu diversification.
Complete Report Scope:
- By Technology
- Automatic Vending Machines
- Semi-Automatic Vending Machines
- Smart / IoT-Enabled Vending Machines
- By Product Type
- Snacks and Packaged Food
- Beverages
- Tobacco and Nicotine Products
- Non-Food Essentials (PPE, Electronics, Personal Care)
- Reverse Vending Machines (Recycling)
- By Application / Deployment Location
- Commercial Buildings and Offices
- Transportation Hubs (Airports, Rail, Bus, Metro)
- Educational Institutions
- Healthcare Facilities
- Hospitality and Leisure Venues
- Industrial and Manufacturing Sites
- Others (Residential, Retail Malls)
- By Payment Mode
- Cash
- Card-Based Cashless (Credit/Debit, NFC)
- Mobile Wallet and QR
- Biometric and Facial Recognition
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounted for 32.74% of 2025 global vending machine market revenue, leveraging ubiquitous broadband and card-payments infrastructure. The United States channeled post-pandemic hygiene priorities into contact-free PPE dispensers across government buildings, while Canada's carbon-reduction targets incentivized energy-efficient refrigeration retrofits. Mexico, though smaller, is scaling reverse-vending pilots as beverage majors prepare for anticipated EPR laws. Labor-cost inflation hastens automation uptake across all three markets, sustaining mid-single-digit growth despite maturity pressures.
Asia-Pacific registered the highest 9.86% CAGR outlook, adding critical mass to the global vending machine market through urban migration and mobile money ubiquity. China's QR-first consumer culture accelerates smart-unit penetration, while Japan wrestles with currency redesigns that have rendered 70% of older machines temporarily non-compliant. Thailand's Tao Bin network sells 200,000 drinks daily via 6,000 machines, a poster child for labor substitution economics. India's Reserve Bank QR-coin initiative signals a state-sponsored push to modernize micro-retail payments.
Europe's trajectory is steadier but underpinned by regulatory catalysts. The UK's 2027 Deposit Return Scheme ramps reverse-vending installations, while Germany's Bremen Airport opened an AI-policed autonomous store in June 2025. Scandinavian operators, already largely cashless, now market ESG-compliant snack lines to corporate campuses. Southern Europe lags on mobile-wallet density yet catches up via tourism-linked deployments in airports and railway stations, ensuring the region maintains a high-single-digit growth clip.
- Fuji Electric Co., Ltd.
- Crane Merchandising Systems (Crane NXT)
- Azkoyen Group
- Evoca Group
- SandenVendo GmbH
- Westomatic Vending Services Ltd.
- Royal Vendors, Inc.
- Seaga Manufacturing, Inc.
- Jofemar S.A.
- Selecta Group
- Cantaloupe Inc. (USA Technologies)
- 365 Retail Markets LLC
- TCN Vending Machine Co., Ltd.
- Guangzhou Baoda Intelligent Technology Co., Ltd.
- Daalchini Technologies Pvt. Ltd.
- Canteen Vending Services (Compass Group)
- Aramark Corporation
- FAS International S.p.A.
- Vending.com (Federal Machine Corp.)
- Vendekin Technologies Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing demand for packaged and fresh food for on-the-go consumption
- 4.2.2 Rapid adoption of cashless and contactless payment technologies
- 4.2.3 Deployment of IoT-enabled smart vending fleets for predictive maintenance
- 4.2.4 Extended-producer-responsibility rules spurring reverse-vending installations
- 4.2.5 Workplace ESG targets boosting healthy and sustainable vending offerings
- 4.2.6 Medicine and PPE vending in rural healthcare networks
- 4.3 Market Restraints
- 4.3.1 High capital, installation and maintenance expenditures
- 4.3.2 Sugary-drink and calorie restrictions in public institutions
- 4.3.3 Cyber-security and data-privacy risks for connected machines
- 4.3.4 Hygiene and vandalism concerns in certain public areas
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Sustainability and Circular-Economy Analysis
- 4.9 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Technology
- 5.1.1 Automatic Vending Machines
- 5.1.2 Semi-Automatic Vending Machines
- 5.1.3 Smart / IoT-Enabled Vending Machines
- 5.2 By Product Type
- 5.2.1 Snacks and Packaged Food
- 5.2.2 Beverages
- 5.2.3 Tobacco and Nicotine Products
- 5.2.4 Non-Food Essentials (PPE, Electronics, Personal Care)
- 5.2.5 Reverse Vending Machines (Recycling)
- 5.3 By Application / Deployment Location
- 5.3.1 Commercial Buildings and Offices
- 5.3.2 Transportation Hubs (Airports, Rail, Bus, Metro)
- 5.3.3 Educational Institutions
- 5.3.4 Healthcare Facilities
- 5.3.5 Hospitality and Leisure Venues
- 5.3.6 Industrial and Manufacturing Sites
- 5.3.7 Others (Residential, Retail Malls)
- 5.4 By Payment Mode
- 5.4.1 Cash
- 5.4.2 Card-Based Cashless (Credit/Debit, NFC)
- 5.4.3 Mobile Wallet and QR
- 5.4.4 Biometric and Facial Recognition
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 UAE
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration Analysis
- 6.2 Strategic Moves and Developments
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global overview, Market overview, Core segments, Financials as available, Strategic info, Market rank/share, Products and services, Recent developments)
- 6.4.1 Fuji Electric Co., Ltd.
- 6.4.2 Crane Merchandising Systems (Crane NXT)
- 6.4.3 Azkoyen Group
- 6.4.4 Evoca Group
- 6.4.5 SandenVendo GmbH
- 6.4.6 Westomatic Vending Services Ltd.
- 6.4.7 Royal Vendors, Inc.
- 6.4.8 Seaga Manufacturing, Inc.
- 6.4.9 Jofemar S.A.
- 6.4.10 Selecta Group
- 6.4.11 Cantaloupe Inc. (USA Technologies)
- 6.4.12 365 Retail Markets LLC
- 6.4.13 TCN Vending Machine Co., Ltd.
- 6.4.14 Guangzhou Baoda Intelligent Technology Co., Ltd.
- 6.4.15 Daalchini Technologies Pvt. Ltd.
- 6.4.16 Canteen Vending Services (Compass Group)
- 6.4.17 Aramark Corporation
- 6.4.18 FAS International S.p.A.
- 6.4.19 Vending.com (Federal Machine Corp.)
- 6.4.20 Vendekin Technologies Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Forecast of Technology Convergence and New Business Models