

|
시장보고서
상품코드
2125272
전기 구동 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Electric Drives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
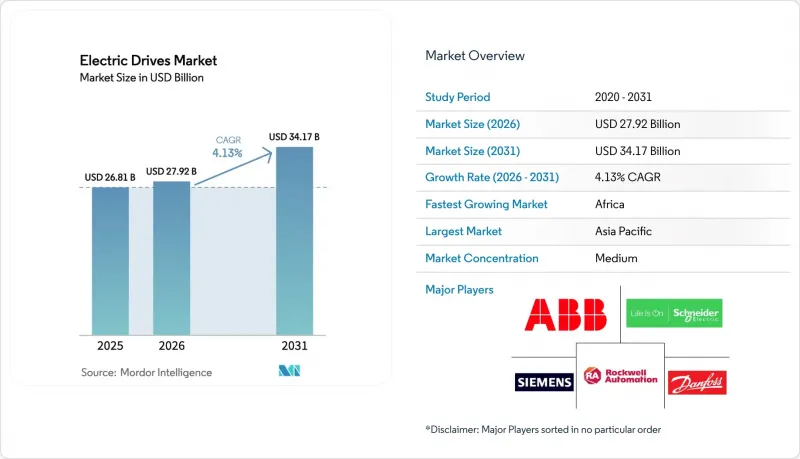
에 의하면, 2026년 전기 구동 시장 규모는 279억 2,000만 달러로 추정되고 2025년 268억 1,000만 달러에서 확대해, 2031년에는 341억 7,000만 달러에 이를 것으로 예측됩니다. 2026-2031년에 걸친 CAGR은 4.13%를 나타낼 전망입니다.
본 보고서는 제품별(교류 드라이브, DC 드라이브, 서보 드라이브), 전압별(저전압 드라이브, 중전압 드라이브), 정격 출력별(250kW 미만, 251-500kW, 500kW 초과),최종 사용자 산업별(석유 및 가스, 상수도·폐수 처리, 화학제품 및 석유화학제품, 식음료, 발전, HVAC, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 제시되어 있습니다.
세계의 전기 구동 시장 동향 및 인사이트
전 세계 및 각국의 엄격한 에너지 효율 규제
미국, 유럽, 중국의 새로운 규제로 인해 모터의 최소 효율 기준이 상향 조정되었으며, 에너지 소비가 많은 플랜트에서는 가변 주파수 드라이브의 도입이 사실상 의무화되었습니다. 산업 감사에 따르면, 모터는 제조 현장의 전력 소비량의 최대 70%를 차지하며, 정속 스타터를 대체함으로써 이산화탄소 배출량과 비용을 대폭 절감할 수 있습니다. 현재 각국 정부는 세제 혜택 및 보조금 프로그램을 검증된 드라이브 개조와 연계하고 있으며, 이로 인해 인증된 제품에 대한 예측 가능한 수요가 발생하고 있습니다. 이에 대응하여 각 벤더사는 3년 이내에 투자 회수가 가능함을 정량적으로 입증하는 에너지 평가 소프트웨어를 드라이브에 포함시켜 대응하고 있습니다. 그 결과, 전기 구동 시장은 정책 시행에 뒷받침된 지속 가능한 업데이트 주기를 확보하고 있습니다.
고정밀 드라이브가 필요한 e-모빌리티 생산 라인의 확대
전기자동차 공장의 배터리 조립, 모터 권선, 품질 관리 스테이션에서는 0.1mm 미만의 반복 정밀도가 요구되며, 서보 드라이브가 생산 라인 설계의 핵심을 담당하고 있습니다. 자동차 OEM 각사는 전동화를 위해 1,000억 달러 이상을 투자하고 있으며, 신규 공장(그린필드)에서는 건설 초기부터 첨단 모션 패키지가 사양으로 채택되고 있습니다. 내연기관 공장의 기존 설비(브라운필드) 개조에서도 기존 컨베이어가 서보 구동 방식의 유연한 셀로 대체되고 있습니다. 서보 벤더 각사는 로봇과의 연동을 간소화하기 위해 통합형 안전 기능 및 분산형 I/O를 추가하여 플러그 앤 플레이 방식의 도입을 가속화하고 있습니다. 이러한 지속적인 자금 유입으로 인해 전기 구동 시장은 e-모빌리티 투자의 주요 수혜자로서의 입지를 공고히 하고 있습니다.
고정 속도형 대안에 비해 높은 초기 설비 투자 비용
가변 주파수 드라이브의 비용은 접촉기 스타터의 3배에서 5배에 달하기 때문에 자금 사정이 어려운 공장에서는 설비 투자가 장벽이 됩니다. 3년 미만의 투자 회수 기간은 재무에 정통한 운영자에게 매력적이지만, 전기 요금이 보조금 대상인 경우 여전히 많은 기업이 업그레이드를 미루고 있습니다. 이러한 반대 의견은 절대적인 절감액이 적고 손익분기점까지의 기간이 길어지는 15kW 미만 범위에서 특히 두드러집니다. 드라이브 리스나 EaaS(Energy-as-a-Service)와 같은 자금 조달 수단이 등장하고 있지만, 북미와 서유럽 이외의 지역에서는 여전히 제한적입니다. 향후에는 반도체 가격 하락이나 전력 회사의 인센티브로 인해 이러한 장벽이 완화되어 전기 구동 시장의 잠재 수요가 확대될 가능성이 있습니다.
부문별 분석
2025년, 교류 드라이브는 전기 구동 시장에서 70.62%라는 압도적인 점유율을 차지했습니다. 이는 전 세계 공장 자동화를 뒷받침하는 펌프, 팬, 컨베이어 라인에서 교류 드라이브의 범용성을 반영한 것입니다. 표준화된 인터페이스, 성숙한 부품 공급망, 설치 업체들의 폭넓은 숙련도가 수요를 뒷받침하고 있으며, 특히 신뢰성이 최첨단 성능보다 더 중요하게 여겨지는 식품 가공 및 상수도 유틸리티 분야에서 두드러집니다. 예측 기간 동안 전력 회사의 원심 장비 효율 목표가 더욱 엄격해지는 가운데, 전기 구동 시장은 기본적인 모터 제어에 있어 계속해서 AC 플랫폼에 의존할 것으로 보입니다. 서보 드라이브는 배터리, 전자기기, 의료기기 조립 과정에서 서브 마이크로미터 단위의 정밀 위치 결정이 필요한 맞춤형 제조 공장 덕분에 2031년까지 연평균 성장률(CAGR) 4.25%를 유지하며 여전히 가장 빠르게 성장하는 틈새 시장입니다. 각 서보 벤더는 현재 통합된 안전 기능과 단일 케이블 네트워크를 패키지로 제공함으로써, 상품화된 AC 유닛과는 차별화된 프리미엄 제품을 제공합니다.
전기 구동 시장은 서보 알고리즘이 하이엔드 AC 패키지에 도입되는 기술적 교차점의 혜택을 받고 있으며, 기존 제품 라인의 경계가 모호해지는 한편, 중견 사용자에게는 매력적인 비용 곡선이 유지되고 있습니다. 한때 금속 및 광업 부문에서 선호되던 DC 드라이브는 현대의 AC 벡터 제어가 더 낮은 유지보수 비용으로 동등한 토크 정밀도를 실현할 수 있게 되면서 현재는 시장 점유율이 축소되고 있습니다. 그러나 일부 압연기 사업자는 레거시 시스템과의 호환성을 이유로 여전히 DC 유닛을 지정하고 있으며, 이로 인해 소폭이지만 교체 수요가 발생하고 있습니다. AC, 서보, DC 각 축을 단일 랙에 통합한 멀티 드라이브 플랫폼이 주목을 받고 있으며, 특히 모션 클래스를 초월한 통일된 프로그래밍을 중시하는 기계 제조업체인 OEM 각 사로부터 지지를 얻고 있습니다. 이러한 융합은 주요 공급업체의 라이프사이클 서비스 수익을 뒷받침하며, 전기 구동 시장 전체의 적정한 집중화를 강화하고 있습니다.
1kV 미만의 저전압 시스템은 2025년 매출의 62.98%를 차지하며, 공장의 펌프, 압축기, 자재관리 라인의 대부분을 뒷받침했습니다. 설치 편의성, 성형 케이스형 보호 장치의 쉬운 입수성, 기술자의 기술 세트가 널리 보급되어 있어 총 소유 비용이 낮게 유지되고 있으며, 이는 전기 구동 시장이 표준 제조 부문에서 저전압을 핵심으로 유지할 것임을 보장합니다. 그럼에도 불구하고, 성장은 중전압 장비에 집중되어 있으며, 중공업 사업자들이 대형 모터를 가변 속도 운전으로 업그레이드함에 따라 2031년까지 연평균 성장률(CAGR) 4.62%로 확대될 것으로 예측됩니다.
중전압 프로젝트는 일반적으로 LNG, 시멘트, 해수 담수화 플랜트에서 기존 시설의 생산 능력 확대나 신규 시설에 대한 투자 시에 등장하며, 이 경우 펌프나 압축기의 출력이 2MW를 초과합니다. 사업자들은 여러 대의 저전압 모터를 병렬로 운전하는 경우와 비교하여 역률 향상 및 케이블 손실 감소를 도모할 수 있기 때문에 이러한 솔루션을 선호하고 있습니다. 준 2레벨 인버터 토폴로지, 실리콘 카바이드 소자,회생 기능은 현재 프리미엄 중전압 패키지의 차별화 요소로 작용하며, 공급업체가 더 높은 이익률을 정당화하는 데 일조하고 있습니다. 고조파 저감 및 계통 지원 모드와 같은 계통 연계 기능은 광업 및 외딴 지역의 유전에서 막 시작된 마이크로그리드 프로그램과 부합하며, 복원력의 가치를 높이고 있습니다. 그 결과, 전기 구동 시장에서는 양극화가 나타나고 있습니다. 상품화된 저전압 제품이 규모를 유지하는 한편, 기술적으로 고도화된 중전압 유닛은 그에 상응하지 않을 정도의 이익을 창출하고 있습니다.
지역별 분석
2025년, 아시아태평양은 전동 구동 장치 시장에서 45.10%라는 최대 점유율을 유지했습니다. 이는 중국의 2024년 자동화 관련 지출 500억 달러와 인도의 인센티브를 배경으로 한 공장 건설 확대에 힘입은 결과입니다. 중국 기업들은 자국의 최신 에너지 집약도 규제를 충족하기 위해 기존 스타터를 가변 속도 패키지로 계속 교체하고 있는 반면, 양쯔강 삼각주 일대의 배터리 기가팩토리 집적지에서는 서보 도입이 가속화되고 있습니다. 인도의 ‘생산 연계 인센티브(PLI)’ 제도는 백색가전의 현지 생산을 촉진하여, 판금 프레스 및 사출 성형기에서 중저가 서보 수요를 뒷받침하고 있습니다. 일본과 한국은 여전히 기술 최첨단을 달리고 있으며, 협동 로봇 셀 및 반도체 팹용으로 AI 지원 고성능 드라이브를 구매하고 있습니다. 한편, 동남아시아 국가들은 시험적인 자동화 셀에서 본격적인 생산 라인으로 전환하고 있습니다. 이러한 움직임이 맞물려 전기 구동 시장에서 해당 지역의 우위가 확고해지고 있습니다.
북미에서는 기존 공장(브라운필드)이 미국 에너지부(DOE)의 모터 규제를 준수하고, 수요 반응(Demand Response)을 위한 전력 회사로부터의 리베이트를 활용하기 위해 드라이브를 개조하고 있어 꾸준한 교체 수요가 발생하고 있습니다. 오대호 주변 자동차 산업의 리쇼어링(국내 복귀) 움직임이 새로운 서보 수주를 촉진하고 있으며, 이는 디스크리트 제조 부문 내 전기 구동 시장 규모를 부각시키고 있습니다. 캐나다 광업 부문에서는 칼리 및 니켈 생산 확대에 따라 중전압 패키지가 도입되고 있는 반면, 멕시코의 Tier 1 자동차 부품 공급업체들은 변속기 하우징 가공 센터용으로 안전 기능이 통합된 서보를 지정하고 있습니다. 이와 병행하여 예측 유지보수용 클라우드 플랫폼의 동향이 진전되고 있어, 국내 소프트웨어 생태계를 뒷받침하고, 하드웨어 출하에 디지털 서비스가 통합되는 것이 확실해지고 있습니다.
유럽은 성숙해 가고 있지만 여전히 혁신 주도형 시장이며, 인더스트리 4.0 로드맵과 유럽 그린 딜을 통해 가변 속도 기술의 보급이 더욱 촉진되고 있습니다. 독일의 자동화 수출 기업들은 자석 소재의 위험을 줄이기 위해 동기 릴랙턴스 드라이브를 요구하고 있으며, 이탈리아의 기계 OEM 업체들은 지적 재산을 보호하기 위해 사이버 보안 대책이 적용된 펌웨어를 탑재하고, 북유럽의 공정 플랜트들은 재생에너지 비율이 높은 전력망을 강화하기 위해 회생 드라이브를 채택하고 있습니다. 아프리카는 현재 시장 규모는 작지만, 남아프리카공화국의 광산에서 운반 트럭의 전동화가 진행되고, 나이지리아의 시멘트 프레스에 중전압 인버터가 도입되는 등 2031년까지 연평균 성장률(CAGR)이 5.26%로 가장 높은 성장세를 보이고 있습니다. 또한, 노동 집약적인 공정을 북아프리카로 이전하는 유럽 제조업체들도 현지에서 서보 시스템의 채택을 촉진하고 있습니다. 이러한 동향들이 맞물리면서 지역별 수익원이 다양화되고, 전기 구동 시장의 장기적인 성장 궤도가 안정화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, electric drives market size in 2026 is estimated at USD 27.92 billion, growing from 2025 value of USD 26.81 billion with 2031 projections showing USD 34.17 billion, growing at 4.13% CAGR over 2026-2031.
This report is Segmented by Product (AC Drives, DC Drives, and Servo Drives), Voltage (Low-Voltage Drive, and Medium-Voltage Drive), Power Rating (Less Than 250 KW, 251-500 KW, and More Than 500 KW), End-User Industry (Oil and Gas, Water and Wastewater, Chemical and Petrochemical, Food and Beverage, Power Generation, HVAC, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Electric Drives Market Trends and Insights
Stringent Global and National Energy-Efficiency Mandates
New U.S., European and Chinese rules elevate minimum motor efficiency levels, effectively compelling variable-frequency drive adoption in energy-intensive plants. Industrial audits show motors consuming up to 70% of manufacturing electricity, so replacing fixed-speed starters yields sizable carbon and cost savings. Governments now link tax incentives and grant programs to verified drive retrofits, creating predictable demand for certified products. Vendors respond by packaging drives with energy-assessment software that quantifies payback in under three years. As a result, the electric drives market gains a durable replacement cycle anchored in policy enforcement.
Acceleration of E-Mobility Production Lines Needing High-Precision Drives
Battery assembly, motor winding and quality-control stations in electric-vehicle plants require sub-0.1 millimeter repeatability, placing servo drives at the heart of line design Automotive OEMs have committed more than USD 100 billion toward electrification, and each greenfield factory specifies advanced motion packages from day one. Brownfield retrofits of internal-combustion plants also replace legacy conveyors with servo-based flexible cells. Servo vendors add integrated safety and decentralized I/O to simplify robot collaboration, accelerating plug-and-play deployment. This continuous capital flow cements the electric drives market as a primary beneficiary of e-mobility investment.
High Initial Capex Versus Fixed-Speed Alternatives
Variable-frequency drives cost three to five times more than contactor starters, making capex a hurdle in cash-constrained plants. Payback periods under three years appeal to financially savvy operators, yet many still defer upgrades when electricity is subsidized. The objection is acute in sub-15 kW ranges where absolute savings are modest, extending breakeven timelines. Financing options such as drive-leasing or energy-as-a-service are emerging but remain scarce outside North America and Western Europe. Over time, falling semiconductor prices and utility incentives may ease the barrier, widening addressable demand in the electric drives market.
Other drivers and restraints analyzed in the detailed report include:
- Digital Retrofits - Variable-Speed Drives for Brownfield Energy Savings
- AI-Enabled Predictive Maintenance Reducing Downtime of Drive Systems
- Cyber-Security Vulnerabilities in Network-Connected Smart Drives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
AC drives held a dominant 70.62% electric drives market share in 2025, reflecting their versatility in pumps, fans and conveyor lines that underpin global factory automation. Standardized interfaces, mature component supply chains and broad installer familiarity sustain demand, particularly in food processing and water utilities where reliability trumps cutting-edge performance. Over the forecast horizon, the electric drives market will continue to rely on AC platforms for baseline motor control as utilities tighten efficiency targets in centrifugal equipment. Servo drives remain the fastest-growing niche with a 4.25% CAGR through 2031 thanks to discrete manufacturing plants that require sub-micrometer positioning in battery, electronics and medical-device assembly. Servo vendors now bundle integrated safety functions and one-cable networks, distinguishing their premium offerings from commoditized AC units.
The electric drives market benefits from a technology crossover as servo algorithms migrate into high-end AC packages, blurring historic product lines while keeping cost curves attractive for mid-tier users. DC drives, once favored in metals and mining, now occupy shrinking pockets because modern AC vector control replicates their torque fidelity at lower maintenance cost. Yet some rolling-mill operators still specify DC units for legacy compatibility, providing a modest replacement stream. Multi-drive platforms that combine AC, servo and DC axes in a single rack are gaining attention, especially among machine-builder OEMs that value unified programming across motion classes. This convergence supports life-cycle service revenues for top suppliers, reinforcing moderate concentration in the broader electric drives market.
Low-voltage systems below 1 kV accounted for 62.98% of 2025 revenue, underpinning most factory pumps, compressors and material-handling lines. Installation simplicity, ready availability of molded-case protection gear and widespread technician skill sets keep total ownership cost low, ensuring that the electric drives market retains a low-voltage core in standard manufacturing. Growth nonetheless skews toward medium-voltage equipment, which is projected to advance at a 4.62% CAGR through 2031 as heavy-industry operators upgrade large motors to variable-speed duty.
Medium-voltage projects typically surface during brownfield capacity expansions or greenfield investments in LNG, cement and desalination plants, where pumps or compressors exceed 2 MW. Operators favor these solutions for improved power factor and reduced cable losses relative to running multiple low-voltage motors in parallel. Quasi-two-level inverter topologies, silicon-carbide devices and regenerative capabilities now differentiate premium medium-voltage packages, helping suppliers justify higher margins. Utility-interactive features such as harmonic mitigation and grid-support modes align with nascent microgrid programs in mining and remote oilfields, adding resilience value. As a result, the electric drives market sees a bifurcation: commoditized low-voltage volumes sustain scale while technologically sophisticated medium-voltage units generate disproportionate profit pools.
Complete Report Scope:
- By Product
- AC Drives
- DC Drives
- Servo Drives
- By Voltage
- Low-Voltage Drive
- Medium-Voltage Drive
- By Power Rating
- Less than 250 kW
- 251-500 kW
- Above 500 kW
- By End-User Industry
- Oil and Gas
- Water and Wastewater
- Chemical and Petrochemical
- Food and Beverage
- Power Generation
- HVAC
- Pulp and Paper
- Discrete Industries
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- Italy
- United Kingdom
- France
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific retained the largest share of the electric drives market in 2025 at 45.10%, sustained by China's USD 50 billion 2024 automation spend and India's incentive-backed factory build-out. Chinese enterprises continue to replace legacy starters with variable-speed packages to satisfy the country's latest energy-intensity mandate, while servo adoption accelerates in battery-gigafactory clusters along the Yangtze River Delta. India's Production Linked Incentive scheme drives localized manufacturing of whitegoods, spurring mid-range servo demand in sheet-metal presses and injection-molding machines. Japan and South Korea remain technology front runners, purchasing premium AI-enabled drives for collaborative robot cells and semiconductor fabs, whereas Southeast Asian nations advance from pilot automation cells to full production lines. These combined activities cement regional primacy in the electric drives market.
North America delivers steady replacement demand as brownfield plants retrofit drives to meet U.S. DOE motor rules and leverage utility rebates for demand-response. Automotive reshoring initiatives around the Great Lakes trigger fresh servo orders, underscoring the electric drives market size within discrete manufacturing. Canada's mining sector deploys medium-voltage packages in potash and nickel expansions, while Mexico's tier-one automotive suppliers specify safety-integrated servos for transmission-housing machining centers. A parallel trend toward predictive-maintenance cloud platforms favors domestic software ecosystems, ensuring that digital services layer atop hardware shipments.
Europe represents a mature yet innovation-driven arena where Industry 4.0 roadmaps and the European Green Deal reinforce variable-speed penetration. German automation exporters demand synchronous-reluctance drives to trim magnet material risk, Italian machinery OEMs embed cyber-secure firmware to protect intellectual property, and Nordic process plants adopt regenerative drives to bolster renewable-heavy grids. Africa, although holding a smaller base today, records the fastest 5.26% CAGR to 2031 as South African mines electrify haul trucks and Nigerian cement presses install medium-voltage inverters. European manufacturers relocating labor-intensive stages to North Africa also lift localized servo uptake. Collectively, these patterns diversify regional revenue streams, stabilizing the long-term trajectory of the electric drives market.
- ABB Ltd.
- Siemens AG
- Danfoss A/S
- Rockwell Automation Inc.
- Schneider Electric SE
- Yaskawa Electric Corporation
- Mitsubishi Electric Corporation
- Nidec Corporation
- SEW-EURODRIVE GmbH and Co KG
- TMEIC Corporation
- WEG S.A.
- Hitachi Ltd.
- Fuji Electric Co. Ltd.
- Eaton Corporation plc
- Emerson Electric Co.
- Toshiba International Corporation Inc.
- Parker Hannifin Corporation
- Regal Rexnord Corporation
- Johnson Electric Holdings Limited
- Bonfiglioli Riduttori S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Market Drivers
- 4.3.1 Rapid industrialisation in process and discrete manufacturing hubs
- 4.3.2 Stringent global and national energy-efficiency mandates
- 4.3.3 Acceleration of e-mobility production lines needing high-precision drives
- 4.3.4 Digital retrofits - variable-speed drives for brownfield energy savings
- 4.3.5 AI-enabled predictive maintenance reducing downtime of drive systems
- 4.3.6 Shift toward rare-earth-free topologies (axial-flux, switched-reluctance)
- 4.4 Market Restraints
- 4.4.1 High initial capex versus fixed-speed alternatives
- 4.4.2 Reliability concerns in harsh-duty, high-harmonic environments
- 4.4.3 Supply-chain volatility for power-electronic components and magnets
- 4.4.4 Cyber-security vulnerabilities in network-connected smart drives
- 4.5 Industry Ecosystem Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 AC Drives
- 5.1.2 DC Drives
- 5.1.3 Servo Drives
- 5.2 By Voltage
- 5.2.1 Low-Voltage Drive
- 5.2.2 Medium-Voltage Drive
- 5.3 By Power Rating
- 5.3.1 Less than 250 kW
- 5.3.2 251-500 kW
- 5.3.3 Above 500 kW
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Water and Wastewater
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Food and Beverage
- 5.4.5 Power Generation
- 5.4.6 HVAC
- 5.4.7 Pulp and Paper
- 5.4.8 Discrete Industries
- 5.4.9 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 Italy
- 5.5.3.3 United Kingdom
- 5.5.3.4 France
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 Danfoss A/S
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Schneider Electric SE
- 6.4.6 Yaskawa Electric Corporation
- 6.4.7 Mitsubishi Electric Corporation
- 6.4.8 Nidec Corporation
- 6.4.9 SEW-EURODRIVE GmbH and Co KG
- 6.4.10 TMEIC Corporation
- 6.4.11 WEG S.A.
- 6.4.12 Hitachi Ltd.
- 6.4.13 Fuji Electric Co. Ltd.
- 6.4.14 Eaton Corporation plc
- 6.4.15 Emerson Electric Co.
- 6.4.16 Toshiba International Corporation Inc.
- 6.4.17 Parker Hannifin Corporation
- 6.4.18 Regal Rexnord Corporation
- 6.4.19 Johnson Electric Holdings Limited
- 6.4.20 Bonfiglioli Riduttori S.p.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


