

|
시장보고서
상품코드
2125289
교류 전기 구동 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Alternating Current (AC) Electric Drives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
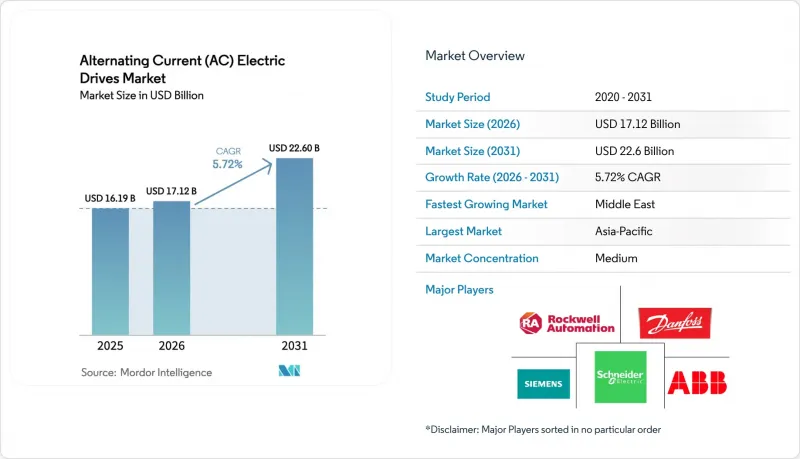
에 의하면, 교류 전기 구동 시장 규모는 2025년에 161억 9,000만 달러로 평가되었습니다. 2026년 171억 2,000만 달러에서 성장하여 2031년까지 226억 달러에 이를 것으로 예상됩니다. 예측 기간(2026-2031년) CAGR은 5.72%를 나타낼 전망입니다.
본 보고서는 전압별(저전압, 중전압 및 기타), 정격 출력별(1MW 이하, 1-3MW, 3MW 초과), 용도별(펌프, 팬, 압축기, 기타), 최종 사용자 산업별(석유 및 가스,화학제품 및 석유화학제품, 식음료, 상·하수도 처리, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 교류 전기 구동 시장 동향 및 인사이트
제조업 분야의 자동화 진전
스마트 팩토리에 대한 투자로 인해 시장에서 교류 전기 구동의 도입이 가속화되고 있습니다. 이는 경영진이 에너지 효율 향상을 결정적인 비용 절감 요인으로 인식하고 있기 때문입니다. ABB는 2024년 11월, 98%의 효율로 작동하며 고조파 왜곡을 50% 저감하는 중전압 플랫폼 ‘ACS8080’을 출시했습니다. 팬의 가변 속도 개조만으로도 전력 사용량을 최대 30% 절감할 수 있어, 이를 통해 추가적인 자동화 업그레이드를 위한 예산을 확보할 수 있습니다. 드라이브에서 플랜트의 히스토리안으로 전송되는 실시간 데이터는 예측 유지보수를 통한 품질 관리를 지원하며, 예기치 못한 가동 중지 시간을 줄여줍니다. 중국, 인도, 인도네시아 각국 정부는 세액 공제를 통해 로봇 기술 도입을 장려하고 있으며, 그로 인해 지능형 드라이브 도입 대상이 되는 기존 설비 기반이 확대되고 있습니다.
정부의 규제 강화와 에너지 절약형 장비에 대한 수요 증가
현재 전 세계 모터 출하량의 약 3분의 2가 최소 에너지 성능 기준의 적용 대상입니다. 유럽연합(EU)의 에코디자인 지침과 미국 에너지부의 규제에 따라 공장은 정량적인 에너지 절감 효과를 입증해야 하며, 신규 생산 라인에서 교류 전기 구동 시장 침투는 사실상 필수적입니다. 최종 에너지 소비에서 전력이 차지하는 비율은 2022년 29%에서 2050년까지 52%로 상승할 것으로 예측되어, 모든 모터 구동 시스템에 대한 감시가 엄격해지고 있습니다. 또한, 전력 회사는 수요 반응(Demand Response) 참여에 대해 인센티브를 지급하고 있어, 가변속 드라이브를 장착한 시설은 유연한 부하 용량을 수익화할 수 있게 되었습니다.
높은 초기 도입 비용과 유지 관리 비용
총 도입 비용에는 설계비, 고조파 필터 뱅크, 냉각 시스템 업그레이드, 운영자 교육 등이 포함되며, 경우에 따라 드라이브 정가의 2-3배에 달하기도 합니다. 중소규모 기업의 경우, 투자 회수 기간이 2회계연도를 초과할 경우 프로젝트를 미루는 경우가 있습니다. 기존 설비의 개보수 시에는 배전반의 배선 변경이나 전력 품질 기준 준수 확인으로 인해 예산이 더욱 늘어납니다. 서비스 팀은 DC 링크용 커패시터나 팬 어셈블리를 정기적으로 교체해야 하며, 단순한 스타터에 익숙한 유지보수 부서에게는 이전에는 없던 수명 주기상의 부담이 발생하게 됩니다.
부문별 분석
2025년에는 대부분의 산업용 모터의 전압이 690V 미만이었기 때문에 저전압 유닛이 57.74%라는 최대 점유율을 차지했습니다. 그러나 프로젝트 개발자들은 부하를 통합하는 경향을 보이며, 유지보수를 간소화하기 위해 1MW 유닛 4대보다 4MW 모터 1대를 선호하는 추세입니다. 현재 교류 전기 구동 시장에서는 석유화학, 해수 담수화, 광업 프로젝트에서 멀티 메가와트급 펌프에 대한 투자가 확대되고 있어, 2031년까지 중전압 제품의 예상 매출액이 연평균 성장률(CAGR) 7.52%로 상승할 것으로 전망됩니다. ACS8080의 출시는 높은 출력 밀도와 낮은 고조파 특성을 통해 이러한 드라이브가 기존 시설(브라운필드)에서도 실용화될 수 있음을 보여줍니다. 각 지역의 정유시설에서는 6.6kV VFD를 채택하여 증기 터빈의 보조 시스템을 축소하고 있으며, 이를 통해 넷 제로 로드맵에 따라 공정 열 배출량을 대폭 줄이고 있습니다.
아시아태평양에서는 현지 패널 제조업체들이 턴키 EPC 입찰에 대응하기 위해 중전압 캐비닛에 링 메인 유닛을 통합하고 있습니다. 유럽 기업들은 엄격한 그리드 코드의 플리커 제한을 충족하는 일체형 액티브 프론트엔드 컨버터를 통해 차별화를 꾀하고 있습니다. 한편, 북미의 전력 회사는 제동 에너지를 전력망으로 환원하는 회생형 드라이브 구성을 승인하고 있으며, 이를 통해 전력 품질 개선을 수익화하고 있습니다. 이러한 동향은 향후 10년 말까지 전력 소비가 많은 산업 분야에서 중전압 제품의 보급이 저전압 기존 제품을 대체하는 전환점을 시사합니다.
식품, 음료, 맞춤형 제조 부문의 OEM 기업들은 컨베이어나 믹서용으로 표준화된 프레임을 지정하는 경우가 많기 때문에 2025년 출하 대수의 47.10%는 여전히 1MW 이하 시스템이 차지했습니다. 그러나 교류 전기 구동 시장에서는 3MW를 초과하는 설비의 도입이 연평균 성장률(CAGR) 7.26%로 가장 빠르게 증가하고 있습니다. 이는 수소 전기분해 플랜트, 부유식 LNG 선박, 대규모 탄소 포집 장치가 거대한 압축기의 정밀한 제어를 필요로 하기 때문입니다. 최신 SiC 인버터는 이러한 정격에서 7kHz를 초과하는 스위칭 주파수를 실현하며, 대형 공조 설비가 필요하지 않아 실내 설치가 가능해져 환경 밀봉 비용을 절감할 수 있습니다.
각 OEM 업체들은 5MW 드라이브를 능동형 자기 베어링식 압축기와 세트로 제공하고 있으며, 이를 통해 윤활유 회로가 불필요해져 플랜트의 가동 시간이 향상되고 있습니다. 금속 및 광업 부문에서는 유압 커플링을 고출력 가변속 드라이브로 대체함으로써, 밀 가동 시의 기계적 부하가 경감되어 결과적으로 기어박스의 수명이 연장되고 있습니다. 서비스 제공업체들은 진행 중인 디지털 전환을 활용하여 클라우드를 통한 고조파 감사 및 소프트웨어 패치 제공을 실시하고 있으며, 이로 인해 그동안 복잡성을 이유로 도입을 주저하던 사업자들에게도 대규모 설비 소유가 예전만큼 어렵지 않게 되었습니다.
지역별 분석
아시아태평양은 2025년에 매출의 35.29%를 차지했으며, 이는 산업 전반에 걸친 산업화와 정부의 로봇 공학 지원 정책을 반영한 결과입니다. 중국은 생산과 소비 양면에서 지배적인 위치를 차지하고 있으며, 현지 브랜드들은 리드 타임을 단축하는 대중 시장용 제품을 출시하고 있습니다. 인도의 ‘생산 연계 인센티브(PLI)’ 제도는 시멘트, 철강, 자동차 각 부문 수요를 확대하고 있는 반면, 일본은 파워 디바이스의 소형화를 추진하며 기술 모듈을 전 세계 OEM에 수출하고 있습니다.
북미와 유럽은 성숙해 가고 있지만 여전히 활기찬 시장입니다. 미국의 ‘인플레이션 억제법’은 에너지 효율 개선 개조에 대한 내부수익률을 높이는 세액 공제를 제공하고 있으며, 이를 통해 교류 전기 구동 시장은 탈탄소화 과정에서 중요한 추진력으로서의 입지를 공고히 하고 있습니다. 유럽의 전력 회사는 재생에너지의 간헐성에 대응하여 모터 부하를 조정하는 시설에 인센티브를 제공하는 동적 계통 지원 요금 제도를 도입하고 있습니다. 그 결과, 구매자들은 회생 기능과 낮은 고조파 성능을 갖춘 드라이브를 선호하게 되었습니다.
중동 시장은 사우디아라비아의 NEOM이나 아랍에미리트의 해수 담수화 시설과 같은 메가 프로젝트에 힘입어 연평균 성장률(CAGR) 6.62%의 궤도에 올라 있습니다. 통합형 석유화학 허브에서는 에틸렌 크래커나 해수 취수 펌프용으로 수 메가와트급 드라이브가 지정되어 있습니다. 아프리카와 남미 시장은 광업 확대와 수자원 인프라 투자로 인해 성장세가 가속화되고 있으나, 자금 조달 제약과 애프터서비스 네트워크 부족으로 인해 도입은 제한되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the AC electric drives market size was valued at USD 16.19 billion in 2025 and estimated to grow from USD 17.12 billion in 2026 to reach USD 22.6 billion by 2031, at a CAGR of 5.72% during the forecast period (2026-2031).
This report is Segmented by Voltage (Low Voltage, and Medium Voltage and Others), Power Rating (Up To 1 MW, 1 MW - 3 MW, Above 3 MW), Application (Pumps, Fans, Compressors, and More), End User Industry (Oil and Gas, Chemical and Petrochemical, Food and Beverage, Water and Wastewater, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Alternating Current (AC) Electric Drives Market Trends and Insights
Increasing Automation in Manufacturing Industries
Smart-factory investments accelerate the adoption of AC electric drives in the market because executives view energy-efficiency gains as decisive cost levers. ABB released the ACS8080 medium-voltage platform in November 2024, which runs at 98% efficiency while cutting harmonic distortion by 50%. Variable-speed retrofits on fans alone reduce electricity use by up to 30%, freeing up the budget for further automation upgrades. Real-time data transmitted from drives to plant historians supports predictive quality control and reduces unplanned downtime. Governments in China, India, and Indonesia incentivize robotics through tax credits, thereby broadening the addressable installed base for intelligent drives.
Rising Government Regulations and Demand for Efficient Devices
Minimum-energy-performance standards now govern roughly two-thirds of global motor shipments. The European Union's Eco-design Directive and the United States Department of Energy's rules require factories to demonstrate quantifiable savings, making AC electric drives' market penetration virtually mandatory in new build lines. The share of electric power in final energy consumption is projected to rise from 29% in 2022 to 52% by 2050, intensifying scrutiny of every motor-driven system. Utilities also reward demand-response participation, allowing facilities equipped with variable-speed drives to monetize flexible load capacity.
High Initial Installation and Maintenance Costs
Total installed cost includes engineering, harmonic-filter banks, cooling upgrades, and operator training, sometimes reaching 2-3X the drive list price. Smaller firms defer projects when payback exceeds two fiscal years. In retrofit scenarios, rewiring panels and verifying power-quality compliance further inflate budgets. Service teams must periodically replace DC-link capacitors and fan assemblies, creating unfamiliar lifecycle obligations for maintenance departments accustomed to simple starters.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of HVAC Installations in Commercial Buildings
- Declining Cost per Kilowatt of High-Power IGBT Modules
- Shortage of Skilled Technicians for Drive Programming and Tuning
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Low-voltage units captured the lion's share of 57.74% in 2025 because most industrial motors draw less than 690 V. However, project developers are consolidating loads, preferring one 4 MW motor over four 1 MW units to simplify maintenance. The AC electric drives market now observes medium-voltage quotations rising at a 7.52% CAGR through 2031, as petrochemical, desalination, and mining projects double down on multi-megawatt pumps. The ACS8080 release illustrates how higher power density and lower harmonics make these drives practical for brownfield sites. Regional oil refineries are adopting 6.6 kV VFDs to reduce steam-turbine auxiliary systems, thereby slashing process-heat emissions under net-zero roadmaps.
In the Asia-Pacific region, local panel builders package medium-voltage cabinets with ring-main units to meet turnkey EPC bids. European players differentiate through integral active-front-end converters that meet stringent grid-code flicker limits. Meanwhile, North American utilities are approving regenerative drive configurations that return braking energy to the network, thereby monetizing power quality improvements. These dynamics indicate an inflection point where medium-voltage penetration may displace low-voltage incumbents in power-hungry verticals by the decade's close.
Systems up to 1 MW still account for 47.10% of 2025 shipments, as OEMs in the food, beverage, and discrete manufacturing sectors typically specify standardized frames for conveyors and mixers. Yet, the AC electric drives market sees above-3 MW installations growing fastest at a 7.26% CAGR, as hydrogen electrolyzer plants, floating LNG vessels, and large-scale carbon-capture units demand precise control of giant compressors. Modern SiC inverters now exceed 7 kHz switching frequency at these ratings without requiring oversized air conditioning, allowing for indoor placement and reduced environmental sealing costs.
Original equipment manufacturers bundle 5 MW drives with active-magnetic-bearing compressors, eliminating lube-oil circuits and boosting plant uptime. In metals and mining, replacing hydraulic couplings with high-power variable-speed drives reduces mechanical stress during mill start-up, thereby extending gearbox life. Service providers capitalize on the ongoing digital transformation by offering cloud-delivered harmonic audits and software patches, making large-scale ownership less daunting for operators previously deterred by complexity.
Complete Report Scope:
- By Voltage
- Low Voltage
- Medium Voltage and Others
- By Power Rating
- Up to 1 MW
- 1 MW - 3 MW
- Above 3 MW
- By Application
- Pumps
- Fans
- Compressors
- Conveyors
- Extruders
- Other Application
- By End User Industry
- Oil and Gas
- Chemical and Petrochemical
- Food and Beverage
- Water and Wastewater
- Power Generation
- Metals and Mining
- Pulp and Paper
- HVAC
- Discrete Industries
- Other End User Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
The Asia-Pacific region captured 35.29% of the revenue in 2025, reflecting cross-sector industrialization and supportive government robotics schemes. China's dominance spans both production and consumption, with local brands cultivating mass-market offerings that shorten lead times. India's Production Linked Incentive scheme expands demand in cement, steel, and automotive verticals, while Japan champions power-device miniaturization, exporting technology modules to global OEMs.
North America and Europe remain mature yet dynamic. The U.S. Inflation Reduction Act offers tax credits that enhance internal rates of return for energy efficiency retrofits, solidifying the AC electric drives market as a key enabler of decarbonization pathways. European utilities implement dynamic grid-support tariffs that reward facilities that throttle motor loads in response to renewable energy intermittency. Consequently, buyers favor drives with regenerative and low-harmonic capabilities.
The Middle East is on a 6.62% CAGR trajectory, energized by mega-projects such as Saudi Arabia's NEOM and United Arab Emirates desalination complexes. Integrated petrochemical hubs specify multi-megawatt drives for ethylene crackers and seawater intake pumps. African and South American markets are gaining momentum through mining expansion and water infrastructure investments; however, adoption is tempered by financing constraints and limited after-sales service networks.
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Danfoss A/S
- Rockwell Automation Inc.
- WEG S.A.
- Yaskawa Electric Corporation
- Toshiba International Corporation
- Parker Hannifin Corporation
- Fuji Electric Co., Ltd.
- Mitsubishi Electric Corporation
- Hitachi, Ltd.
- Emerson Electric Co.
- Nidec Corporation
- Invertek Drives Ltd.
- Eaton Corporation plc
- Bonfiglioli Riduttori S.p.A.
- SEW-EURODRIVE GmbH and Co KG
- Lenze SE
- Nord Drivesystems Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Automation in Manufacturing Industries
- 4.2.2 Rising Government Regulations and Demand for Energy Efficient Devices
- 4.2.3 Rapid Expansion of HVAC Installations in Commercial Buildings
- 4.2.4 Declining Cost per Kilowatt of High-Power IGBT Modules
- 4.2.5 Surge in Variable Frequency Drive Retrofits in Aging Industrial Plants
- 4.2.6 Integration of AC Drives with IIoT Platforms for Predictive Maintenance
- 4.3 Market Restraints
- 4.3.1 High Initial Installation and Maintenance Costs
- 4.3.2 Harmonics and Power Quality Concerns Limiting Adoption
- 4.3.3 Shortage of Skilled Technicians for Drive Programming and Tuning
- 4.3.4 Supply Chain Volatility in Semiconductor Components Affecting Lead Times
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers/Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Voltage
- 5.1.1 Low Voltage
- 5.1.2 Medium Voltage and Others
- 5.2 By Power Rating
- 5.2.1 Up to 1 MW
- 5.2.2 1 MW - 3 MW
- 5.2.3 Above 3 MW
- 5.3 By Application
- 5.3.1 Pumps
- 5.3.2 Fans
- 5.3.3 Compressors
- 5.3.4 Conveyors
- 5.3.5 Extruders
- 5.3.6 Other Application
- 5.4 By End User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Food and Beverage
- 5.4.4 Water and Wastewater
- 5.4.5 Power Generation
- 5.4.6 Metals and Mining
- 5.4.7 Pulp and Paper
- 5.4.8 HVAC
- 5.4.9 Discrete Industries
- 5.4.10 Other End User Industry
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Schneider Electric SE
- 6.4.4 Danfoss A/S
- 6.4.5 Rockwell Automation Inc.
- 6.4.6 WEG S.A.
- 6.4.7 Yaskawa Electric Corporation
- 6.4.8 Toshiba International Corporation
- 6.4.9 Parker Hannifin Corporation
- 6.4.10 Fuji Electric Co., Ltd.
- 6.4.11 Mitsubishi Electric Corporation
- 6.4.12 Hitachi, Ltd.
- 6.4.13 Emerson Electric Co.
- 6.4.14 Nidec Corporation
- 6.4.15 Invertek Drives Ltd.
- 6.4.16 Eaton Corporation plc
- 6.4.17 Bonfiglioli Riduttori S.p.A.
- 6.4.18 SEW-EURODRIVE GmbH and Co KG
- 6.4.19 Lenze SE
- 6.4.20 Nord Drivesystems Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


