

|
시장보고서
상품코드
2125305
영국의 IT 서비스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom IT Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
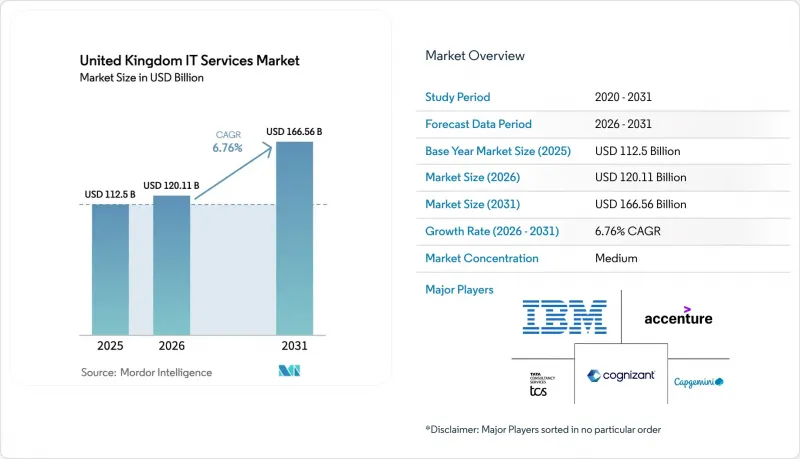
에 의하면, 영국의 IT 서비스 시장 규모는 2025년에 1,125억 달러로 평가되었습니다. 2026년 1,201억 1,000만 달러에서 2031년까지 1,665억 6,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.76%를 나타낼 전망입니다.
본 보고서는 서비스 유형(IT 컨설팅·도입, IT 아웃소싱, 비즈니스 프로세스 아웃소싱 등), 최종 사용자 기업 규모(중소기업, 대기업), 제공 모델(온쇼어 제공, 니어쇼어 제공 등), 최종 사용자 업종(은행, 금융서비스 및 보험(BFSI), 정부·공공 부문 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
영국의 IT 서비스 시장 동향 및 인사이트
AI 주도 디지털 전환의 물결
영국은 현재 세계 3위의 AI 경제 규모를 자랑하며, AI 도입을 통해 연간 1.5%의 생산성 향상을 목표로 하고 있습니다. 이러한 열의에도 불구하고, 충분한 AI 지식을 보유하고 있다고 응답한 제조업체는 고작 16%에 그치고 있어, 서비스 제공업체에게는 컨설팅 기회가 확대되고 있습니다. 40억 달러 규모의 공공 투자와 140억 달러 규모의 민간 투자 약속이 AI를 중심으로 한 프로젝트를 위한 견고한 파이프라인을 형성하고 있습니다. 액센츄어만 해도 2025 회계연도 2분기에 생성형 AI 관련 수주액으로 14억 달러를 확보하여 기업의 활발한 수요를 보여주었습니다. 옥스퍼드셔의 칼햄을 시작으로, 정부가 지정한 ‘AI 성장 구역’에서는 대규모 시스템 통합과 클라우드 용량이 필요합니다. 이러한 요인들이 맞물려 영국의 IT 서비스 시장에 지속적인 성장을 가져오고 있습니다.
‘클라우드 퍼스트’ 정부 조달 방침
G-Cloud 14 카탈로그에 4,000개 공급업체가 제공하는 4만 6,000건의 서비스가 등재되어 있는 것에서 알 수 있듯이, ‘클라우드 퍼스트’ 방침은 공공 부문의 조달 형태를 혁신하고 있습니다. 2012년 이후, 프레임워크 계약을 통해 23억 달러의 비용 절감 실적을 달성한 것은 그 경제적 이점을 입증함과 동시에 중소기업의 참여를 촉진하고 있습니다. 앞으로 실시될 160억 달러 규모의 ‘테크놀로지 서비스 4’ 경쟁은 벤더들에게 가장 큰 단일 비즈니스 기회가 될 것입니다. 클라우드 도입은 ‘디지털 기술 부문 계획’에 기반한 전략적 파트너십으로까지 확대되어, 조달과 혁신의 경계를 모호하게 만들고 있습니다. 규제 산업이 공공 부문의 기준을 모방함에 따라 민간 부문으로의 파급 효과가 두드러지고 있으며, 이는 영국의 IT 서비스 시장 전체에서 플랫폼 서비스의 두 자릿수 성장을 뒷받침하고 있습니다.
IT 인재 시장의 높은 임금 인플레이션
2024년, 기술 분야의 급여는 7-10% 상승했으며, 고용주의 76%가 심각한 기술 인력 부족을 지적했습니다. 2025년 4월 국민보험료율이 13.8%에서 15%로 인상됨에 따라 고용주의 비용이 증가할 전망입니다. 브렉시트 이후 EU 출신 전문가 30만 명이 이직함에 따라 60만 개의 일자리가 공석으로 남아, 경제에 연간 630억 달러의 손실을 초래하고 있습니다. 기업들은 니어쇼어 전략 및 자동화 전략 확대를 통해 이러한 부족분을 메우고 있지만, 인건비 급등이 이익률을 압박하며 영국의 IT 서비스 시장의 성장을 둔화시키고 있습니다.
부문별 분석
2025년, 클라우드 플랫폼 서비스는 영국 IT 서비스 시장 점유율의 28.15%를 차지하며, G-Cloud 14에 따른 카탈로그 확충과 레거시 시스템에서 퍼블릭 클라우드로의 지속적인 전환에 힘입어 주도적인 위치를 확립했습니다. 이 부문에서 영국의 IT 서비스 시장 규모는 160억 달러 규모의 ‘Technology Services 4’ 프레임워크를 배경으로 꾸준히 확대될 것으로 예측됩니다. 동시에, 매니지드 보안 서비스는 ‘사이버 보안 복원력 법안’에 따른 규정 준수 의무를 반영하여 2031년까지 연평균 성장률(CAGR) 9.38%를 나타낼 것으로 예측됩니다. IT 컨설팅은 기업용 AI 프로그램 덕분에 견조한 모습을 유지하고 있는 반면, IT 아웃소싱 및 BPO는 자동화가 진행됨에 따라 균형 잡힌 성장을 보이고 있습니다.
클라우드 전환과 보안 강화의 시너지 효과가 공급업체의 매출 확대를 뒷받침하고 있습니다. 기관들이 On-Premise 시스템을 대체함에 따라, 플랫폼 계약에 매니지드 보안 번들 계약이 결합되면서 시장 점유율이 확대되고 있습니다. 14억 달러 규모의 NHS 입찰은 해당 부문 고유의 프레임워크가 생태계 공급업체를 견인하는 모습을 여실히 보여주고 있습니다. 따라서 영국의 IT 서비스 시장에서는 하이퍼스케일 노하우와 제로 트러스트 아키텍처를 결합한 벤더가 우위를 점하고 있습니다.
2025년, 영국의 IT 서비스 시장 규모의 64.25%를 대기업이 차지했으며, 막대한 예산을 투입해 멀티클라우드 도입, 생성형 AI 시범 도입, 규제 대응 현대화를 추진했습니다. 지배적인 위치를 차지하고 있는 기업들의 경우, 변혁 로드맵이 성숙해짐에 따라 성장률은 완만해지고 있습니다. 대조적으로, 중소기업 부문은 ‘중소기업 디지털 도입 태스크포스’의 10단계 행동 계획에 힘입어 2031년까지 연평균 성장률(CAGR) 8.98%로 확대될 것으로 예측됩니다. 중소기업 부문에서 영국의 IT 서비스 시장 점유율은 여전히 소규모이지만, AI를 활용한 생산성 향상을 통해 창출될 수 있는 781억 달러 규모의 경제적 가치는 유망한 목표 시장을 형성하고 있습니다.
서비스 모델은 판매 주기의 단축과 중소기업이 선호하는 성과 기반 가격 책정에 대응할 필요가 있습니다. 지역 AI 혁신 허브, 세액 공제, 클라우드 마켓플레이스를 통해 진입 장벽이 낮아지면서, 공급업체들은 재현 가능한 패키지를 개발할 수 있게 되었습니다. 이에 따라 영국의 IT 서비스 시장에서는 런던 이외 지역의 초소규모 기업을 위해 맞춤화된 구독형 솔루션이 증가하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the UK IT services market size was valued at USD 112.5 billion in 2025 and estimated to grow from USD 120.11 billion in 2026 to reach USD 166.56 billion by 2031, at a CAGR of 6.76% during the forecast period (2026-2031).
This report is Segmented by Service Type (IT Consulting and Implementation, IT Outsourcing, Business Process Outsourcing, and More), End-User Enterprise Size (Small and Medium Enterprises, and Large Enterprises), Deployment Model (Onshore Delivery, Nearshore Delivery, and More), and End-User Vertical (BFSI, Government and Public Sector, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom IT Services Market Trends and Insights
AI-led Digital Transformation Wave
The United Kingdom now ranks as the world's third-largest AI economy and is targeting annual productivity gains of 1.5% through AI deployment. Despite enthusiasm, only 16% of manufacturers report adequate AI knowledge, opening consultative opportunities for service providers. Public investment of USD 4 billion and USD 14 billion in private commitments form a durable pipeline for AI-centric engagements. Accenture alone secured USD 1.4 billion in generative-AI bookings during Q2 FY25, signaling robust enterprise appetite. Government-designated AI Growth Zones-beginning with Culham, Oxfordshire-will require extensive systems integration and cloud capacity. Together, these factors generate a sustained uplift in the UK IT services market.
Cloud-first Government Procurement Policies
The cloud-first mandate, highlighted by G-Cloud 14's catalog of 46,000 services from 4,000 suppliers, is reshaping public-sector procurement. Framework savings of USD 2.3 billion since 2012 validate economic benefits and stimulate SME participation. The forthcoming USD 16 billion Technology Services 4 competition represents the largest single opportunity for vendors. Cloud uptake extends into strategic partnerships under the Digital and Technologies Sector Plan, blurring lines between procurement and innovation. Private-sector spillovers are visible as regulated industries replicate public-sector standards, reinforcing double-digit growth in platform services across the UK IT services market.
High Wage Inflation in Tech Talent Pool
Tech salaries escalated 7-10% in 2024, with 76% of employers citing acute skill shortages. The April 2025 National Insurance hike from 13.8% to 15% inflate employer costs. Post-Brexit workforce attrition of 300,000 EU professionals leaves 600,000 vacancies that cost the economy USD 63 billion annually. Firms offset gaps by expanding nearshore and automation strategies, yet elevated labor costs compress margins and temper growth in the UK IT services market.
Other drivers and restraints analyzed in the detailed report include:
- Acute Cyber-threat Environment
- Convergence of OT-IT in UK Manufacturing
- Near-term Macroeconomic Slowdown
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud and platform services represented 28.15% of the UK IT services market share in 2025, a leadership position supported by G-Cloud 14's widened catalog and ongoing migration of legacy estates to the public cloud. The UK IT services market size for this segment is projected to compound steadily on the back of the USD 16 billion Technology Services 4 framework. Simultaneously, managed security services are forecast to post a 9.38% CAGR to 2031, reflecting mandatory compliance under the Cyber Security and Resilience Bill. IT consulting remains resilient thanks to enterprise AI programs, while IT outsourcing and BPO experience balanced growth amid automation.
Cross-pollination between cloud migration and security hardening underpins provider revenue expansion. As agencies replace on-premise systems, bundled managed-security contracts accompany platform deals, magnifying wallet share. NHS tenders worth USD 1.4 billion illustrate how sector-specific frameworks pull along ecosystem suppliers. The UK IT services market, therefore, rewards vendors that combine hyperscale know-how with zero-trust architectures.
Large enterprises controlled 64.25% of the UK IT services market size in 2025, leveraging substantial budgets for multi-cloud rollouts, generative-AI pilots, and regulatory modernization. Despite dominance, their growth rate moderates as transformation roadmaps mature. In contrast, the SME cohort is projected to expand at a 8.98% CAGR to 2031, propelled by the SME Digital Adoption Taskforce's 10-step action plan. UK IT services market share among SMEs remains modest, yet the economic value potential-USD 78.1 billion in AI-enabled productivity gains-creates a fertile addressable base.
Service models must adjust to shorter sales cycles and outcome-based pricing preferred by smaller firms. Regional AI innovation hubs, tax credits, and cloud marketplaces lower entry barriers, allowing providers to develop repeatable packages. Accordingly, the UK IT services market is witnessing a rise in subscription-oriented solutions tailored to micro-enterprises outside London.
Complete Report Scope:
- By Service Type
- IT Consulting and Implementation
- IT Outsourcing (ITO)
- Business Process Outsourcing (BPO)
- Managed Security Services
- Cloud and Platform Services
- By End-User Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Deployment Model
- Onshore Delivery
- Nearshore Delivery
- Offshore Delivery
- By End-user Vertical
- BFSI
- Manufacturing
- Government and Public Sector
- Healthcare and Life-Sciences
- Retail and Consumer Goods
- Telecom and Media
- Logistics and Transport
- Energy and Utilities
- Other End-user Verticals
List of Companies Covered in this Report:
- Accenture plc
- IBM UK Ltd.
- Capgemini SE
- Tata Consultancy Services (TCS) UK
- Infosys Ltd. UK
- Cognizant Technology Solutions UK
- HCL Technologies UK
- Wipro Ltd. UK
- Fujitsu Services Ltd.
- DXC Technology UK
- CGI IT UK Ltd.
- Sopra Steria Ltd.
- Computacenter plc
- Softcat plc
- Kainos Group plc
- BJSS Ltd.
- Endava plc
- Version 1 Software UK Ltd.
- FDM Group plc
- PA Consulting Group
- Civica Ltd.
- NTT DATA UK Ltd.
- Capita IT Services
- Rackspace Technology UK
- Mastek (UK) Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-led Digital Transformation Wave
- 4.2.2 Cloud-first Government Procurement Policies
- 4.2.3 Acute Cyber-threat Environment
- 4.2.4 Convergence of OT-IT in UK Manufacturing
- 4.2.5 Rise of Green-IT Mandates (Sustainability Targets)
- 4.2.6 Brexit-Driven Regulatory Complexity
- 4.3 Market Restraints
- 4.3.1 High Wage Inflation in Tech Talent Pool
- 4.3.2 Near-term Macroeconomic Slowdown
- 4.3.3 Data-Sovereignty Concerns with Offshore Delivery
- 4.3.4 Fragmented SME Adoption Outside London
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Evaluation of Critical Regulatory Framework
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Competitive Rivalry
- 4.8.2 Threat of New Entrants
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Bargaining Power of Buyers
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 IT Consulting and Implementation
- 5.1.2 IT Outsourcing (ITO)
- 5.1.3 Business Process Outsourcing (BPO)
- 5.1.4 Managed Security Services
- 5.1.5 Cloud and Platform Services
- 5.2 By End-User Enterprise Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 Onshore Delivery
- 5.3.2 Nearshore Delivery
- 5.3.3 Offshore Delivery
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 Manufacturing
- 5.4.3 Government and Public Sector
- 5.4.4 Healthcare and Life-Sciences
- 5.4.5 Retail and Consumer Goods
- 5.4.6 Telecom and Media
- 5.4.7 Logistics and Transport
- 5.4.8 Energy and Utilities
- 5.4.9 Other End-user Verticals
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 IBM UK Ltd.
- 6.4.3 Capgemini SE
- 6.4.4 Tata Consultancy Services (TCS) UK
- 6.4.5 Infosys Ltd. UK
- 6.4.6 Cognizant Technology Solutions UK
- 6.4.7 HCL Technologies UK
- 6.4.8 Wipro Ltd. UK
- 6.4.9 Fujitsu Services Ltd.
- 6.4.10 DXC Technology UK
- 6.4.11 CGI IT UK Ltd.
- 6.4.12 Sopra Steria Ltd.
- 6.4.13 Computacenter plc
- 6.4.14 Softcat plc
- 6.4.15 Kainos Group plc
- 6.4.16 BJSS Ltd.
- 6.4.17 Endava plc
- 6.4.18 Version 1 Software UK Ltd.
- 6.4.19 FDM Group plc
- 6.4.20 PA Consulting Group
- 6.4.21 Civica Ltd.
- 6.4.22 NTT DATA UK Ltd.
- 6.4.23 Capita IT Services
- 6.4.24 Rackspace Technology UK
- 6.4.25 Mastek (UK) Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


