

|
시장보고서
상품코드
2125322
라벨 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Label - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
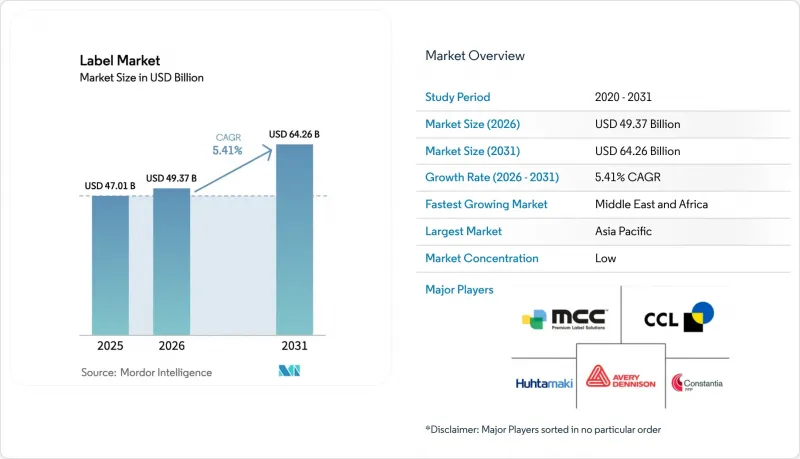
에 의하면, 라벨 시장 규모는 2025년 470억 1,000만 달러로 평가되었고, 2026년에는 493억 7,000만 달러로 추정되고, 2031년까지 642억 6,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 5.41%로 성장할 전망입니다.
본 보고서는 유형별(감압형, 수축형, 인몰드형 등), 소재별(종이, 폴리프로필렌, 폴리에틸렌, 폴리에틸렌 테레프탈레이트, 기타 소재), 인쇄 기술별(플렉소 인쇄, 오프셋 인쇄, 그라비아 인쇄 등), 최종 사용자 산업별(식품, 음료, 헬스케어 및 제약, 화장품 및 퍼스널케어 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 라벨 시장 동향 및 인사이트
전자상거래의 급속한 성장이 가변 데이터 배송 라벨 시장을 견인
2024년, 전 세계 소포 처리량은 210억 개를 돌파했으나, 여전히 모든 상자에는 최소 1개의 스캔 가능한 식별자가 필요합니다. 각 컨버터 업체들은 분당 100미터 이상의 속도로 고유한 바코드를 인쇄할 수 있는 고속 디지털 잉크젯 인쇄기를 도입하여 이에 대응하고 있으며, 이를 통해 플래시 세일을 진행하는 소매업체의 당일 발송이 가능해졌습니다. 의약품 콜드체인 물류는 온도 표시 라벨에 미국 ‘의약품 공급망 보안법’에서 의무화한 로트 번호 및 유효 기간 코드도 기재해야 하기 때문에 더욱 복잡해지고 있습니다. 유럽연합(EU)으로 반입되는 국경 간 소포에는 2025년에 시행될 ‘포장 및 포장 폐기물 규정’에 따라 도입되는 디지털 제품 여권과 연결된 QR 코드를 표시해야 합니다. 디지털 대응 능력이 부족한 컨버터는 소량 생산 및 가변 데이터 인쇄에 이미 적응한 기동력 있는 경쟁사들에게 시장 점유율을 빼앗길 위험이 있습니다.
지속가능성 관련 규제가 라이너가 없는 재활용 가능한 형태의 도입을 가속화
유럽연합(EU)은 현재 2030년까지 모든 포장재를 재활용 가능하게 할 것을 의무화하고 있으며, 같은 해까지 병에 30%의 rPET(재생 PET 병)을 사용하도록 의무화하고 있습니다. 이러한 규제로 인해 라벨 시장에 진입한 기업들은 실리콘 코팅된 박리 라이너를 배제하는 물로 씻어낼 수 있는 접착제나 라이너리스 구조를 채택해야 하는 상황에 처해 있습니다. UPM Raflatac의 ‘RafCycle’ 네트워크는 최근 폴란드와 태국으로 확대되어 연간 약 1만 메트르톤의 라이너 폐기물을 재활용하고 있습니다. 캘리포니아주와 오리건주에서 생산자 책임 확대법이 도입됨에 따라 북미에서도 유사한 프로그램이 등장하고 있습니다. 또한, 브랜드 소유주들은 식품 접촉 라벨에서의 PFAS 사용 금지 조치에 직면하고 있으며, 이에 따라 각 변환업체들은 ISO 14021 인증을 획득한 불소 무함유 코팅에 대한 투자를 확대되고 있습니다.
필름 및 접착제 원자재 비용의 변동
2025년, 원유 가격 변동과 아시아태평양 석유화학 거점에서공급 차질이 각 컨버터 업체를 불안에 빠뜨렸기 때문에 폴리프로필렌 필름의 거래 가격은 톤당 1,200-1,600달러 사이에서 등락했습니다. 아크릴 에멀젼용 접착제 수지 가격은 전년 대비 12% 상승하여, 중규모 컨버터의 평균 EBITDA 마진이 불과 8-12%에 그치는 상황에서 이익률을 압박했습니다. 소비재를 취급하는 다국적 기업과의 고정 가격 계약으로 인해 원가 전가가 제한되고 있어, 각 컨버터 업체들은 다년간 공급 계약 협상을 진행하거나 수지 소비량을 줄이는 무용제 기술에 투자할 수밖에 없는 상황입니다. 재활용 PET 수지 역시 유사한 가격 변동에 직면하고 있으며, 이는 유럽의 rPET 30% 의무화에 따른 병 플레이크 공급 부족을 반영한 것입니다. 필름 압출 공정으로의 수직 통합이 진행되지 않은 중소규모 컨버터는 이러한 투입 비용의 급격한 변동에 가장 큰 영향을 받고 있습니다.
부문 분석
수축 라벨은 2031년까지 연평균 성장률(CAGR) 6.25%로 성장하여 라벨 시장 전체를 상회할 것으로 예측됩니다. 이러한 인기는 브랜딩, 규제 문구, 부정 개봉 방지 기능을 하나의 슬리브에 통합한 360도 장식에서 비롯됩니다. 감압형 라벨은 다양한 기판에 대한 적응성과 분당 500개 이상의 고속 부착 속도 덕분에 2025년에도 여전히 라벨 시장 점유율의 47.44%를 차지했습니다. 랩어라운드 라벨은 여전히 주류인 탄산음료에 널리 채택되고 있지만, 레이저 조각 및 직접 프린팅을 통한 솔루션으로의 시험적인 대체가 진행되고 있습니다. 인몰드 라벨은 블로우 성형 공정 중에 장식을 통합함으로써 유제품 용기나 아이스크림 용기의 제조 효율을 높이고, 후속 공정의 한 단계를 생략합니다. 접착제 도포형이나 열전사형과 같은 소규모 카테고리는 유리병의 고급스러움이나 산업용 제품의 내구성이 소재 선택의 결정 요인이 되는 분야에서 여전히 자리를 지키고 있습니다. 수축 슬리브는 저밀도 PET-G·PP 필름이 현재 재활용 시설에서 깨끗하게 분리될 수 있게 됨에 따라 순환 경제에 대한 우려가 해소되어, 앞으로도 시장 점유율을 계속 확대해 나갈 것입니다.
각 컨버터 업체들은 의약품, 물류, 화학약품용 드럼통의 경우 계속해서 점착 라벨을 우선시할 것입니다. 이는 엄격한 세척 요건과 가변 데이터에 대한 요구가 이 포맷의 모듈식 구조와 부합하기 때문입니다. 그러나 수축 슬리브의 롤 폭 확대와 자동 시밍 장치의 보급으로 단위당 비용이 절감됨에 따라, 음료 브랜드들은 기존에 랩어라운드 필름을 사용하던 SKU를 수축 슬리브로 전환하는 경향을 보이고 있습니다. 고급 제품 시장에서는 메탈릭 액센트가 가미된 다층 열전사 라벨이 질감을 통한 차별화를 중시하는 크래프트 증류주 시장에서 점유율을 유지하고 있습니다. 전반적으로 이 유형의 부문은 성능, 재활용성, 진열 효과 및 비용이 상쇄되는 용도에 따른 절충점을 고려해야 할 대상으로 남아 있습니다.
PET 필름의 매출액은 브랜드 소유자의 노력과 규제에 따른 할당으로 인해 rPET 호환 페이스 스톡 수요가 증가함에 따라, 2031년까지 연평균 성장률(CAGR) 6.72%를 나타낼 것으로 예측됩니다. 폴리프로필렌은 낮은 밀도와 투명성으로 인해 수축 슬리브와 인몰드 라벨을 모두 지원하며, 운송 비용 절감과 광학적 품질을 제공하기 때문에 2025년에는 시장 점유율의 36.77%를 차지했습니다. 종이는 질감이 살아있는 FSC 인증 소재가 진정성을 자아내는 프리미엄 와인 및 크래프트 맥주 최종 시장에서 여전히 중요한 위치를 차지하고 있습니다. 폴리에틸렌은 영하에서도 유연성을 유지할 수 있어 냉동 식품 및 스퀴즈 병에 필수적인 소재로 남아 있습니다. PVC나 PLA와 같은 기타 폴리머는 틈새 용도로 사용됩니다. PVC는 사용 후 처리 문제가 있음에도 불구하고 음료 멀티팩에 여전히 사용되고 있는 반면, PLA 필름은 산업용 퇴비화가 가능한 지역에서 퇴비화 가능한 포장에 대한 기대에 부응하고 있습니다.
2030년까지 병에 30%의 rPET 사용을 의무화하는 유럽의 ‘포장 및 포장 폐기물 규정’에 따라, 각 컨버터 기업들은 병 플레이크 공급 계약을 통해 원료 확보에 나서야 하는 상황에 놓여 있습니다. UPM Raflatac과 Avery Dennison은 2024-2025년 rPET 필름의 생산 능력을 확대하며, 수요의 지속성에 대한 확신을 보여주고 있습니다. 단일 소재인 폴리프로필렌 구조의 발전으로 인해, 표면재, 접착제, 오버라미네이트를 PP 계열 소재 내에서 통일함으로써, 소재를 분리하지 않고도 재활용성을 확보하고 있습니다. 한편, 종이의 전망이 정체된 것은 습기에 대한 취약성을 반영한 것이지만, 고급 주류 분야에서는 진열 시 어필력을 높이기 위해 호일 스탬핑이나 촉감 니스 처리로 강화된 펄프 기반 표면재가 여전히 지정되고 있습니다.
지역별 분석
아시아태평양은 2025년에 40.14%의 시장 점유율을 유지했으며, 세계 소비재 제조의 핵심으로서의 위상을 강조했습니다. 중국의 소포 배송 네트워크는 2024년에 1,300억 건을 넘어섰으며, 이 하나하나가 가변 데이터 물류 라벨 수요를 견인하고 있습니다. 인도에서 미국으로의 의약품 수출에는 ‘의약품 공급망 안보법(DSSA)’을 준수하는 일련번호 라벨이 필수입니다. 한편, 일본은 브랜드의 진위성을 확인하고 고객 참여를 확대하는 NFC 지원 라벨 도입을 선도하고 있습니다. 한국의 화장품 수출업체들은 고급스러운 마감 처리에 대한 수요를 주도하고 있으며, 호주의 엄격한 식품 안전 기준으로 인해 신선식품 공급망 전반에 걸쳐 내습성 접착제가 요구되고 있습니다. 동남아시아의 성장은 라이너 폐기물 재활용이 제한적이라는 점으로 인해 제약을 받고 있지만, 해당 지역 각국 정부는 향후 10년 동안 회수율을 향상시킬 EPR(확대 생산자 책임) 법안 초안을 마련 중입니다.
중동 및 아프리카는 현대적인 소매업과 인프라 투자의 뒷받침을 받아 2031년까지 연평균 성장률(CAGR) 7.11%라는 가장 높은 성장률을 보일 것으로 전망됩니다. 아랍에미리트(UAE)와 사우디아라비아는 콜드체인 용량 확장을 지속하고 있어, 저온 내성이 있는 점착 라벨의 수주를 촉진하고 있습니다. 튀르키예는 유럽에 인접한 제조 거점으로서의 위상을 확립하여, 니어쇼어 공급을 목표로 하는 다국적 컨버터 기업들을 유치하고 있습니다. 남아프리카공화국은 사하라 이남 아프리카 전역에 음료, 의약품, 가정용품을 위한 라벨을 공급하고 있는 반면, 나이지리아에서는 도시 중산층의 확대에 따라 포장 상품의 판매량이 급증하고 있습니다. 미비한 인프라와 환율 리스크가 존재하지만, GS1 바코드 규격 및 영양 표시 기준과의 조화를 통해 라벨 시장의 지속적인 확대가 예상됩니다.
북미와 유럽은 양적 성장의 원동력이라기보다는 여전히 혁신의 중심지로서의 지위를 유지하고 있습니다. 미국에서는 FSMA 제204조에 따라 고위험 식품의 추적 가능성이 의무화되어 있으며, QR 코드가 내장된 라벨의 도입이 촉진되고 있습니다. 동시에, 주 차원의 EPR(생산자 책임 회수) 제도에 따라 사용 후 제품 처리 비용이 브랜드 소유자에게 전가됨에 따라, 폐기물량을 줄이는 라이너리스(linerless) 형식에 대한 수요가 증가하고 있습니다. 유럽의 ‘포장 및 포장 폐기물 규정’은 2030년까지 재활용 가능한 포장 사용을 의무화하고 rPET 사용 기준을 단계적으로 상향 조정하고 있으며, 이에 따라 가공업체들은 씻어낼 수 있는 접착제나 종이를 사용하지 않는 라이너리스 구조의 시범 도입을 촉진하고 있습니다. 남미에서는 브라질과 아르헨티나를 중심으로 음료 및 대두 기반 식품의 수출에 힘입어 한 자릿수 중반대의 성장이 예상되지만, 거시경제의 변동으로 인해 예측의 불확실성이 높아지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the label market size is expected to increase from USD 47.01 billion in 2025 to USD 49.37 billion in 2026 and reach USD 64.26 billion by 2031, growing at a CAGR of 5.41% over 2026-2031.
This report is Segmented by Type (Pressure-Sensitive, Shrink, In-Mold, and More), Material (Paper, Polypropylene, Polyethylene, Polyethylene-Terephthalate And, Other Materials), Print Technology (Flexographic, Offset, Gravure, and More), End-User Industry (Food, Beverage, Healthcare and Pharmaceutical, Cosmetics and Personal Care, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Label Market Trends and Insights
E-commerce Boom Driving Variable-Data Shipping Labels
Global parcel volumes surpassed 21 billion units in 2024, and every box still needs at least one scannable identifier. Converters are responding with high-speed digital inkjet presses that print unique barcodes above 100 meters per minute, enabling same-day fulfillment for flash-sale retailers. Pharmaceutical cold-chain logistics adds complexity because temperature-indicator labels must also carry batch and expiry codes required by the U.S. Drug Supply Chain Security Act. Cross-border parcels entering the European Union must display QR codes linked to digital product passports introduced under the Packaging and Packaging Waste Regulation in 2025. Converters lacking digital capacity risk share loss to agile peers already scaled for short runs and variable data.
Sustainability Regulations Accelerating Liner-less and Recyclable Formats
The European Union now requires all packaging to be recyclable by 2030 and mandates 30% rPET in bottles by the same year. These rules push label market participants to adopt wash-off adhesives and liner-less constructions that remove silicone-coated release liners. UPM Raflatac's RafCycle network, recently expanded to Poland and Thailand, diverts about 10 000 metric tons of liner waste annually. Similar programs are emerging in North America as extended producer responsibility laws roll out in California and Oregon. Brand owners also face PFAS bans in food-contact labels, prompting converters to invest in fluorine-free coatings certified under ISO 14021.
Raw-Material Cost Volatility in Films and Adhesives
Polypropylene film traded between USD 1 200-1 600 per metric ton during 2025 as crude-oil swings and supply outages in Asia-Pacific petrochemical hubs unsettled converters. Adhesive-resin prices for acrylic emulsions climbed 12% year on year, eroding EBITDA margins that average just 8-12% for mid-sized converters. Locked-price contracts with consumer-goods multinationals limit cost-pass-through, forcing converters to negotiate multi-year supply deals or invest in solvent-free technologies that reduce resin consumption. Recycled PET resin faced similar volatility, reflecting tight bottle-flake supplies under Europe's 30% rPET mandate. Smaller converters, lacking vertical integration into film extrusion, carry the most exposure to these input shocks.
Other drivers and restraints analyzed in the detailed report include:
- Smart and Connected Packaging Unlocking New Revenue Streams
- Food and Beverage Demand for Premium Compliance-Driven Packaging
- Shift Toward Stand-Up Pouches and Direct-to-Object Printing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Shrink labels are forecast to grow at a 6.25% CAGR through 2031, outstripping the overall label market. Their popularity stems from 360-degree decoration that merges branding, regulatory text, and tamper evidence in one sleeve. Pressure-sensitive formats still held 47.44% of the label market share in 2025 thanks to versatility across substrates and rapid application speeds that exceed 500 units per minute. Wrap-around labels remain endemic to mainstream carbonated drinks but face pilot replacements by laser-etched or direct-print solutions. In-mold labels add process efficiency in dairy tubs and ice-cream containers by integrating decoration during blow molding, cutting a full downstream step. Smaller categories such as glue-applied and heat-transfer styles survive where glass-bottle prestige or industrial durability governs material choice. Shrink sleeves will keep gaining because low-density PET-G and PP films now separate cleanly at recycling plants, addressing circularity concerns.
Converters will still prioritize pressure-sensitive labels for pharmaceuticals, logistics, and chemical drums because stringent wash-off and variable-data needs align with that format's modular construction. However, wider shrink-sleeve roll widths and automated seaming equipment have reduced per-unit costs, encouraging beverage brands to migrate SKUs that historically used wrap-around film. At the premium end, multi-layer heat-transfer labels with metallic accents are defending share in craft spirits that value tactile differentiation. Overall, the type segment remains a study in application-specific trade-offs where performance, recyclability, and shelf impact counterbalance cost.
PET film sales are projected to grow at a 6.72% CAGR through 2031 as brand-owner commitments and regulatory quotas boost demand for rPET-ready facestocks. Polypropylene accounted for 36.77% of the market share in 2025 because of its low density and clarity, which support both shrink sleeves and in-mold labels, offering freight savings and optical quality. Paper maintains relevance in premium wine and craft-beer end-markets where textured, FSC-certified stocks evoke authenticity. Polyethylene remains indispensable for frozen foods and squeeze bottles due to its flexibility at sub-zero temperatures. Other polymers, such as PVC and PLA, have niche applications: PVC persists in beverage multipacks despite end-of-life challenges, while PLA films meet compostable-pack aspirations where industrial composting is available.
The European Packaging and Packaging Waste Regulation that enforces 30% rPET in bottles by 2030 drives converters to secure feedstock via bottle-flake supply contracts. UPM Raflatac and Avery Dennison expanded rPET film capacity in 2024-2025, signaling confidence in demand durability. Advances in mono-material polypropylene structures, aligning facestock, adhesive, and over-laminate within PP families, address circularity without material separation. Conversely, paper's flat outlook reflects vulnerability to moisture, yet premium spirits still specify pulp-based facestocks enhanced with foil stamping and tactile varnishes for shelf appeal.
Complete Report Scope:
- By Type
- Pressure-Sensitive Labels
- Shrink Labels
- In-Mold Labels
- Wrap-Around Labels
- Other Types
- By Material
- Paper
- Polypropylene (PP)
- Polyethylene (PE)
- Polyethylene-Terephthalate (PET)
- Other Materials
- By Print Technology
- Flexographic Printing
- Offset Printing
- Gravure Printing
- Digital Inkjet Printing
- Other Printing Technologies
- By End-User Industry
- Food
- Beverage
- Healthcare and Pharmaceutical
- Cosmetics and Personal Care
- Chemicals and Industrial
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Turkey
- Saudi Arabia
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific retained 40.14% market share in 2025, underscoring its position as the manufacturing nucleus for global consumer goods. China's parcel-delivery network exceeded 130 billion shipments in 2024, each driving a variable-data logistics label. India's pharmaceutical exports to the United States necessitate serialized labels compliant with the Drug Supply Chain Security Act, while Japan pioneers NFC-enabled labels that verify brand authenticity and extend customer engagement. South Korea's cosmetics exporters fuel demand for premium finishes, and Australia's strict food-safety codes require moisture-resistant adhesives across fresh-produce supply chains. Growth in Southeast Asia is checked by limited liner-waste recycling, yet regional governments are drafting EPR laws that will raise collection rates over the next decade.
The Middle East and Africa is positioned for the fastest 7.11% CAGR to 2031, spurred by modern retail and infrastructure investments. The United Arab Emirates and Saudi Arabia continue building cold-chain capacity, triggering orders for low-temperature-tolerant pressure-sensitive labels. Turkey's status as a Europe-facing manufacturing hub is attracting multinational converters aiming for near-shore supply. South Africa supplies beverage, pharmaceutical, and household-care labels across sub-Saharan Africa, while Nigeria's urban middle class is swelling packaged-goods volumes. Despite infrastructure gaps and currency risks, harmonization with GS1 barcoding and nutrition labelling standards points to sustained label market expansion.
North America and Europe remain innovation centers rather than volume growth engines. The United States enforces traceability for high-risk foods under FSMA Section 204, pushing adoption of QR-embedded labels. Simultaneously, state-level EPR schemes shift end-of-life costs to brand owners, lifting demand for liner-less formats that lower waste tonnage. Europe's Packaging and Packaging Waste Regulation obliges recyclable packaging by 2030 and sets progressive rPET thresholds, encouraging converters to pilot wash-off adhesives and paper-free liner-less constructions. South America, led by Brazil and Argentina, experiences middle-single-digit growth paced by beverage and soy-based food exports, although macroeconomic volatility adds forecasting uncertainty.
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Huhtamaki Oyj
- Constantia Flexibles GmbH
- UPM Raflatac (UPM Group)
- Mondi plc
- Fuji Seal International Inc.
- Fort Dearborn Company
- Lintec Corporation
- 3M Company
- Smurfit Westrock
- Amcor plc
- Taghleef Industries
- Stora Enso Oyj
- Xeikon BV
- KRIS Flexipacks Pvt Ltd
- Royal Sens Group
- Leading Edge Labels and Packaging
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce Boom Driving Variable-Data Shipping Labels
- 4.2.2 Sustainability Regulations Accelerating Liner-less and Recyclable Formats
- 4.2.3 Food and Beverage Demand for Premium Compliance-Driven Packaging
- 4.2.4 Smart and Connected Packaging Unlocking New Revenue Streams
- 4.2.5 EV Battery-Safety Mandates Spurring High-Spec Pressure-Sensitive Labels
- 4.2.6 ASEAN Label-Free Bottle Pilots Catalyzing Direct-to-Container Printing
- 4.3 Market Restraints
- 4.3.1 Raw-Material Cost Volatility in Films and Adhesives
- 4.3.2 Shift Toward Stand-Up Pouches and Direct-to-Object Printing
- 4.3.3 Limited Global Liner-Waste Recycling Infrastructure
- 4.3.4 Emerging Label-Free Bottle Regulations Reducing Wrap-Around Demand
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Pressure-Sensitive Labels
- 5.1.2 Shrink Labels
- 5.1.3 In-Mold Labels
- 5.1.4 Wrap-Around Labels
- 5.1.5 Other Types
- 5.2 By Material
- 5.2.1 Paper
- 5.2.2 Polypropylene (PP)
- 5.2.3 Polyethylene (PE)
- 5.2.4 Polyethylene-Terephthalate (PET)
- 5.2.5 Other Materials
- 5.3 By Print Technology
- 5.3.1 Flexographic Printing
- 5.3.2 Offset Printing
- 5.3.3 Gravure Printing
- 5.3.4 Digital Inkjet Printing
- 5.3.5 Other Printing Technologies
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Healthcare and Pharmaceutical
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Chemicals and Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Turkey
- 5.5.5.1.3 Saudi Arabia
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 CCL Industries Inc.
- 6.4.2 Avery Dennison Corporation
- 6.4.3 Multi-Color Corporation
- 6.4.4 Huhtamaki Oyj
- 6.4.5 Constantia Flexibles GmbH
- 6.4.6 UPM Raflatac (UPM Group)
- 6.4.7 Mondi plc
- 6.4.8 Fuji Seal International Inc.
- 6.4.9 Fort Dearborn Company
- 6.4.10 Lintec Corporation
- 6.4.11 3M Company
- 6.4.12 Smurfit Westrock
- 6.4.13 Amcor plc
- 6.4.14 Taghleef Industries
- 6.4.15 Stora Enso Oyj
- 6.4.16 Xeikon BV
- 6.4.17 KRIS Flexipacks Pvt Ltd
- 6.4.18 Royal Sens Group
- 6.4.19 Leading Edge Labels and Packaging
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


