

|
시장보고서
상품코드
2125467
필리핀의 의약품 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Philippines Pharmaceutical Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
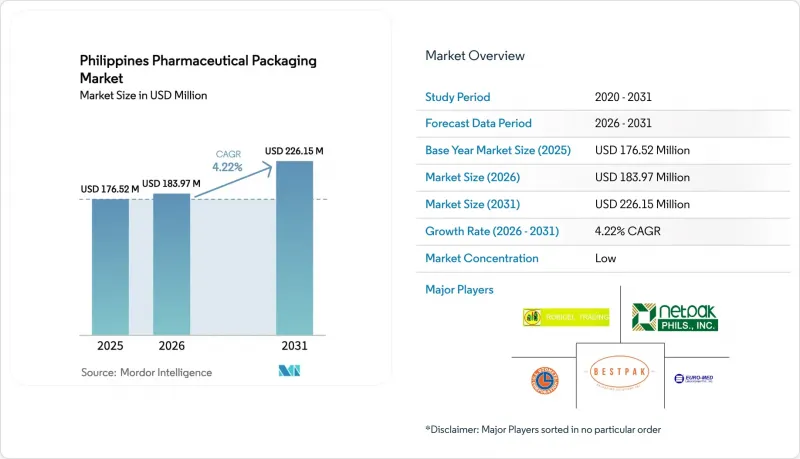
에 의하면, 2026년 필리핀 의약품 포장 시장 규모는 1억 8,397만 달러로 추정되고, 2025년 1억 7,652만 달러에서 확대해, 2031년에는 2억 2,615만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 4.22%로 성장할 것으로 전망됩니다.
본 보고서는 소재 유형별(플라스틱, 유리 등), 제품 유형별(병, 바이알 및 앰플, 블리스터 팩, 프리필드 주사기 및 카트리지 등), 포장 수준별(1차 포장, 2차 포장, 3차 포장), 최종 사용자 산업별(의약품 제조업체, 위탁 포장 업체 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
필리핀의 의약품 포장 시장 동향 및 인사이트
제네릭 의약품 생산 확대
현재 45일로 단축된 신속 승인으로 인해 시장 진입 기간이 단축됨에 따라, 현지 기업들은 라벨 재설계 및 규정을 준수하는 블리스터, 병, 파우치 솔루션에 대한 투자를 서둘러야 하는 상황에 놓여 있습니다. 제네릭 의약품 시장 규모는 2028년까지 38억 달러에 달할 것으로 예측되며, 모든 신규 분자에 대해 보건부의 제네릭 의약품 라벨 요건을 충족하는 일련번호가 부여된 포장이 요구되고 있습니다. PEZA(필리핀 경제특구청) 관할 구역 내의 세제 혜택이 생산량을 끌어올리고 있는 한편, 2024년 8월 필리핀에서 입지 조사를 실시한 인도계 기업 5곳은 고차단성 병 및 부정 개봉 방지 씰에 대한 향후 수요를 시사하고 있습니다. 우수 제조 기준(GMP) 지침에 따라 원자재 사전 인증을 취득한 포장 가공업체들은 이러한 신규 진출기업들로부터 조기에 공급업체 지위를 확보하고 있으며, 2025-2028년 전체 계약 주기 동안의 생산량 확보를 확고히 하고 있습니다.
필수 의약품의 정부 조달 확대
필리핀 파마 프로큐어먼트(Philippine Pharma Procurement Inc.)의 로드맵은 2030년까지 입찰에서 국내 생산자의 점유율을 50%로 끌어올리는 것을 목표로 하고 있으며, 이를 통해 ‘그린 레인(Green Lane)’ 라이선싱 제도 하에서 이미 인증을 받은 공급업체에 대한 정기적인 발주가 보장됩니다. 3,525만 달러가 투자된 클라크 의약품 물류 허브에는 GDP 인증을 받은 창고가 마련되어 있으며, 일련번호가 부여된 카톤 및 사전 인쇄된 라벨을 제공하는 공급업체를 지원하고 있습니다. 필수 의약품 포장, 당뇨병 검사 스트립, 항고혈압제 블리스터 슬리브, 항암제 벌은 현재 보건부 재고 관리 플랫폼과 연동되는 추적성용 QR 코드 표기가 의무화되어 있습니다. 엔드투엔드 코딩 서비스와 데이터 무결성 감사를 제공하는 컨버터 기업들은 가격 프리미엄을 확보하면서도 다년 계약을 체결하고 있으며, 필리핀 의약품 포장 시장에서 수익 다각화를 가속화하고 있습니다.
수입 원자재에 대한 높은 의존도
유효 성분의 98%와 플라스틱 수지의 대부분이 수입에 의존하고 있기 때문에 각 컨버터 기업들은 환율 변동과 운송 차질에 직면하여 이익률이 압박받고 있습니다. 필리핀 의약품 산업 협회에 따르면, 2015년부터 2019년에 걸쳐 원자재 수입량은 15% 증가했습니다. 또한 팬데믹으로 인해 리드 타임이 120일 이상에 달하는 상황이 드러나면서, 각 컨버터 업체들은 완충 재고를 2배로 늘릴 수밖에 없었습니다. 국내에 석유화학 산업의 기반이 없기 때문에 수지 가격은 인근 국가들보다 8-12% 높은 수준을 유지하고 있으며, 일부 충전 업체들은 태국이나 말레이시아에서 프리폼을 조달하고 있습니다. 무역산업부는 펠릿 수입에 대한 관세 인하를 검토하고 있지만, 단기적인 가격 변동은 계속되고 있어 1회의 입찰 주기를 넘어서는 원가 가산 계약을 확보하기는 어렵습니다.
부문별 분석
플라스틱은 2025년에 필리핀 의약품 포장 시장의 39.85%를 차지했으며, 수량 면에서 주요한 우위를 점하고 있습니다. HDPE 병, PET 용기, 폴리프로필렌 캡이 가장 일반적으로 사용되는 소재입니다. 이는 규제 관련 자료에 이미 이러한 소재의 전환 데이터가 기재되어 있어 승인까지의 리드 타임을 단축할 수 있기 때문입니다. 필리핀 의약품 포장 시장의 플라스틱 부문 규모는 새로운 확대 생산자 책임(EPR) 규정에 따라 2028년까지 회수 목표가 80%로 상향 조정되는 상황에서도 꾸준히 성장할 것으로 예측됩니다. EPR에 따른 비용 증가로 인해 브랜드 소유자들은 바이오 라이너와 재생 PET 소재의 시범 도입을 추진하고 있으며, 이는 가격 상승을 초래하는 한편 세액 공제 혜택도 얻을 수 있습니다.
지속 가능한 복합 소재는 현재 틈새 시장이지만, 전 세계 고객들이 수명 주기 지표를 공급업체의 평가 기준에 반영함에 따라 연평균 성장률(CAGR) 5.96%라는 가장 높은 성장률을 보일 것으로 예측됩니다. 과학기술부 산하 그린 패키징 연구소에서는 키토산 및 펙틴 필름에 대한 실증 시험을 진행하고 있으며, 다국적 기업 중 이를 조기에 도입한 기업들이 공동 출자하여 규모 확대 시험을 진행하고 있습니다. 유리는 유형 I 붕규산 유리의 완전성이 요구되는 주사제 분야에서 견고한 수요 기반을 유지하고 있는 반면, 알루미늄 튜브는 산소 차단성이 요구되는 스테로이드 크림의 충전에 사용되고 있습니다. 이러한 소재의 전환은 종합적으로 공급망의 재편을 가져오고 있으며, 에코존 내에 수지 재활용 라인을 통합한 합작 사업 설립을 촉진하고 있어, 이러한 움직임이 중기적으로 필리핀의 의약품 포장 시장을 지탱하게 될 것입니다.
2025년, 필리핀 의약품 포장 시장에서 병은 21.09%의 점유율을 차지했습니다. 이는 OTC(일반의약품) 기침·감기 시럽 및 비타민 액상제를 취급하는 고속 생산 라인과의 호환성 덕분입니다. 자동 시각 검사 시스템과 유도 씰 라이너를 통해 오염 위험이 감소함에 따라, 공립 병원 입찰에서 병의 채택이 정착되고 있습니다. 한편, 필리핀 의약품 포장 시장에서 파우치 및 백 시장 규모는 연평균 성장률(CAGR) 5.34%로 가장 빠르게 확대되고 있습니다. 이는 온라인 약국이 운송 비용을 30% 절감할 수 있는 경량 라미네이트 소포장을 선호하기 때문입니다.
블리스터 팩은 고형 제제의 복약 순응도에서 여전히 중심적인 역할을 하고 있으며, 특히 FDA가 만성 질환 환자를 위한 QR 코드 연동형 복약 관리 앱에 대응하는 ‘지갑형 블리스터’를 승인한 이후 그 중요성이 더욱 높아지고 있습니다. 백신 접종 캠페인에서는 프리필드 주사기나 카트리지의 인기가 높아지고 있습니다. 한편, 바이알과 앰플은 특수 주사제의 안전성을 유지하고 있습니다. 카톤에는 RFID 인레이나 점자 엠보싱 가공 등 기능적인 개선이 이루어지고 있으며, 팔레트의 코너 보드는 EPR 감사에 대응하기 위해 재생지로 전환되고 있습니다. 이러한 제품 구성의 진화로 인해, 가동 중단으로 인한 손실을 초래하지 않으면서도 단기간 납품이 가능한 맞춤형 키트와 대량 생산되는 범용 배치 사이를 유연하게 전환할 수 있는 컨버터들이 혜택을 보고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Philippines pharmaceutical packaging market size in 2026 is estimated at USD 183.97 million, growing from 2025 value of USD 176.52 million with 2031 projections showing USD 226.15 million, growing at 4.22% CAGR over 2026-2031.
This report is Segmented by Material Type (Plastic, Glass, and More), Product Type (Bottles, Vials and Ampoules, Blister Packs, Prefilled Syringes and Cartridges, and More), Packaging Level (Primary, Secondary, and Tertiary), End-User Industry (Pharmaceutical Manufacturing Companies, Contract Packaging Organizations, and More). The Market Forecasts are Provided in Terms of Value (USD).
Philippines Pharmaceutical Packaging Market Trends and Insights
Growing Generic Drug Production
Fast-tracked approvals, now limited to 45 days, have cut market-entry timelines, prompting local firms to reformulate labels and invest in compliant blister, bottle, and pouch solutions. The generic-drug spending pool is projected to reach USD 3.8 billion by 2028, and every new molecule requires serialization-ready packaging that meets the Department of Health's generic-label mandate. Fiscal perks inside PEZA parks amplify volumes, while five India-based firms that scouted Philippine sites in August 2024 signal future demand for high-barrier bottles and tamper-evident seals. Packaging converters that pre-qualify materials under Good Manufacturing Practice guidelines are winning early supplier status with these green-field entrants, cementing volume commitments across 2025-2028 contract cycles.
Increasing Government Procurement of Essential Medicines
The Philippine Pharma Procurement Inc. roadmap aims to increase the local-producer share of tenders to 50% by 2030, securing routine orders for suppliers already accredited under the Green Lane licensing system. The Clark pharmaceutical logistics hub, a USD 35.25 million investment, features GDP-certified warehousing that caters to suppliers of serialized cartons and pre-printed labels. Essential-medicine packs, diabetes strips, anti-hypertensive blister sleeves, and oncology vals must now carry traceability QR codes that sync with the Department of Health inventory platform. Converters offering end-to-end coding services and data-integrity audits command price premiums yet secure multiyear contracts, accelerating revenue diversification within the Philippines pharmaceutical packaging market.
Heavy Reliance on Imported Raw Materials
With 98% of active ingredients and most plastic resins imported, converters face currency swings and freight disruptions that compress margins. The Philippine Pharmaceutical Industry Association notes raw-material imports grew 15% between 2015-2019; the pandemic exposed lead-time spikes beyond 120 days, forcing converters to double buffer stocks. The lack of a domestic petrochemical base keeps resin prices 8-12% higher than those of regional peers, prompting some fillers to source preforms from Thailand and Malaysia. Although the Department of Trade and Industry considers tariff relief for pellet imports, short-term volatility persists, making cost-plus contracts difficult to secure for more than one bid cycle.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Local Contract Manufacturing Organizations
- Stringent Anti-Counterfeiting Regulations
- Limited Cold Chain Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics deliver the core volume advantage, capturing 39.85% of the Philippines pharmaceutical packaging market in 2025. HDPE bottles, PET jars, and polypropylene closures are the most commonly used materials because regulatory dossiers already reference their migration data, thereby reducing approval lead times. The Philippines pharmaceutical packaging market size for plastics is set to grow steadily, even as new Extended Producer Responsibility (EPR) rules raise recovery targets to 80% by 2028. EPR costs prompt brand owners to trial bio-based liners and recycled-content PET, which command price increases while unlocking tax credits.
Sustainable composites, although niche today, are projected to chart the fastest 5.96% CAGR as global clients incorporate life-cycle metrics into supplier scorecards. The Department of Science and Technology's Green Packaging Laboratory pilots chitosan and pectin films, and early adopters among multinationals co-fund scale-up trials. Glass retains a loyal base in injectables that require Type I borosilicate integrity, while aluminum tubes fill steroid creams that require oxygen barriers. Collectively, these material pivots re-align supply chains, inviting joint ventures that embed resin recycling lines within ecozones, moves that sustain the Philippines pharmaceutical packaging market over the medium term.
Bottles owned 21.09% of the Philippines pharmaceutical packaging market share in 2025, thanks to their compatibility with high-speed lines serving OTC cough-cold syrups and vitamin liquids. Automated vision systems and induction-seal liners reduce contamination risk, solidifying their use in public hospital tenders. Meanwhile, the Philippines pharmaceutical packaging market size for pouches and bags grows fastest at 5.34% CAGR as e-pharmacies prefer lightweight laminate sachets that slash freight costs by 30%.
Blister packs remain central to solid-dose compliance, especially after the FDA endorsed wallet blister formats that support QR-linked adherence apps for patients with chronic diseases. Prefilled syringes and cartridges gain popularity in vaccination drives; vials and ampules maintain the security of specialty injectables. Cartons receive functional upgrades, including RFID inlays and braille embossing, while pallet corner boards transition to recycled paper to meet EPR audits. This product-mix evolution rewards converters who are agile enough to switch between short-run, personalized kits and high-volume, commodity batches without incurring downtime penalties.
Complete Report Scope:
- By Material Type
- Plastic
- High-Density Polyethylene (HDPE)
- Low-Density Polyethylene (LDPE)
- Polyethylene Terephthalate (PET)
- Other Plastics
- Glass
- Metal
- Paper and Paperboard
- Composites/ Bio-based Materials
- Plastic
- By Product Type
- Bottles
- Vials and Ampoules
- Blister Packs
- Prefilled Syringes and Cartridges
- Tubes
- Pallets
- Pouches and Bags
- Carton Boxes
- Other Product Types
- By Packaging Level
- Primary
- Secondary
- Tertiary
- By End-user Industry
- Pharmaceutical Manufacturing Companies
- Contract Packaging Organizations
- Retail and Institutional Pharmacies
- Hospitals and Clinics
- Other End-user Industries
List of Companies Covered in this Report:
- Amcor Flexibles Philippines Corp. (Amcor plc)
- Shandong Pharmaceutical Glass Co., Ltd.
- Robicel Trading
- Bestpak Packaging Solutions, Inc.
- Euro-Med Laboratories Philippines Inc.
- Netpak Phils., Inc.
- GL Otometz Corporation
- Plastic Container Packaging Corporation
- APO International Marketing Corporation
- Merfel Plastic Products
- Versa Group Philippines Corporation
- SwissPac
- Gerresheimer AG
- Schott AG
- Nipro PharmaPackaging International NV
- SGD Pharma
- West Pharmaceutical Services Inc.
- Catalent Inc.
- Datwyler Holding AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Generic Drug Production
- 4.2.2 Increasing Government Procurement of Essential Medicines
- 4.2.3 Expansion of Local Contract Manufacturing Organizations
- 4.2.4 Stringent Anti-Counterfeiting Regulations
- 4.2.5 Rising Demand for Patient-Friendly Packaging
- 4.2.6 Growth of E-Pharmacy Distribution Channels
- 4.3 Market Restraints
- 4.3.1 Heavy Reliance on Imported Raw Materials
- 4.3.2 Limited Cold Chain Infrastructure
- 4.3.3 Price Sensitivity among Local Manufacturers
- 4.3.4 Environmental Compliance Costs
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.1.1 High-Density Polyethylene (HDPE)
- 5.1.1.2 Low-Density Polyethylene (LDPE)
- 5.1.1.3 Polyethylene Terephthalate (PET)
- 5.1.1.4 Other Plastics
- 5.1.2 Glass
- 5.1.3 Metal
- 5.1.4 Paper and Paperboard
- 5.1.5 Composites/ Bio-based Materials
- 5.1.1 Plastic
- 5.2 By Product Type
- 5.2.1 Bottles
- 5.2.2 Vials and Ampoules
- 5.2.3 Blister Packs
- 5.2.4 Prefilled Syringes and Cartridges
- 5.2.5 Tubes
- 5.2.6 Pallets
- 5.2.7 Pouches and Bags
- 5.2.8 Carton Boxes
- 5.2.9 Other Product Types
- 5.3 By Packaging Level
- 5.3.1 Primary
- 5.3.2 Secondary
- 5.3.3 Tertiary
- 5.4 By End-user Industry
- 5.4.1 Pharmaceutical Manufacturing Companies
- 5.4.2 Contract Packaging Organizations
- 5.4.3 Retail and Institutional Pharmacies
- 5.4.4 Hospitals and Clinics
- 5.4.5 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor Flexibles Philippines Corp. (Amcor plc)
- 6.4.2 Shandong Pharmaceutical Glass Co., Ltd.
- 6.4.3 Robicel Trading
- 6.4.4 Bestpak Packaging Solutions, Inc.
- 6.4.5 Euro-Med Laboratories Philippines Inc.
- 6.4.6 Netpak Phils., Inc.
- 6.4.7 GL Otometz Corporation
- 6.4.8 Plastic Container Packaging Corporation
- 6.4.9 APO International Marketing Corporation
- 6.4.10 Merfel Plastic Products
- 6.4.11 Versa Group Philippines Corporation
- 6.4.12 SwissPac
- 6.4.13 Gerresheimer AG
- 6.4.14 Schott AG
- 6.4.15 Nipro PharmaPackaging International NV
- 6.4.16 SGD Pharma
- 6.4.17 West Pharmaceutical Services Inc.
- 6.4.18 Catalent Inc.
- 6.4.19 Datwyler Holding AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


