|
시장보고서
상품코드
2125565
중국의 API(원료의약품) 시장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)China Active Pharmaceutical Ingredients - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
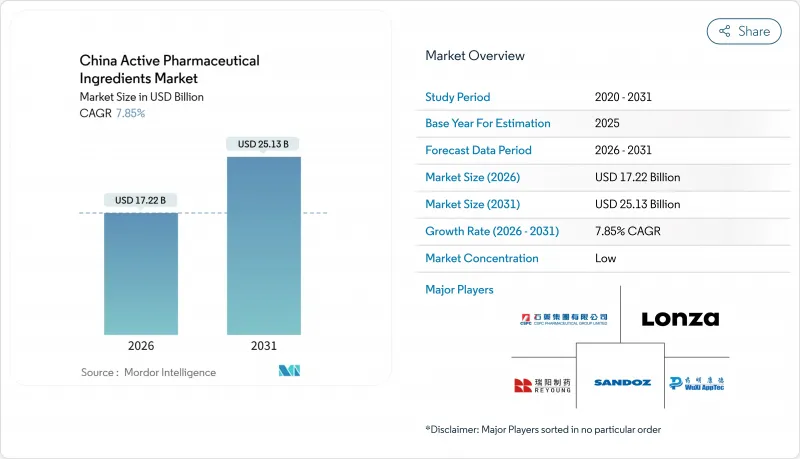
에 의하면, 중국 API(원료의약품) 시장 규모는 2026년에 172억 2,000만 달러로 추정되며, 예측 기간(2026-2031년) CAGR 7.85%로 성장을 지속하여, 2031년에는 251억 3,000만 달러에 이를 전망입니다.

본 보고서는 비즈니스 모델(캡티브 API·머천트 API), 합성 유형(합성·바이오기술), 의약품 유형(제네릭·브랜드), 용도(순환기, 종양, 호흡기, 신경, 정형외과, 안과, 기타)별로 세분화되어 있습니다. 본 보고서에서는 상기 각 부문 시장 규모(달러)를 제시하고 있습니다.
중국 API(원료의약품) 시장 동향 및 인사이트
만성 질환 및 생활습관병 유병률의 상승
중국 사망 원인의 80% 이상은 심혈관 질환, 당뇨병, 암에 기인하며, 60세 이상 국민의 75%가 적어도 하나의 만성 질환을 앓고 있습니다. 이러한 부담으로 인해 VBP(가치 기반 지불)에 따른 가격 압박에도 불구하고, 스타틴, 메트포르민 전구체, 항암제 중간체에 대한 수요는 지속될 것으로 예측됩니다. 당뇨병 진단 건수는 1억 4,000만 건에 달하며, 항당뇨병용 API에 대한 높은 기본 수요가 확고하게 자리 잡고 있습니다. ‘건강 중국 2030’ 정책에 따라 도입된 성(省) 차원의 암 검진 의무화는 PD-1 및 키나아제 억제제 중간체의 주문 증가를 더욱 가속화하고 있습니다. 65세 이상 인구는 2030년까지 3억 명을 넘어설 전망이므로, 신경계 질환 및 골다공증 치료용 API 수요는 예측 기간 동안 견조한 추세를 보일 것으로 예측됩니다.
바이오의약품·바이오시밀러의 국내 사용 확대
중국에서는 2015년부터 2024년까지 4,382건의 혁신 의약품 개발 프로그램이 시작되었고, 중국에서 개발된 18개 제품이 해외에서 승인을 획득함에 따라 단일클론 항체 및 재조합 단백질 원료의약품에 대한 국내 수요가 촉진되었습니다. 쾰른·BPC사는 ADC 중간체에 투자한 반면, 루예 파마사는 제네릭 의약품으로 인한 원료의약품(VBP) 가격 하락으로 침식된 이익률을 유지하기 위해 나노의료 기술 역량 강화를 도모했습니다. 2020년에 도입된 바이오시밀러 심사 규정의 간소화로 인해 트라스투주맙의 후속 제품은 18개월 이내에 국내 시장에서 상당한 점유율을 확보할 수 있었습니다. Cytiva사의 2025년판 지수에 따르면, 중국의 바이오 제조 역량은 5.72로 평가되었으며, 조사 대상인 스폰서의 61%가 지역 내 조달을 확대할 계획이라고 보고되었습니다. 이러한 지표들은 2026년부터 2031년까지 바이오테크용 원료의약품 시장의 연평균 성장률(CAGR)이 11.85%를 나타낼 것이라는 전망을 뒷받침하고 있습니다.
약가 규제와 전국적인 수량 기준 조달
2024년 암 치료제 분야에서 VBP(수량 기준 조달)가 확대됨에 따라 원료의약품 비용 절감 요구가 발생하여, 시장 연평균 성장률(CAGR) 전망치가 1.6포인트 하향 조정되었습니다. CSPC(국가의약품감독관리국)의 원료의약품 매출액은 2024년에 판매량이 증가했음에도 불구하고 전년 대비 1.6% 감소하여 이익률 하락을 나타냈습니다. 이 정책은 브랜드 간 차별화를 무력화함으로써 상품화를 가속화하고, 공급업체들이 VBP의 영향력이 약한 복잡한 펩타이드나 고부가가치 원료의약품(HPAPI)으로 전환하도록 강요하고 있습니다.
부문별 분석
중국 API(원료의약품) 시장에서는 2025년 매출의 58.55%를 일반 제조업체가 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 8.25%를 나타낼 것으로 전망됩니다. 유럽과 미국의 제약 기업들은 연구개발(R&D) 예산을 확보하기 위해 아웃소싱을 진행하고 있으며, 멀티 클라이언트 포트폴리오가 고정비 분산에 기여하고 있습니다. 169에이커 부지에 1,000m3가 넘는 반응조를 보유한 WuXi의 타이싱(泰興) 복합 시설은 그 규모의 우위를 보여주고 있습니다. 자사 전용 시설은 파이프라인 자산이 실패하거나 특허가 만료될 경우 가동률이 저하될 위험이 있는 반면, 머천트형 공급업체는 생산 능력을 신속하게 재분배할 수 있습니다. 그러나 소수의 해외 고객에 대한 의존도가 높기 때문에 머천트형 기업은 지정학적 충격에 취약하며, 2024년 우시 어드밴스드 테라피즈(WuXi Advanced Therapies)의 매출에 타격을 입혔던 ‘바이오시큐어법’에 따른 일시 중단 사태와 같은 상황이 발생할 가능성이 있습니다.
또한, 머천트 모델은 지리적 분산도 용이하게 합니다. 아신켐(Asynchem)의 영국 기업 인수나 파마론(Pharmalon)의 영국 거점을 통해, 중국의 CDMO 기업들은 저비용의 중국 본토 생산을 유지하면서도 유럽 및 미국의 규제 당국에 등록 주소를 기재할 수 있게 됩니다. 고효능 의약품 및 펩타이드 제품 라인은 프리미엄 가격을 책정할 수 있어 VBP(가치 기반 지불)의 영향으로부터 이익률을 보호할 수 있으며, 2031년까지 신규 머천트 기업의 설비 투자(CAPEX)의 대부분이 이에 집중되고 있습니다.
중국의 API(원료의약품) 시장에서 2025년 시장 가치의 70.53%는 여전히 합성 화학이 차지하고 있지만, 바이오의약품 파이프라인이 가속화되고 있는 덕분에 바이오기술 API는 연평균 성장률(CAGR) 11.85%로 확대되고 있습니다. 쑤저우와 상하이의 산업 단지에서는 포유류 세포 배양 생산 능력이 확대되고 있으며, Cytiva사는 2025년 지수에서 중국의 바이오 제조를 5.72로 평가했습니다.
바이오테크 API의 단가는 저분자 화합물의 3-5배에 달하며, 이는 공급업체에게 원자재 가격 변동에 대한 완충 역할을 하고 있습니다. VBP 대상 분자가 늘어남에 따라 합성 API의 마진은 축소되는 추세이며, 화학 분야에서는 키랄 중간체 및 HPAPI로의 전환이 진행되고 있습니다. 이러한 분야에서는 특수한 격리 기술이 필요하기 때문에 더 높은 가격 책정이 정당화됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.17According to Mordor Intelligence, the China active pharmaceutical ingredients market size is estimated at USD 17.22 billion in 2026, and is expected to reach USD 25.13 billion by 2031, at a CAGR of 7.85% during the forecast period (2026-2031).
This report is Segmented by Business Mode (Captive API and Merchant API), Synthesis Type (Synthetic and Biotech), Drug Type (Generic and Branded), and Application (Cardiology, Oncology, Pulmonology, Neurology, Orthopedic, Ophthalmology, and Other Applications). The Report Offers the Value (USD) for the Above Segments.
China Active Pharmaceutical Ingredients Market Trends and Insights
Rising Prevalence Of Chronic & Lifestyle Diseases
Cardiovascular disease, diabetes, and cancer account for more than 80% of Chinese mortality, and 75% of citizens aged 60 plus manage at least one chronic condition. The burden guarantees sustained ordering of statins, metformin precursors, and oncology intermediates despite VBP price compressions. Diagnosed diabetes cases reached 140 million, locking in high baseline demand for antidiabetic APIs. Provincial cancer-screening mandates introduced under Healthy China 2030 further accelerate orders for PD-1 and kinase inhibitor intermediates. Because the population aged 65 plus will top 300 million by 2030, demand for neurology and osteoporosis APIs is projected to remain resilient across the forecast window.
Growing Domestic Use Of Biologics & Biosimilars
China initiated 4,382 innovative drug programs between 2015 and 2024, and 18 Chinese-origin products won overseas approvals, catalyzing local demand for monoclonal-antibody and recombinant-protein APIs. Kelun-BPC invested in ADC intermediates, while Luye Pharma advanced nanomedicine capabilities to retain more value margins that generic VBP has eroded. Streamlined biosimilar review rules introduced in 2020 helped trastuzumab follow-ons capture sizeable domestic share within 18 months. Cytiva's 2025 index rated China 5.72 in biomanufacturing capacity and reported that 61% of surveyed sponsors plan to increase regional sourcing. These indicators underpin the 11.85% CAGR outlook for biotech APIs over 2026-2031.
Drug-Price Control & National Volume-Based Procurement
The 2024 VBP extension to oncology triggered API cost-down requests that erased 1.6 percentage points from market CAGR projections. CSPC's bulk-drug revenue dipped 1.6% year-over-year in 2024 despite higher volumes, illustrating margin erosion. The policy accelerates commoditization by neutralizing brand differentiation, forcing suppliers toward complex peptides and HPAPIs where VBP leverage is weaker.
Other drivers and restraints analyzed in the detailed report include:
- Yuan Depreciation Widens Export Price Advantage
- Supply-Chain Friend-Shoring Boosts China CDMO Orders
- Fierce Competition & Stricter GMP / Environmental Rules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Merchant players captured 58.55% of 2025 revenue in the China active pharmaceutical ingredients market and are tracking an 8.25% CAGR to 2031. Western pharma is outsourcing to preserve R&D budgets, and multi-client portfolios help spread fixed costs. WuXi's Taixing complex, spanning 169 acres with over 1,000 m3 reactors, demonstrates the scale advantage. Captive facilities risk low utilization whenever pipeline assets fail or patents expire, while merchant suppliers can redeploy capacity quickly. However, reliance on a concentrated foreign client base leaves merchant firms vulnerable to geopolitical shocks such as the Biosecure Act suspension wave that dented WuXi Advanced Therapies revenue in 2024.
The merchant model also eases geographic diversification. Asymchem's U.K. acquisition and Pharmaron's British sites allow Chinese CDMOs to list Western regulatory addresses while retaining low-cost mainland production. High-potency and peptide lines command premium pricing, insulating margins from VBP, and are the focal points of most new merchant CAPEX through 2031.
Synthetic chemistry still holds 70.53% of the 2025 market value in the China active pharmaceutical ingredients market, yet biotech APIs are scaling at an 11.85% CAGR courtesy of an accelerated biologics pipeline. Mammalian cell-culture capacity is expanding in Suzhou and Shanghai parks, with Cytiva rating Chinese biomanufacturing at 5.72 in its 2025 index.
Biotech APIs earn 3-5 times the unit price of small molecules, cushioning suppliers against input price swings. Synthetic APIs face shrinking spreads as VBP covers more molecules, nudging chemistries toward chiral intermediates and HPAPIs where specialized containment justifies higher quotations.
Complete Report Scope:
- By Business Mode
- Captive API
- Merchant API
- By Synthesis Type
- Synthetic
- Biotech
- By Drug Type
- Generic
- Branded
- By Application
- Cardiology
- Oncology
- Pulmonology
- Neurology
- Orthopedic
- Ophthalmology
- Other Applications
List of Companies Covered in this Report:
- Asymchem Laboratories (Tianjin) Co., Ltd.
- Chengdu Tianyin Pharmaceutical Co., Ltd.
- CSPC Pharmaceutical Group Ltd.
- Hangzhou Zhongmei Huadong Pharmaceutical Co., Ltd.
- Kelun-BPC
- Lonza Guangzhou Ltd.
- Luye Pharma Group Ltd.
- Nanjing Kingfriend Biochemical Pharmaceutical Co., Ltd.
- Northeast Pharmaceutical Group Co., Ltd.
- Pharmaron Beijing Co., Ltd.
- Porton Pharma Solutions Ltd.
- Shandong Xinhua Pharmaceutical Co., Ltd.
- Shenzhen Hepalink Pharmaceutical Co., Ltd.
- STA Pharma (WuXi)
- WuXi AppTec (STA Pharmaceutical)
- Zhejiang Garden Biopharmaceutical Co., Ltd.
- Zhejiang Hisun Pharmaceutical Co., Ltd.
- Zhejiang Huahai Pharmaceutical Co., Ltd.
- Zhejiang Medicine Co., Ltd.
- Zhejiang NHU
- Reyoung Pharmaceuticals
- Sandoz Group AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of chronic & lifestyle diseases
- 4.2.2 Growing domestic use of biologics & biosimilars
- 4.2.3 Yuan depreciation widens export price advantage
- 4.2.4 Supply-chain friend-shoring boosts China CDMO orders
- 4.2.5 Government policies favoring local pharmaceutical manufacturing
- 4.2.6 Rising demand for affordable generics
- 4.3 Market Restraints
- 4.3.1 Drug-price control & national volume-based procurement
- 4.3.2 Fierce competition & stricter GMP / environmental rules
- 4.3.3 Emerging US/EU tariffs on critical-drug raw materials
- 4.3.4 Volatile coal & solvent prices squeezing small producers
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Business Mode
- 5.1.1 Captive API
- 5.1.2 Merchant API
- 5.2 By Synthesis Type
- 5.2.1 Synthetic
- 5.2.2 Biotech
- 5.3 By Drug Type
- 5.3.1 Generic
- 5.3.2 Branded
- 5.4 By Application
- 5.4.1 Cardiology
- 5.4.2 Oncology
- 5.4.3 Pulmonology
- 5.4.4 Neurology
- 5.4.5 Orthopedic
- 5.4.6 Ophthalmology
- 5.4.7 Other Applications
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Asymchem Laboratories (Tianjin) Co., Ltd.
- 6.3.2 Chengdu Tianyin Pharmaceutical Co., Ltd.
- 6.3.3 CSPC Pharmaceutical Group Ltd.
- 6.3.4 Hangzhou Zhongmei Huadong Pharmaceutical Co., Ltd.
- 6.3.5 Kelun-BPC
- 6.3.6 Lonza Guangzhou Ltd.
- 6.3.7 Luye Pharma Group Ltd.
- 6.3.8 Nanjing Kingfriend Biochemical Pharmaceutical Co., Ltd.
- 6.3.9 Northeast Pharmaceutical Group Co., Ltd.
- 6.3.10 Pharmaron Beijing Co., Ltd.
- 6.3.11 Porton Pharma Solutions Ltd.
- 6.3.12 Shandong Xinhua Pharmaceutical Co., Ltd.
- 6.3.13 Shenzhen Hepalink Pharmaceutical Co., Ltd.
- 6.3.14 STA Pharma (WuXi)
- 6.3.15 WuXi AppTec (STA Pharmaceutical)
- 6.3.16 Zhejiang Garden Biopharmaceutical Co., Ltd.
- 6.3.17 Zhejiang Hisun Pharmaceutical Co., Ltd.
- 6.3.18 Zhejiang Huahai Pharmaceutical Co., Ltd.
- 6.3.19 Zhejiang Medicine Co., Ltd.
- 6.3.20 Zhejiang NHU Co., Ltd.
- 6.3.21 Reyoung Pharmaceuticals
- 6.3.22 Sandoz Group AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment