

|
시장보고서
상품코드
2125577
클라우드 컴퓨팅 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cloud Computing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
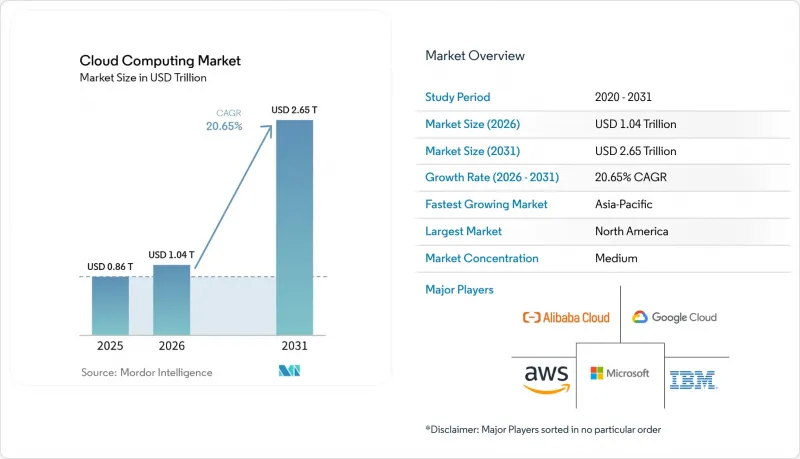
에 의하면, 클라우드 컴퓨팅 시장 규모는 2025년 8,600억 달러에서 2026년에는 1조 400억 달러로 확대되어 2026년부터 2031년까지 CAGR 20.65%로 성장을 지속하여, 2031년까지 2조 6,500억 달러에 이를 것으로 예측됩니다.
본 보고서는 서비스 모델(IaaS, PaaS, SaaS), 배포 모델(퍼블릭 클라우드, 프라이빗 클라우드, 하이브리드 클라우드), 최종 사용자 업종(IT 및 통신, 은행, 금융서비스 및 보험(BFSI), 제조 등), 조직 규모(대기업, 중소기업), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 클라우드 컴퓨팅 시장 동향 및 인사이트
핵심 업무용 소프트웨어 분야에서 SaaS의 폭발적인 확산
클라우드 전환의 대상은 더 이상 생산성 향상을 위한 워크로드에 그치지 않고, 미션 크리티컬한 기업 자원 계획(ERP), 고객 관계 관리(CRM), 재무 시스템까지 확대되고 있으며, 이러한 변화가 클라우드 컴퓨팅 시장 전체를 점점 더 형성하고 있습니다. 델타항공은 2024년, SaaS를 활용하여 AI 기반 개인화 및 정시 운항률 향상을 실현하기 위해 5억 달러 규모의 디지털 코어 개편을 완료했습니다. 이러한 전환을 통해 지속적인 기능 업데이트와 내장형 분석이 실현되어, On-Premise형 소프트웨어로는 불가능했던 실시간 의사 결정이 가능해졌습니다. 규제 대상 산업에서는 SaaS 스택에 통합된 표준화된 규정 준수 관리의 이점을 통해 감사 신속화와 운영 비용 절감이 진행되고 있습니다. 전환을 미루고 있는 조직은 SaaS를 우선적으로 도입하고 있는 동종 업계 경쟁사에 비해 기능적 격차나 제품 주기 지연이라는 위험에 직면할 가능성이 있습니다.
탄력적인 컴퓨팅이 필요한 생성형 AI 워크로드의 급증
대규모 언어 모델 훈련에는 수천 대의 고대역폭 GPU를 병렬로 가동해야 하며, 이는 기존 엔터프라이즈 워크로드의 실적를 훨씬 초과합니다. Oracle은 2025년 OpenAI를 지원할 텍사스 주 거점을 위해 400억 달러 상당의 NVIDIA 프로세서를 확보했습니다. 이러한 규모의 확대는 데이터센터의 전력, 냉각, 네트워크 패브릭 설계에 극적인 변화를 가져오고 있습니다. 각 공급업체는 증가하는 수요를 충족하기 위해 AI에 최적화된 실리콘, 직접 액체 냉각, 고속 상호 연결을 중심으로 아키텍처 재구성을 추진하고 있습니다. 고객들은 버스트형 AI 실험이나 프로덕션 환경에서의 추론에 대해 용량과 유리한 비용 구조를 보장할 수 있는 벤더를 선호하고 있습니다.
데이터 현지화 법안이 세계 확장을 가로막고 있다.
관할 구역별 데이터 상주 규정에 따라 서비스 제공업체는 인프라를 중복 구축하고 독립적인 논리적 환경을 조성할 수밖에 없어, 비용과 운영의 복잡성이 증가하고 있습니다. 다국적 기업들은 스토리지, 처리, 인력의 접근과 관련하여 중복되는 의무에 직면하고 있으며, 많은 경우 아키텍처 재설계나 서비스 가격 인상을 감수해야만 합니다.
부문 분석
Platform-as-a-Service(PaaS)는 2026년부터 2031년까지 연평균 성장률(CAGR) 22.85%를 나타낼 것으로 예측되며, 이는 서비스 모델 중 가장 빠른 속도입니다. SaaS는 2025년 매출에서 52.87%라는 압도적인 점유율을 유지하고 있는 반면, IaaS(Infrastructure-as-a-Service)는 여전히 그 기반이 되는 탄력적인 토대를 형성하고 있습니다. PaaS의 성장세를 뒷받침하는 요인은 컨테이너 오케스트레이션, 서버리스 런타임, 그리고 릴리스 주기를 수개월에서 수주로 단축하는 로우코드 도구입니다. 아마존은 이러한 PaaS 워크로드를 처리하기 위해 AI 중심의 데이터센터에 1,500억 달러를 투자했습니다. 프로바이더들이 내장형 보안 및 AI 서비스로 플랫폼을 강화함에 따라, 개발자들은 인프라의 세부 사항에 얽매이지 않고 사용자 가치에 집중할 수 있는 자유도가 높아지고 있습니다.
클라우드 컴퓨팅 시장에서 PaaS 벤더들은 업계별 프레임워크와 통합된 MLOps를 통해 차별화를 꾀하고 있습니다. 이러한 기능 덕분에 고급 분석 도입 기간이 단축되고, 코드 품질이 향상되며, 개발자의 부담이 경감됩니다. 이러한 조합을 통해 PaaS는 디지털 제품을 위한 전략적 수단으로서의 입지를 확고히 하며, 신속한 실험과 지속적인 배포를 뒷받침하고 있습니다.
2025년에는 프라이빗 클라우드가 매출의 46.62%를 차지하며, 하이브리드 클라우드는 연평균 성장률(CAGR) 22.24%로 확대되고 있습니다. 이 모델에서는 기밀성이 높은 워크로드의 경우 데이터를 가까이에서 보관하면서, 테스트, 분석, 재해 복구 시에는 퍼블릭 클라우드의 용량을 버스트 방식으로 활용할 수 있습니다. 기업들이 On-Premise 핵심 환경과 외부 위탁 용량 전반에 걸쳐 쿠버네티스(Kubernetes) 제어 플레인을 표준화해 나감에 따라, 하이브리드 배포 분야의 클라우드 컴퓨팅 시장 규모는 급격히 확대될 전망입니다.
Oracle과 AWS의 크로스 클라우드 제휴를 통해 데이터 출력 요금이 폐지되어, Oracle 데이터베이스가 어느 제공업체에서든 원활하게 작동할 수 있게 되었습니다. 상호 운용성 덕분에 벤더 종속성에 대한 우려가 완화되어, 고객은 성능과 가격에 따라 최적의 선택을 할 수 있게 되었습니다. 그 결과, 하이브리드 전략은 규정 준수를 위한 안전 장치이자, 위험이 높은 전면적인 마이그레이션(포크리프트 마이그레이션)을 수반하지 않는 현대화의 발판으로 간주되고 있습니다.
지역별 분석
북미는 클라우드 도입에 있어 초기 선두 주자였으며, 디지털 네이티브 기업이 밀집해 있는 클러스터 덕분에 2025년 매출의 24.18%를 차지했습니다. 투자는 계속해서 진행되고 있습니다. 아마존은 펜실베이니아주와 노스캐롤라이나주의 캠퍼스에 300억 달러를 투자하고 있으며, 마이크로소프트는 2025 회계연도에 800억 달러 규모의 용량 확충을 계획하고 있습니다. 이 지역의 성장은 현재 인재 및 연구 거점과의 근접성이 필요한 AI 워크로드를 중심으로 전개되고 있습니다. 기업들이 중복성과 비용 최적화를 위해 워크로드를 분산시키는 가운데, 캐나다와 멕시코도 새로운 기회를 개척하고 있습니다.
유럽에서는 적극적인 디지털 전환 목표와 엄격한 데이터 주권 규제의 균형이 잡혀 있으며, 이것이 클라우드 컴퓨팅 시장에서 해당 지역의 발전 방향을 형성하고 있습니다. 기업들은 기밀 데이터를 현지에서 보관하면서 개발 및 분석에는 전 세계 클라우드를 활용하는 하이브리드 아키텍처를 선호하고 있습니다. OVHcloud와 같은 제공업체들은 유럽 내 데이터 보관을 독자적인 강점으로 강조하고 있습니다. 브렉시트 이후의 지정학적 변화로 인해 영국 기업들은 끊임없이 변화하는 국경을 넘는 데이터 협정에 대응할 수밖에 없게 되었으며, 이는 하이브리드 도입을 더욱 촉진하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 21.65%가 예상되는 미래 성장의 원동력입니다. 인프라 프로젝트가 급속히 확대되고 있으며, Sify사는 인도의 AI 전용 데이터센터에 50억 달러를 투자할 예정입니다. 알리바바 클라우드와 텐센트 클라우드와 같은 국내 대기업들이 중국 시장을 독점하는 한편, 국제적인 제공업체들은 일본, 한국, 인도, 그리고 급성장 중인 아세안(ASEAN) 국가들을 목표로 삼고 있습니다. 각국 정부는 ‘클라우드 퍼스트’ 정책과 스마트 시티 계획을 뒷받침하며, 확장 가능한 플랫폼에 대한 수요를 가속화하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.17According to Mordor Intelligence, the cloud computing market size is expected to grow from USD 0.86 trillion in 2025 to USD 1.04 trillion in 2026 and is forecast to reach USD 2.65 trillion by 2031 at 20.65% CAGR over 2026-2031.
This report is Segmented by Service Model (IaaS, Paas, Saas). Deployment Model (Public Cloud, Private Cloud, Hybrid Cloud), End User Vertical (IT and Telecom, BFSI, Manufacturing, and More), Organization Size (Large Enterprises, Small and Mid-Sized Enterprises (SMEs)) and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Cloud Computing Market Trends and Insights
Explosive SaaS adoption in core enterprise software
Cloud migrations now encompass mission-critical enterprise-resource-planning, customer-relationship-management, and finance systems rather than only productivity workloads, a shift that is increasingly shaping the broader Cloud Computing Market. Delta Air Lines finalized a USD 500 million overhaul of its digital core in 2024, using SaaS to enable AI-driven personalization and punctuality improvements. The pivot delivers continuous feature updates and embedded analytics, unlocking real-time decision-making that on-premises software cannot match. Regulated sectors benefit from standardized compliance controls baked into SaaS stacks, accelerating audits and lowering operational overhead. Organizations delaying migration risk capability gaps and slower product cycles compared with SaaS-first peers
Proliferation of Gen-AI workloads demanding elastic compute
Large-language-model training requires thousands of high-bandwidth GPUs operating in parallel, dwarfing previous enterprise-workload footprints. Oracle reserved USD 40 billion worth of Nvidia processors for a Texas site supporting OpenAI in 2025. Such scale drives radical shifts in data-center power, cooling, and network fabric design. Providers are re-architecting around AI-optimized silicon, direct-liquid cooling, and high-speed interconnects to satisfy growing demand. Customers gravitate toward vendors able to guarantee capacity and favorable economics for bursty AI experiments and production inference.
Data-localization laws fragmenting global footprints
Jurisdiction-specific residency rules compel providers to duplicate infrastructure and create discrete logical environments, adding cost and operational complexity. Multinationals face overlapping obligations on storage, processing, and personnel access, often forcing architectural redesigns and higher service prices.
Other drivers and restraints analyzed in the detailed report include:
- Industry-specific cloud platforms (compliance-ready blueprints)
- Sovereign-cloud mandates in EU and GCC
- Run-rate cost overruns vs on-prem TCO
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Platform-as-a-Service is forecast to compound at 22.85% from 2026-2031, the quickest pace among service models. SaaS retained a commanding 52.87% of 2025 revenue, while Infrastructure-as-a-Service remains the elastic foundation underneath. The PaaS wave is fueled by container orchestration, serverless runtimes, and low-code tools that compress release cycles from months to weeks. Amazon earmarked USD 150 billion for AI-centric data centers catering to those PaaS workloads. As providers enrich platforms with built-in security and AI services, developers gain more freedom to focus on user value rather than plumbing.
In the cloud computing market, PaaS vendors increasingly differentiate through industry frameworks and integrated MLOps. These capabilities shorten deployment of advanced analytics, raise code quality, and reduce developer toil. The combination positions PaaS as a strategic lever for digital products, underpinning rapid experimentation and continuous delivery.
Although private clouds captured 46.62% revenue in 2025, hybrid clouds are expanding at 22.24% CAGR. The model preserves data closeness for sensitive workloads while bursting to public capacity for testing, analytics, and disaster recovery. The cloud computing market size for hybrid deployments is set to rise sharply as firms standardize Kubernetes control planes across on-premises cores and outsourced capacity.
Oracle's cross-cloud pact with AWS eliminates data-egress fees and permits Oracle Database to run seamlessly on either provider. Interoperability curbs vendor-lock fears and lets customers optimize on performance or price. Consequently, the hybrid strategy is viewed as a safety valve for compliance and a springboard for modernization without risky forklift migrations.
Complete Report Scope:
- By Service Model
- IaaS
- PaaS
- SaaS
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By End-user Vertical
- IT and Telecom
- BFSI
- Manufacturing
- Retail and Consumer Goods
- Healthcare and Life Sciences
- Others
- By Organisation Size
- Large Enterprises
- Small and Mid-Sized Enterprises (SMEs)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America commanded 24.18% of 2025 revenue thanks to an early lead in cloud adoption and dense clusters of digital-native enterprises. Investment continues: Amazon is channeling USD 30 billion into Pennsylvania and North Carolina campuses, while Microsoft plans USD 80 billion in fiscal-year 2025 capacity. Growth in the region now pivots around AI workloads that demand proximity to talent and research hubs. Canada and Mexico open incremental opportunities as firms spread workloads for redundancy and cost optimization.
Europe balances aggressive digital-transformation targets with stringent data-sovereignty rules, shaping the region's trajectory within the Cloud Computing Market. Organizations favor hybrid architectures that keep sensitive data local yet leverage global clouds for development and analytics. Providers such as OVHcloud emphasize European data residency as a unique selling point. Geopolitical shifts post-Brexit compel UK businesses to navigate evolving cross-border data agreements, further reinforcing hybrid adoption.
Asia-Pacific is the engine of future expansion, with a projected 21.65% CAGR. Infrastructure projects scale rapidly: Sify will invest USD 5 billion in Indian AI-focused data centers. Domestic champions such as Alibaba Cloud and Tencent Cloud dominate China, while international providers target Japan, South Korea, India, and fast-growing ASEAN states. Governments back cloud-first policies and smart-city programs, accelerating demand for scalable platforms.
- Amazon (AWS)
- Microsoft
- Google Cloud
- Alibaba Cloud
- IBM
- Oracle
- Salesforce
- SAP SE
- Adobe
- Tencent Cloud
- Huawei Cloud
- Rackspace
- VMware
- Snowflake
- Workday
- ServiceNow
- DigitalOcean
- OVHcloud
- Linode
- Nutanix
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosive SaaS adoption in core enterprise software
- 4.2.2 Proliferation of Gen-AI workloads demanding elastic compute
- 4.2.3 Industry-specific cloud platforms (compliance-ready blueprints)
- 4.2.4 Sovereign-cloud mandates in EU and GCC
- 4.2.5 Rise of less than 10 ms edge-cloud zones for XR and autonomous ops
- 4.2.6 Green-cloud buying criteria tied to Scope-3 targets
- 4.3 Market Restraints
- 4.3.1 Data-localisation laws fragmenting global footprints
- 4.3.2 Run-rate cost overruns vs on-prem TCO
- 4.3.3 Advanced chip export controls limiting GPU supply
- 4.3.4 Scarcity of low-carbon power for hyperscale DCs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Model
- 5.1.1 IaaS
- 5.1.2 PaaS
- 5.1.3 SaaS
- 5.2 By Deployment Model
- 5.2.1 Public Cloud
- 5.2.2 Private Cloud
- 5.2.3 Hybrid Cloud
- 5.3 By End-user Vertical
- 5.3.1 IT and Telecom
- 5.3.2 BFSI
- 5.3.3 Manufacturing
- 5.3.4 Retail and Consumer Goods
- 5.3.5 Healthcare and Life Sciences
- 5.3.6 Others
- 5.4 By Organisation Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Mid-Sized Enterprises (SMEs)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Southeast Asia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.2.5 Egypt
- 5.5.5.2.6 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon (AWS)
- 6.4.2 Microsoft
- 6.4.3 Google Cloud
- 6.4.4 Alibaba Cloud
- 6.4.5 IBM
- 6.4.6 Oracle
- 6.4.7 Salesforce
- 6.4.8 SAP SE
- 6.4.9 Adobe
- 6.4.10 Tencent Cloud
- 6.4.11 Huawei Cloud
- 6.4.12 Rackspace
- 6.4.13 VMware
- 6.4.14 Snowflake
- 6.4.15 Workday
- 6.4.16 ServiceNow
- 6.4.17 DigitalOcean
- 6.4.18 OVHcloud
- 6.4.19 Linode
- 6.4.20 Nutanix
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


