

|
시장보고서
상품코드
2154981
남미의 5G 기술 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America 5G Technology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
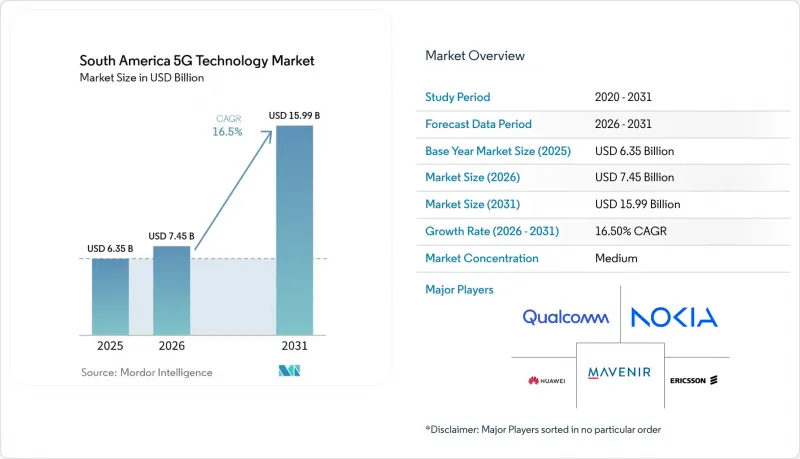
에 따르면 남미의 5G 기술 시장 규모는 2025년에 63억 5,000만 달러, 2026년에 74억 5,000만 달러에 달하며, 2031년까지 159억 9,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 16.50%로 성장할 것으로 전망되고 있습니다.
남미 5G 기술 시장의 동향과 인사이트
남미 주요 경제국에서의 5G 확산 확대
브라질의 주파수 대역 할당 관련 규정에 따라 5G 구축은 통신사업자에게 단계적인 법적 요건이 되었으며, 면허 조건이 구축 기한과 연계되어 네트워크 확장이 사업 환경의 공식적인 일부가 되었습니다. 아나텔(Anatel)은 2026년 12월까지 인구 3만 명 미만의 지자체 중 30%에서 서비스를 제공하도록 의무화하고 있습니다. 이 요건은 2029년까지 전 지역을 커버하는 수준으로 상향 조정될 예정입니다. 2026년 초 기준으로 5G는 1,966개 지자체에 도입되었습니다. 통신부는 2026년 말까지 2,220개 이상의 도시에서 서비스를 이용할 수 있을 것으로 전망하고 있습니다. TIM Brasil은 2026년 1월, 6,500개 이상의 4G 및 5G 기지국에 대해 화웨이 및 노키아와의 공급 계약을 승인했습니다. 이러한 의무는 상업적 매력이 제한적인 지역의 무선 액세스 네트워크 및 고정 무선 액세스에 대한 수요를 지원하는 한편, 공급업체에 장비 납품, 설치 작업 및 서비스 계약에 관한 보다 명확한 일정을 제공하고 있습니다.
저지연 연결에 대한 기업의 수요 확대
광업, 항만, 에너지, 제조업 각 분야에서 기업의 도입은 시범 운영 단계에서 실제 운영 네트워크로 전환되고 있습니다. 이러한 분야의 상업적 타당성은 모니터링 기능 향상, 통신 신뢰성 향상, 자동화, 그리고 현장에 특화된 네트워크 제어에 의해 지원되고 있습니다. 노키아는 2026년 3월, TIM 브라질과의 제휴를 14개 주로 추가 확대했습니다. 이를 통해 브라질 인구의 42%를 커버하게 되었습니다. 이 프로그램은 네트워크 슬라이싱, 이미지 분석, 음성 인식 및 자율 운영을 지원합니다. 노키아는 이번 도입에서 하브록(Habrok)사의 매시브 MIMO(Massive MIMO) 무선기와 엔비디아(NVIDIA)의 AI-RAN 컴퓨팅 기술을 채택했습니다. 발레(Vale), 페트로브라스(Petrobras), 게르다우(Gerdau), 악시아 에너지아(AXIA Energia), 플렉스(Flex) 등 각사는 브라질 내에서 사설 네트워크 운영을 시작했습니다. 이러한 움직임에 따라 사설 무선 연결은 실험적인 기술이라기보다는 계획적인 설비 투자로 자리매김하고 있습니다. 산업용 고객들은 도입 지원, 지속적인 최적화, 안전한 운영, 그리고 특정 현장에 맞춘 연결성을 필요로 하고 있으므로 이러한 수요는 남미의 5G 기술 시장에 기업의 지속적인 수익을 가져다줄 길을 제시하고 있습니다.
주파수 대역 확보 상황의 편차와 경매의 복잡성
남미의 주파수 대역 관련 규제로 인해 각국 시장의 전개 조건이 상이하며, 장비 공급업체와 통신사업자는 국가별로 다른 경매 일정, 라이선스 조건, 주파수 대역 가용성, 기술적 조건에 직면해 있습니다. 브라질과 칠레는 앞서 움직이기 시작했으나, 다른 국가들은 여전히 초기 단계에 머물러 있습니다. 칠레에서는 2026년 초, 잔여 3.5GHz 대역 할당에 관한 의견 수렴이 진행되었습니다. 브라질도 6GHz 대역에 대한 공개 의견 수렴을 시작했습니다. 이러한 절차는 주파수 계획 수립부터 실제 도입까지의 기간을 연장하게 됩니다. 지연이 발생할 때마다 단말기 공급이나 기업용 서비스 개시가 미뤄질 가능성이 있습니다. 아르헨티나, 페루, 에콰도르, 볼리비아에서도 기술적 및 절차적 요건이 서로 다릅니다. 따라서 공급업체는 표준화된 지역 설계가 아닌 국가별 규정 준수 대응이 필요하며, 이는 조달 지연, 프로젝트 계획의 복잡화, 그리고 지역 전체를 아우르는 장비 도입 접근 방식이 가져다주는 즉각적인 이점을 제한하는 요인이 될 수 있습니다.
부문 분석
2025년 남미 5G 기술 시장에서 하드웨어는 50.35%를 차지했습니다. 이는 서비스 및 소프트웨어 수익이 두드러지기 전에 통신사업자가 대량의 무선 장비를 필요로 했던 도입 초기 단계를 반영한 것입니다. 초기 구축 단계에서는 대규모 기지국, 안테나, 무선 유닛이 필요했으며, 통신사업자가 보다 고도화된 서비스 기능을 제공할 수 있게 되기 위해서는 커버리지 확대 계획에 따른 물리적 인프라 구축이 요구되었습니다. 브라질의 커버리지 의무가 이러한 장비 수요를 지원했습니다. 아르헨티나의 초기 도입 프로그램 또한 하드웨어 수요를 지원했습니다. 통신사업자가 OSS/BSS 시스템의 현대화를 추진함에 따라 소프트웨어의 중요성은 점점 더 커지고 있습니다. 이는 새로운 네트워크에서는 여러 기술 계층에 걸친 프로비저닝, 고객 지원, 과금 프로세스 및 서비스 보장의 연계가 필요하기 때문입니다. 클라우드 네이티브 네트워크 기능에도 소프트웨어에 대한 투자가 요구됩니다. 노키아의 ‘MantaRay SON’은 자동화된 네트워크 관리를 지원합니다. 따라서 통신사업자는 물리적 인프라 외에도 프로비저닝, 서비스 보장, 자동화 및 코어 네트워크 기능을 연계하는 시스템이 필요하므로 구성 요소의 조합은 무선 장비에만 국한되지 않게 되었습니다.
서비스 시장은 2026-2031년에 연평균 성장률(CAGR) 18.35%로 확대될 것으로 예측됩니다. 통신사업자는 도입, 최적화 및 관리형 운영에 관한 전문적인 지원을 필요로 하고 있습니다. 노키아와 TIM Brasil 간의 계약에는 AirScale 도입 및 MantaRay SON을 통한 자동화 서비스가 포함되어 있습니다. 또한 브라질 14개 주에 걸친 기업 솔루션 개발도 포함되어 있습니다. 독립형 네트워크에는 SIM 마이그레이션 및 코어 설정 작업이 필요합니다. 또한 무선에서 코어에 이르는 지연 시간 최적화도 요구됩니다. 오픈 RAN을 통해 하드웨어 인터페이스의 호환성이 향상됩니다. 따라서 초기 네트워크 도입이 완료된 후에도 고객은 호환 가능한 시스템, 운영의 연속성 및 기술 지원을 필요로 하므로, 서비스 제공과 소프트웨어 통합은 계약 가치 측면에서 더욱 중요해집니다.
2025년 남미 5G 기술 시장에서 Sub-6GHz 대역은 68.90%를 차지하고 있으며, 상업적·지역적 조건이 크게 다른 이 지역에서 커버리지와 실용적인 전파 전파가 우선시되고 있음이 부각되고 있습니다. 이 주파수 대역은 인구 밀집 도시와 농촌 지역에서 유용한 커버리지를 제공합니다. 이는 인구 밀집 대도시권, 외딴 지역의 지자체, 농촌 지역, 산악 지대, 그리고 커버리지 수요가 극히 다른 산업 지역 등 남미의 다양한 지역에 적합합니다. 브라질에서는 2021년 경매를 통해 3.5GHz 대역 주파수를 전국적으로 할당했습니다. Claro, Vivo, TIM이 전국적인 할당을 받았습니다. 또한 Anatel은 2026년 5월에 700MHz 대역 주파수 블록도 할당했습니다. 이 할당에는 서비스가 미흡한 지역 및 연방 고속도로에 대한 투자 의무가 포함되었습니다. 이러한 다층적인 주파수 대역 접근 방식은 대용량 오버레이가 보급되기 전의 커버리지를 확보하고, 사업자가 도심 지역을 넘어 서비스를 확장하는 동시에 인구 밀집 지역을 위한 추가 용량을 계획할 수 있게 해줍니다.
하이브리드 구성은 2026-2031년에 연평균 성장률(CAGR) 18.80%로 확대될 것으로 예측됩니다. 통신사업자들은 인구 밀집 지역에서 6GHz 미만의 매크로 커버리지와 밀리미터파(mmWave) 용량을 결합하고 있습니다. 경기장 및 기업 시설은 밀리파의 초기 사용 사례이며, 이러한 장소에는 다수의 사용자와 데이터 집약적인 산업 기능이 존재하므로 집중적인 용량 투자와 전문적인 네트워크 설계가 정당화됩니다. 2025년 6월 기준으로 상용화된 밀리파 지원 단말기는 150종 이상에 달했습니다. 2019년 말 기준 총 수는 21종이었습니다. GSMA의 추정에 따르면 2030년까지 각 시장에서 2GHz 중파 대역 주파수 대역이 필요할 것으로 예상됩니다. 따라서 칠레, 아르헨티나, 페루에서는 장기적인 용량 제약에 직면하게 될 것입니다. 하이브리드 네트워크는 각 주파수 대역의 전파 특성 및 용량 특성을 가장 효과적으로 활용할 수 있는 곳에서 사용할 수 있으므로, 커버리지와 집중된 트래픽 수요를 모두 충족시키는 실용적인 수단이 됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 5G 연혁과 진화
- 현재의 도입 사이클(선도자, 채택자, 후발자)
- 업계 밸류체인 분석
- 규제 상황 및 정책의 동향
- 기술 전망
- Porter's Five Forces 분석
- 5G와 Beyond 5G(6G 경로)
- 거시경제 요인이 시장에 미치는 영향
제5장 시장 규모와 성장 예측
- 컴포넌트별
- 주파수대별
- 용도별
- 최종사용자 산업별
- 네트워크 아키텍처별
- 국가별
- 브라질
- 아르헨티나
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson(Ericsson)
- Nokia Corporation
- Qualcomm Incorporated
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- Intel Corporation
- MediaTek Inc.
- Cisco Systems, Inc.
- NEC Corporation
- CommScope Holding Company, Inc.
- Apple Inc.
- Skyworks Solutions, Inc.
- Analog Devices, Inc.
- Juniper Networks, Inc.
- Mavenir plc
- Parallel Wireless, Inc.
- America Movil, S.A.B. de C.V.
- Telefonica Brasil S.A.
제7장 시장 기회와 향후 전망
KSAAccording to Mordor Intelligence, the South America 5G technology market size is projected to be USD 6.35 billion in 2025, USD 7.45 billion in 2026, and reach USD 15.99 billion by 2031, growing at a CAGR of 16.50% from 2026 to 2031.
South America 5G Technology Market Trends and Insights
Rising 5G Rollout Across Major South American Economies
Brazil's spectrum obligations have made 5G rollout a phased statutory requirement for operators, connecting license conditions to deployment deadlines and making network extension a formal part of the operating environment. Anatel requires service in 30% of municipalities below 30,000 residents by December 2026. The requirement rises to universal coverage by 2029. 5G had reached 1,966 municipalities by early 2026. The Ministry of Communications expects service to be available in more than 2,220 cities by the end of 2026. TIM Brasil approved Huawei and Nokia supply contracts for more than 6,500 4G and 5G sites during January 2026. These obligations support demand for radio access networks and fixed wireless access in locations with limited commercial appeal, while giving suppliers clearer timing for equipment deliveries, installation work, and service contracts.
Expanding Enterprise Demand for Low-Latency Connectivity
Enterprise deployment is moving from trials toward operational networks in mining, ports, energy, and manufacturing, where the commercial case rests on better monitoring, more dependable communications, automation, and site-specific network control. Nokia expanded its TIM Brasil partnership across 14 additional states in March 2026. The coverage reaches 42% of Brazil's population. The program supports network slicing, image analysis, voice recognition, and autonomous operations. Nokia uses Habrok Massive MIMO radios and NVIDIA AI-RAN computing in the deployment. Vale, Petrobras, Gerdau, AXIA Energia, and Flex have commissioned private networks in Brazil. Their activity makes private wireless connectivity a planned capital investment rather than an experimental technology. This demand gives the South America 5G technology market a path to recurring enterprise revenue, since industrial customers require deployment support, ongoing optimization, secure operations, and connectivity tailored to specific sites.
Uneven Spectrum Availability and Auction Complexity
South American spectrum rules create different rollout conditions across national markets, so equipment suppliers and operators face different auction schedules, licensing terms, spectrum availability, and technical conditions from one country to another. Brazil and Chile have moved earlier, while other countries remain at earlier stages. Chile was conducting a consultation on the remaining 3.5 GHz allocations in early 2026. Brazil also opened a public consultation on the 6 GHz band. These processes extend the period between spectrum planning and physical deployment. Each delay can postpone the availability of devices and enterprise service launches. Argentina, Peru, Ecuador, and Bolivia also apply different technical and procedural requirements. Vendors, therefore, need country-specific compliance work instead of standardized regional designs, which can slow procurement, complicate project planning, and limit the immediate benefits of a region-wide equipment approach.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Fixed Wireless Access for Broadband-Underserved Areas
- Telecom Virtualization and Cloud-Native Core Modernization
- Elevated Rural Backhaul and Fiber Deployment Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware accounted for 50.35% of the South America 5G technology market in 2025, reflecting the early rollout stage, when operators needed large volumes of radio equipment before service and software revenues could become more prominent. The first deployment phase required base stations, antennas, and radio units at scale, with coverage programs demanding physical infrastructure before operators can offer more advanced service capabilities. Brazilian coverage obligations sustained this equipment requirement. Argentina's early deployment program also supported demand for hardware. Software is becoming increasingly important as operators modernize OSS/BSS systems, because newer networks require coordinated provisioning, customer support, billing processes, and service assurance across multiple technology layers. Cloud-native network functions also require software investment. Nokia's MantaRay SON supports automated network management. The component mix is therefore moving beyond radio equipment alone, as operators need systems that coordinate provisioning, service assurance, automation, and core-network functions alongside physical infrastructure.
Services are projected to expand at an 18.35% CAGR from 2026 to 2031. Operators need specialist support for deployment, optimization, and managed operations. Nokia's TIM Brasil agreement includes AirScale installation and MantaRay SON automation services. It also includes enterprise solution development across 14 Brazilian states. Stand-alone networks require SIM migration and core configuration work. They also require radio-to-core latency optimization. Open RAN can make hardware interfaces more interchangeable. Service delivery and software integration, therefore, become more important to contract value, since customers need compatible systems, operational continuity, and technical support after the initial network installation is completed.
Sub-6 GHz accounted for 68.90% of the South America 5G technology market in 2025, underscoring the priority given to coverage and usable propagation across a region where commercial and geographic conditions vary widely. The band provides useful coverage in dense cities and rural areas. This suits South America's varied geography, which includes dense metropolitan areas, distant municipalities, rural communities, mountainous territory, and industrial locations with very different coverage needs. Brazil assigned 3.5 GHz spectrum nationally in its 2021 auction. Claro, Vivo, and TIM received national allocations. Anatel also awarded 700 MHz lots during May 2026. The awards included investment obligations for underserved locations and federal highways. This layered spectrum approach supports coverage before higher-capacity overlays become widespread, allowing operators to extend service beyond central urban areas while planning additional capacity for dense locations.
Hybrid configurations are projected to expand at an 18.80% CAGR from 2026 to 2031. Operators combine sub-6 GHz macro coverage with mmWave capacity in dense settings. Stadiums and enterprise locations are early use cases for mmWave, where large numbers of users or data-intensive industrial functions can justify focused capacity investment and specialized network design. More than 150 commercial mmWave-capable devices were available by June 2025. The total was 21 at the end of 2019. The GSMA estimates that each market will need 2 GHz of mid-band spectrum by 2030. Chile, Argentina, and Peru therefore face longer-term capacity constraints. Hybrid networks provide a practical way to match coverage and concentrated traffic demand, because each spectrum layer can be used where its propagation and capacity characteristics are most useful.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Spectrum Band
- Sub-6 GHz
- mmWave
- Hybrid (Sub-6 GHz and mmWave)
- By Application
- Enhanced Mobile Broadband (eMBB)
- Fixed Wireless Access (FWA)
- Massive Machine-Type Communications (mMTC)
- Ultra-Reliable Low-Latency Communications (URLLC)
- By End-User Industry
- Consumer
- Manufacturing
- Healthcare
- Automotive
- Energy and Utilities
- Media and Entertainment
- Public Safety and Defense
- By Network Architecture
- Stand-Alone (SA)
- Non-Stand-Alone (NSA)
- By Country
- Brazil
- Argentina
- Rest of South America
List of Companies Covered in this Report:
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson (Ericsson)
- Nokia Corporation
- Qualcomm Incorporated
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- Intel Corporation
- MediaTek Inc.
- Cisco Systems, Inc.
- NEC Corporation
- CommScope Holding Company, Inc.
- Apple Inc.
- Skyworks Solutions, Inc.
- Analog Devices, Inc.
- Juniper Networks, Inc.
- Mavenir plc
- Parallel Wireless, Inc.
- America Movil, S.A.B. de C.V.
- Telefonica Brasil S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising 5G Network Rollout Across Major South American Economies
- 4.2.2 Expanding Enterprise Demand for Low-Latency Connectivity
- 4.2.3 Growth in Fixed Wireless Access for Broadband Underserved Areas
- 4.2.4 Telecom Virtualization and Cloud-Native Core Modernization
- 4.2.5 Private 5G Adoption in Mining, Ports, and Industrial Corridors
- 4.2.6 Spectrum Refarming and New Auction Programs Supporting Capacity Expansion
- 4.3 Market Restraints
- 4.3.1 Uneven Spectrum Availability and High Auction Complexity
- 4.3.2 Elevated Rural Backhaul and Fiber Deployment Costs
- 4.3.3 Macroeconomic Pressure on Operator Capex and Device Affordability
- 4.3.4 Slow Monetization Beyond Consumer Mobile Broadband
- 4.4 5G Timeline and Evolution
- 4.5 Current Adoption Cycle (Forerunners, Adopters, and Laggards)
- 4.6 Industry Value Chain Analysis
- 4.7 Regulatory and Policy Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
- 4.10 5G and Beyond (6G Pathways)
- 4.11 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Spectrum Band
- 5.2.1 Sub-6 GHz
- 5.2.2 mmWave
- 5.2.3 Hybrid (Sub-6 GHz and mmWave)
- 5.3 By Application
- 5.3.1 Enhanced Mobile Broadband (eMBB)
- 5.3.2 Fixed Wireless Access (FWA)
- 5.3.3 Massive Machine-Type Communications (mMTC)
- 5.3.4 Ultra-Reliable Low-Latency Communications (URLLC)
- 5.4 By End-User Industry
- 5.4.1 Consumer
- 5.4.2 Manufacturing
- 5.4.3 Healthcare
- 5.4.4 Automotive
- 5.4.5 Energy and Utilities
- 5.4.6 Media and Entertainment
- 5.4.7 Public Safety and Defense
- 5.5 By Network Architecture
- 5.5.1 Stand-Alone (SA)
- 5.5.2 Non-Stand-Alone (NSA)
- 5.6 By Country
- 5.6.1 Brazil
- 5.6.2 Argentina
- 5.6.3 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Huawei Technologies Co., Ltd.
- 6.4.2 Telefonaktiebolaget LM Ericsson (Ericsson)
- 6.4.3 Nokia Corporation
- 6.4.4 Qualcomm Incorporated
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 ZTE Corporation
- 6.4.7 Intel Corporation
- 6.4.8 MediaTek Inc.
- 6.4.9 Cisco Systems, Inc.
- 6.4.10 NEC Corporation
- 6.4.11 CommScope Holding Company, Inc.
- 6.4.12 Apple Inc.
- 6.4.13 Skyworks Solutions, Inc.
- 6.4.14 Analog Devices, Inc.
- 6.4.15 Juniper Networks, Inc.
- 6.4.16 Mavenir plc
- 6.4.17 Parallel Wireless, Inc.
- 6.4.18 America Movil, S.A.B. de C.V.
- 6.4.19 Telefonica Brasil S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


