

|
시장보고서
상품코드
2154990
유럽의 5G 기술 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe 5G Technology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
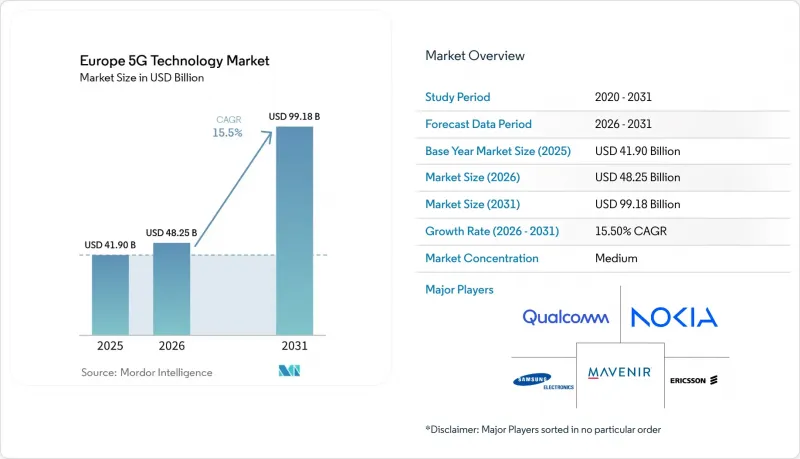
에 따르면 유럽의 5G 기술 시장 규모는 2025년 419억 달러에서 2026년에는 482억 5,000만 달러로 확대하며, 2031년까지 991억 8,000만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 15.5%로 성장할 것으로 전망되고 있습니다.
유럽 5G 기술 시장의 동향 및 인사이트
유럽 주요 경제권에서 5G 독립형 네트워크 구축이 진행 중입니다.
보다폰 스리는 10년간의 네트워크 투자 계획에 110억 파운드(148억 5,000만 달러)를 투자하기로 결정했습니다. 여기에는 영국내 17,000곳 이상의 기지국을 대상으로 에릭슨 및 노키아와 체결한 공급 계약에 대한 20억 파운드(27억 달러)가 포함되어 있습니다. 2025년 9월에 체결된 이 계약들을 통해 2034년까지 영국 인구의 99% 이상에게 5G 독립형(SA) 통신 서비스 지역을 확대하겠다는 계획의 핵심으로 독립형 방식의 구축이 자리 잡았습니다. 유럽의 5G 기술 시장은 주요 통신사업자들이 제한적인 시범 운영에서 벗어나, 공통 기술 표준, 확립된 공급업체, 장기적인 약속, 그리고 초기 네트워크 커버리지에서 널리 이용 가능한 독립형(SA) 기능에 이르는 명확한 로드맵을 갖춘 재현 가능한 전국 규모의 프로그램으로 전환함으로써 혜택을 볼 것입니다. 독립형 네트워크는 네트워크 슬라이싱, 사설 연결, 그리고 표준적인 최선 노력(best-effort) 방식의 모바일 액세스가 아닌 전용 성능 특성을 활용하는 기업용 서비스 패키지의 기술적 기반을 제공합니다. 이러한 기능은 기본적인 모바일 커버리지만으로는 통신사업자가 자사의 서비스를 차별화하거나, 고객이 고급 서비스에 대해 요금을 지불해야 할 이유를 설명할 여지가 제한적이기 때문에 중요한 의미를 지닙니다. 유럽연합 집행위원회는 2026년 1월 21일, ‘디지털 네트워크법’을 제안하며 주파수 대역 관리 및 국경을 넘는 인가에 관한 조치를 포함시켰습니다.
산업 제조 클러스터에서의 프라이빗 5G 수요 증가
프라이빗 5G는 2025-2026년에 특히 대규모로 가동중인 생산 거점 전체에서 예측 가능한 무선 성능이 요구되는 산업 환경에서 고립된 시험 단계에서 실제 운용 단계로 전환되었습니다. 지멘스는 2026년 4월, 벨기에, 핀란드, 프랑스, 노르웨이, 폴란드, 영국을 추가하여 산업용 프라이빗 5G 제공 대상을 15개국으로 확대했습니다. 이러한 제공 범위 확대를 통해 각 거점마다 개별적인 솔루션을 설계하는 대신, 여러 시설에 공통된 네트워크 설계를 적용하고자 하는 기업을 지원합니다. 유럽의 5G 기술 시장에서는 다양한 설비, 생산 단계, 안전 요건을 갖춘 현장을 포함하여, 동일한 운영 환경 내에서 기능해야 하는 자동화, 머신 비전, 이동 로봇 및 연결된 비즈니스 시스템을 프라이빗 시스템이 지원함으로써 지속적인 수요가 발생하고 있습니다. 3GPP Release 16에서는 통제된 조건 하에서 1밀리초에 가까운 지연 시간과 높은 신뢰성이 요구되는 까다로운 사용 사례를 위한 URLLC 기능이 정의되었습니다. 이러한 요구 사항에 따라 모바일 기기, 센서, 생산 공정에 일관된 성능이 요구되는 경우, 제조 현장에서는 고정식 산업용 연결을 프라이빗 셀룰러 네트워크로 대체하거나 이를 보완하는 방안을 고려할 수 있습니다. 재현 가능한 도입 계획을 통해 중규모 산업 시설에서의 프라이빗 5G 도입에 필요한 노력을 줄이고, 거점 간 확장을 보다 현실적으로 만들 수 있습니다.
고밀도 미드밴드 및 밀리미터파 인프라의 높은 자본 집약도
GSMA Intelligence의 추산에 따르면 유럽에서는 2026-2036년에 4,750억 유로(5,368억 달러)의 모바일 투자가 필요할 것으로 예상됩니다. 이 중 통신사업자가 활용할 수 있는 자금은 2,700억 유로(3,051억 달러)로 추산되며, 2,000억 유로(2,331억 9,000만 달러) 이상의 자금 부족이 발생할 것으로 보입니다. GSMA에 따르면 필요한 지출의 거의 절반은 주요 교통 노선을 따라 구축되는 5G 관련 사업에 할당될 예정입니다. 이러한 지역에서는 커버리지의 연속성과 용량 수요를 충족하기 위해 더 대규모의 네트워크 인프라가 필요합니다. 고밀도 중파대 및 밀리파 네트워크는 광범위한 6GHz 미만 매크로 커버리지에 비해 사이트 간 간격을 좁히고 전용 무선 장비가 필요하므로 구축 비용과 사이트 관련 비용 모두 증가합니다. 이러한 요건으로 인해 네트워크 경제성이 낮은 시장이나 대용량 트래픽 수요가 아직 입증되지 않은 지역에서는 투자 부담이 특히 커집니다. 통신사업자는 자본이 제한적인 경우, 비독립형(NSA) 네트워크의 운영 기간을 연장하고 가장 확실한 수익을 기대할 수 있는 기지국만을 우선적으로 선택할 가능성이 있습니다. 이러한 결정은 완전한 독립형(SA) 기능과 관련된 소프트웨어 및 서비스에 대한 지출을 지연시켜, 기본적인 커버리지에서 고급 서비스 제공으로의 전환을 늦출 우려가 있습니다.
부문 분석
2025년 유럽 5G 기술 시장에서 하드웨어는 시장 점유율의 44.85%를 차지했으나, 서비스 부문은 2031년까지 연평균 성장률(CAGR) 17.41%로 확대될 것으로 예측됩니다. 하드웨어 수요는 5G 구축의 물리적 액세스 계층을 구성하는 매시브 MIMO 무선 유닛, 기지국 및 원격 무선 헤드(RRH)에 계속해서 집중되고 있습니다. 이러한 자산은 유럽 통신사업자의 전체 네트워크에서 서브 6GHz 대역의 밀도 향상 프로그램을 지원하며, 소비자의 데이터 사용, 고정 무선 액세스 및 기업 트래픽이 동일한 무선 인프라를 공유함으로써 수요가 증가하는 트래픽이 많은 지역에서 용량을 확대하는 데 필요한 장비를 제공합니다. 또한 통신사업자가 커버리지를 확대하거나, 기지국을 업그레이드하거나, 기업 거점을 위한 전용 장비를 설치하는 경우에도 하드웨어는 여전히 필수적입니다. 따라서 유럽의 5G 기술 부문은 지출 구성에 변화가 나타나기 시작했음에도 불구하고 여전히 대규모 장비 기반을 유지하고 있습니다.
다년간의 네트워크 계획에서 클라우드 네이티브 도입, 관리형 무선 운영, 네트워크-어즈-어-서비스(NaaS) 계약이 보편화됨에 따라 서비스의 중요성이 높아질 것으로 예상됩니다. 이러한 활동은 초기 장비 구매에 그치지 않고, 설계, 통합, 최적화, 지원, 운영 관리까지 포함하는 지속적인 계약을 창출합니다. 오픈 RAN은 소프트웨어가 일부 전용 하드웨어 기능을 대체할 수 있고, 여러 공급업체 간의 보다 긴밀한 협력을 필요로 하므로 이러한 변화를 지원하고 있습니다. 또한 통신사업자가 레거시 코어 프로세스를 대체하고 공용 네트워크와 기업 구축을 병행하여 관리함에 따라 소프트웨어는 네트워크 성능과 상용 서비스를 연결하는 오케스트레이션, 가상 네트워크 기능(VNF), 운영 지원 시스템(OSS), 비즈니스 지원 시스템(BSS)도 지원하고 있습니다. 따라서 유럽의 5G 기술 시장에서는 5G 커버리지 구축 초기 단계에 비해 하드웨어, 소프트웨어 및 서비스에 대한 요구 사항의 구성이 더욱 다양해지고 있습니다.
2025년 유럽 5G 기술 시장에서 Sub-6GHz 대역은 66.48%를 차지하고 있으며, 이는 통신사업자의 포트폴리오에서 주요 용량 계층으로서의 역할을 반영합니다. n78 대역은 일관된 네트워크 설계로 광범위한 지역을 지원할 수 있으므로 이러한 커버리지 및 용량 전략의 중심적인 역할을 수행해 왔습니다. 이 대역은 도달 범위와 용량의 균형 덕분에 도시, 교외, 그리고 많은 농촌 지역에 걸친 광범위한 구축에 적합합니다. 통신사업자는 이 주파수 대역을 활용함으로써, 더 높은 주파수 대역에 필요한 고밀도 기지국망이나 전용 장비에 의존하지 않고도 5G 서비스 제공 범위를 확대할 수 있습니다. 이 주파수 대역은 대부분의 전국적 5G 네트워크 계획과 그 이후의 보다 목표가 명확한 용량 확충에 있으며, 여전히 실용적인 기반이 되고 있으며, 통신사업자는 국지적인 고주파 인프라에 막대한 자원을 투입하기 전에 광범위한 서비스 제공을 우선시할 수 있습니다.
하이브리드(6GHz 미만 및 밀리미터파) 구성은 2031년까지 연평균 성장률(CAGR) 17.98%로 확대될 것으로 예측됩니다. 이러한 구성은 행사장, 기업 캠퍼스, 방송 시설 등 트래픽이 집중되고 더 높은 국소적 처리량이 필요한 장소에서 밀리미터파를 통해 용량을 추가합니다. 노키아와 EOLO는 2024년 12월 이탈리아에서 유럽 최초의 5G 독립형 밀리미터파 네트워크를 구축했습니다. 유럽의 5G 기술 시장에서는 신뢰할 수 있는 서브 6GHz 대역 커버리지와 특정 거점에서의 매우 높은 국소 용량이 공존해야 하는 하이브리드 네트워크를 활용할 수 있습니다. 유럽내 26GHz 대역의 주파수 조화는 이러한 표적형 구축을 위한 주파수 기반을 제공할 뿐만 아니라, 통신사업자에게 장비 계획에 대한 공통 기준을 제시합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 5G 연혁과 진화
- 현재의 도입 사이클(선도자, 채택자, 후발자)
- 업계 밸류체인 분석
- 규제 상황 및 정책의 동향
- 기술 전망
- Porter's Five Forces 분석
- 5G와 Beyond 5G(6G 경로)
- 거시경제 요인이 시장에 미치는 영향
제5장 시장 규모와 성장 예측
- 컴포넌트별
- 주파수대별
- 용도별
- 최종사용자 산업별
- 네트워크 아키텍처별
- 국가별
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 러시아
- 기타 유럽 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson(Ericsson)
- Nokia Corporation
- Qualcomm Incorporated
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- Intel Corporation
- MediaTek Inc.
- Cisco Systems, Inc.
- NEC Corporation
- Fujitsu Limited
- CommScope Holding Company, Inc.
- Vodafone Group plc
- Skyworks Solutions, Inc.
- Analog Devices, Inc.
- Juniper Networks, Inc.
- Mavenir plc
- Parallel Wireless, Inc.
- Rohde and Schwarz GmbH and Co. KG
- Deutsche Telekom AG
제7장 시장 기회와 향후 전망
KSAAccording to Mordor Intelligence, the Europe 5G technology market size is expected to increase from USD 41.90 billion in 2025 to USD 48.25 billion in 2026 and reach USD 99.18 billion by 2031, growing at a CAGR of 15.5% over 2026-2031.
Europe 5G Technology Market Trends and Insights
Ongoing 5G Standalone Network Rollouts Across Major European Economies
VodafoneThree committed GBP 11 billion (USD 14.85 billion) to a 10-year network investment plan, including GBP 2 billion (USD 2.7 billion) in supply agreements with Ericsson and Nokia for more than 17,000 United Kingdom sites. The September 2025 agreements placed standalone deployment at the center of a plan intended to extend 5G standalone coverage to more than 99% of the United Kingdom population by 2034. The European 5G technology market benefits when large operators move from limited trials to repeatable national programs with common technical standards, established suppliers, long-term commitments, and a clear route from initial network coverage to widely available standalone capability. Standalone networks provide the technical base for network slicing, private connectivity, and enterprise service packages that use dedicated performance characteristics rather than standard best-effort mobile access. Those capabilities matter because basic mobile coverage alone gives operators limited scope to differentiate their offerings or to explain why a customer should pay for an advanced service. The European Commission proposed the Digital Networks Act on January 21, 2026, with measures covering spectrum management and cross-border authorizations.
Rising Private 5G Demand in Industrial Manufacturing Clusters
Private 5G moved from isolated testing to operational deployment during 2025 and 2026, particularly in industrial settings that require predictable wireless performance across large, active production sites. Siemens expanded its industrial private 5G offer to 15 countries in April 2026, adding Belgium, Finland, France, Norway, Poland, and the United Kingdom. This wider availability supports companies that want to apply a common network design across multiple facilities rather than designing a separate solution for each location. The European 5G technology market gains recurring demand when private systems support automation, machine vision, mobile robots, and connected business systems that must work within the same operational environment, including sites with varied equipment, production stages, and safety requirements. 3GPP Release 16 defined URLLC capabilities for demanding use cases that require near-1 ms latency and high reliability under controlled conditions. These requirements explain that manufacturing sites may replace or supplement fixed industrial connections with private cellular networks when mobile equipment, sensors, and production processes require consistent performance. Replicable deployment plans can reduce the effort needed to introduce private 5G at midsize industrial sites and make cross-site deployment more practical.
High Capital Intensity of Dense Mid-Band and mmWave Infrastructure
GSMA Intelligence estimated that Europe requires EUR 475 billion (USD 536.8 billion) in mobile investment from 2026 to 2036. It estimated an operator-accessible pool of EUR 270 billion (USD 305.1 billion), leaving over EUR 200 billion (USD 233.19 billion). GSMA Nearly half of the required spending relates to 5G along major transport routes, where coverage continuity and capacity demand require more extensive network infrastructure. Dense mid-band and mmWave networks need closer site spacing and specialized radio equipment than broad sub-6 GHz macro coverage, adding both deployment and site-related costs. This requirement makes the investment burden particularly difficult in markets with weaker network economics and in areas where high-capacity traffic demand is not yet proven. Operators may keep non-standalone networks in service longer when capital is constrained and prioritize only the sites with the clearest return. That decision can delay the software and services spending associated with full standalone capabilities and slow the transition from basic coverage to advanced service delivery.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Fixed Wireless Access Adoption in Underserved European Broadband Markets
- Open RAN and Virtualized Network Adoption to Improve Vendor Flexibility
- Slow Enterprise Monetization of Advanced 5G Use Cases
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware accounted for 44.85% of the European 5G technology market share in 2025, while services are projected to expand at a 17.41% CAGR through 2031. Hardware demand remains centered on massive MIMO radio units, base stations, and remote radio heads that form the physical access layer of 5G deployment. These assets support sub-6 GHz densification programs across European operator networks and provide the equipment needed to add capacity in high-traffic areas, where demand increases as consumer data use, fixed wireless access, and enterprise traffic share the same radio infrastructure. Hardware also remains necessary when operators extend coverage, upgrade sites, or install specialized equipment for enterprise locations. Europe's 5G technology sector, therefore, retains a large equipment base even as the composition of spending begins to change.
Services are expected to gain importance as cloud-native deployment, managed radio operations, and network-as-a-service arrangements become more common across multi-year network programs. These activities create recurring engagements that extend beyond the original equipment purchase and encompass design, integration, optimization, support, and operational management. Open RAN supports this shift because software can replace some proprietary hardware functions and requires closer coordination between multiple suppliers. Software also supports orchestration, virtual network functions, operations support systems, and business support systems that connect network performance with commercial delivery as operators replace legacy core processes and manage public networks alongside enterprise deployments. The Europe 5G technology market, therefore, has a broader mix of hardware, software, and services requirements than in the initial phase of 5G coverage deployment.
Sub-6 GHz accounted for 66.48% of the European 5G technology market in 2025, reflecting its role as the primary capacity layer in operator portfolios. Band n78 has been a central part of this coverage and capacity strategy because it can serve a wide range of locations with a consistent network design. Its balance of reach and capacity makes it suitable for broad deployment across urban, suburban, and many rural areas. Operators can use this band to expand 5G availability without relying on the dense site grids and specialized equipment needed for higher frequencies. It remains the practical base for most nationwide 5G network plans and for later additions of more targeted capacity, allowing operators to prioritize broad availability before committing major resources to localized high-frequency infrastructure.
Hybrid (sub-6 GHz and mmWave) configurations are projected to expand at a 17.98% CAGR through 2031. These configurations add mmWave capacity where traffic is concentrated at venues, enterprise campuses, and broadcast locations that need higher local throughput. Nokia and EOLO deployed Europe's first 5G standalone mmWave network in Italy in December 2024. The European 5G technology market can use hybrid networks in which dependable sub-6 GHz coverage must coexist with very high local capacity at specific sites. European harmonization of the 26 GHz band provides a spectrum basis for these targeted deployments and gives operators a common reference for equipment planning.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Spectrum Band
- Sub-6 GHz
- mmWave
- Hybrid (Sub-6 GHz and mmWave)
- By Application
- Enhanced Mobile Broadband (eMBB)
- Fixed Wireless Access (FWA)
- Massive Machine-Type Communications (mMTC)
- Ultra-Reliable Low-Latency Communications (URLLC)
- By End-User Industry
- Consumer
- Manufacturing
- Healthcare
- Automotive
- Energy and Utilities
- Media and Entertainment
- Public Safety and Defense
- By Network Architecture
- Stand-Alone (SA)
- Non-Stand-Alone (NSA)
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson (Ericsson)
- Nokia Corporation
- Qualcomm Incorporated
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- Intel Corporation
- MediaTek Inc.
- Cisco Systems, Inc.
- NEC Corporation
- Fujitsu Limited
- CommScope Holding Company, Inc.
- Vodafone Group plc
- Skyworks Solutions, Inc.
- Analog Devices, Inc.
- Juniper Networks, Inc.
- Mavenir plc
- Parallel Wireless, Inc.
- Rohde and Schwarz GmbH and Co. KG
- Deutsche Telekom AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ongoing 5G Standalone Network Rollouts Across Major European Economies
- 4.2.2 Rising Private 5G Demand in Industrial Manufacturing Clusters
- 4.2.3 Expanding Fixed Wireless Access Adoption in Underserved European Broadband Markets
- 4.2.4 Open RAN and Virtualized Network Adoption to Improve Vendor Flexibility
- 4.2.5 Network Slicing Requirements From Enterprise and Public Sector Use Cases
- 4.2.6 Cross-Border Spectrum Harmonization Supporting Pan-European Deployment Efficiency
- 4.3 Market Restraints
- 4.3.1 High Capital Intensity of Dense Mid-Band and mmWave Infrastructure
- 4.3.2 Slow Enterprise Monetization of Advanced 5G Use Cases
- 4.3.3 Spectrum Fragmentation and Varying National Licensing Conditions
- 4.3.4 Elevated Energy Use and Site-Level Sustainability Pressures
- 4.4 5G Timeline and Evolution
- 4.5 Current Adoption Cycle (Forerunners, Adopters, and Laggards)
- 4.6 Industry Value Chain Analysis
- 4.7 Regulatory and Policy Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
- 4.10 5G and Beyond (6G Pathways)
- 4.11 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Spectrum Band
- 5.2.1 Sub-6 GHz
- 5.2.2 mmWave
- 5.2.3 Hybrid (Sub-6 GHz and mmWave)
- 5.3 By Application
- 5.3.1 Enhanced Mobile Broadband (eMBB)
- 5.3.2 Fixed Wireless Access (FWA)
- 5.3.3 Massive Machine-Type Communications (mMTC)
- 5.3.4 Ultra-Reliable Low-Latency Communications (URLLC)
- 5.4 By End-User Industry
- 5.4.1 Consumer
- 5.4.2 Manufacturing
- 5.4.3 Healthcare
- 5.4.4 Automotive
- 5.4.5 Energy and Utilities
- 5.4.6 Media and Entertainment
- 5.4.7 Public Safety and Defense
- 5.5 By Network Architecture
- 5.5.1 Stand-Alone (SA)
- 5.5.2 Non-Stand-Alone (NSA)
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Russia
- 5.6.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Huawei Technologies Co., Ltd.
- 6.4.2 Telefonaktiebolaget LM Ericsson (Ericsson)
- 6.4.3 Nokia Corporation
- 6.4.4 Qualcomm Incorporated
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 ZTE Corporation
- 6.4.7 Intel Corporation
- 6.4.8 MediaTek Inc.
- 6.4.9 Cisco Systems, Inc.
- 6.4.10 NEC Corporation
- 6.4.11 Fujitsu Limited
- 6.4.12 CommScope Holding Company, Inc.
- 6.4.13 Vodafone Group plc
- 6.4.14 Skyworks Solutions, Inc.
- 6.4.15 Analog Devices, Inc.
- 6.4.16 Juniper Networks, Inc.
- 6.4.17 Mavenir plc
- 6.4.18 Parallel Wireless, Inc.
- 6.4.19 Rohde and Schwarz GmbH and Co. KG
- 6.4.20 Deutsche Telekom AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


