

|
시장보고서
상품코드
2156867
미국의 의약품 냉장 체인 공수 물류 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Pharmaceutical Cold Chain Air Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
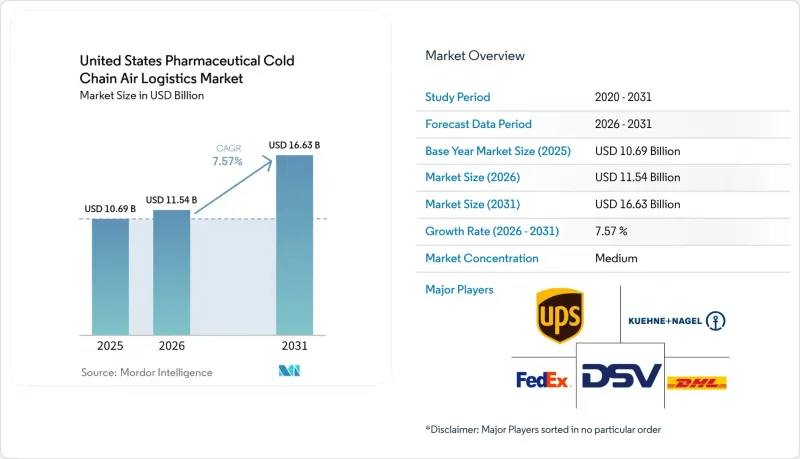
에 따르면 미국의 의약품 콜드체인 항공 물류 시장 규모는 2025년에 106억 9,000만 달러로 평가되며, 2026년 115억 4,000만 달러에서 2031년까지 166억 3,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 7.57%에 달할 전망입니다.
이러한 성장은 온도 관리가 필요한 의약품 파이프라인의 확대와 환자에게 더 가까운 곳에서의 유통 모델로의 전환을 반영하고 있습니다. 이 보고서는 온도 범위(냉장, 냉동, 상온, 초저온), 의약품 제품 유형(저분자 의약품, 생물제제, 전문 의약품, 세포·유전자 치료, 동물용 의약품, 기타), 출하 흐름(국내, 국제) 및 지역(북동부, 남동부, 중서부, 남서부, 서부)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국 의약품 콜드체인 항공 물류 시장의 동향 및 인사이트
생물제제 및 전문 의약품 운송량 증가
생물제제는 관리된 운송과 문서화된 출하 절차가 필요하므로 미국 의약품 콜드체인 항공 물류 시장의 비용 구조를 변화시키고 있습니다. CDER는 2025년에 12개의 생물제제를 포함한 46개의 신약을 승인했으며, CDER와 CBER를 합친 신규 승인 건수는 58건에 달했습니다. 각 제품의 출시에는 상업적 유통 개시 전에 검증된 운송 경로를 거쳐야 하므로, 운송 적격성 평가 작업이 발생합니다. 따라서 미국의 의약품 콜드체인 항공 물류 시장은 화물 운송 자체와 신제품에 수반되는 적격성 확인 작업 모두로부터 수요를 얻고 있습니다. 2025년 FDA 승인에는 10개의 참조 제품에 대한 18개의 바이오시밀러가 포함되었습니다. 개별 바이오시밀러 제조업체는 자체적인 적격 포장 및 운송업체를 마련해야 하므로, 하나의 오리지널 의약품 프로그램 하에서 화물을 통합하는 대신, 활성 화물 운송 계약의 수가 증가하게 됩니다.
세포·유전자 치료의 상용화
세포·유전자 치료는 임상 단계에서 상업적 유통 단계로 전환되고 있으며, 미국 의약품 콜드체인 항공 물류 시장에서 가장 까다로운 화물 범주로 자리 잡고 있습니다. Cryoport사는 2026년 3월 31일 기준으로 상업적으로 승인된 21개의 세포·유전자 치료제 및 766건의 글로벌 임상 시험을 지원했다고 보고했습니다. 2026년 8월 ‘GENGLYCOS’와 2026년 7월 ‘TREGZI’의 FDA 승인으로 인해 인증된 치료 센터로의 전문적인 유통이 필요한 치료제가 추가되었습니다. 자가 유래 치료의 경우, 환자의 세포를 병원에서 제조 거점으로 운송한 후, 다시 동일한 의료 시설로 반환해야 합니다. 이러한 왕복 운송으로 인해 신원 관리, 시기, 그리고 온도 관리가 운송 과정에서 매우 중요해집니다. -150°C 이하에서 작동하는 액체 질소 증기 시퍼는 UN 1977에 관한 IATA 위험물 규제의 대상이 되며, 이로 인해 운송업체 선택의 폭이 제한되고 취급 요건이 엄격해집니다.
높은 검증, 포장 및 온도 관리 비용
검증 요건으로 인해 운송량에 관계없이 의약품 콜드체인 항공 운송 경로에는 일정한 최저 비용이 설정되어 있습니다. 21 CFR Part 211.142 및 211.150에 따라 제조업체 및 유통업체는 보관 및 유통 과정에서 의약품의 동일성, 효능, 품질 및 순도를 보호하기 위한 서면 절차를 유지해야 합니다. 미국 의약품 콜드체인 항공 물류 시장에서는 계절별 운송 경로의 적합성 평가, 포장 성능 및 문서화된 운송 절차를 고려해야 합니다. USP 일반장 1079에는 의약품의 적절한 보관 및 유통에 관한 기준이 규정되어 있으며, 공식적인 온도 관리 프로세스가 권장됩니다. 액티브 컨테이너나 인증된 장비는 지속적인 인증 비용 및 운영 비용의 증가로 이어집니다. 이러한 요건은 소량이지만 고가의 치료제 운송을 관리하는 소규모 공급업체나 후원사에게 더 큰 부담이 됩니다.
부문 분석
2025년, 상온 운송은 시장 점유율의 46.62%를 차지하며 미국 의약품 콜드체인 항공 물류 시장에서 가장 큰 비중을 차지했습니다. 이 범주에는 관리된 상온 요건이 요구되는 GLP-1 주사제나, 연장된 상온 프로파일을 가진 경구용 전문 의약품이 포함됩니다. 이러한 운송량의 증가는 공항 화물 시설 및 취급 프로세스에 대한 투자를 지원하고 있습니다. 또한 이러한 투자는 동일한 운송 경로를 이용하는 특수 화물의 운송도 지원할 수 있습니다. 냉장 제품의 경우, 많은 생물제제 및 백신에서 엄격한 취급 관리가 요구됩니다. FDA 자료에는 승인된 의약품에 있으며, 적절한 유통 조건의 중요성이 설명되어 있습니다. 또한 제품의 안정성을 위해 더 낮은 온도에서의 보관이 필요한 경우, 냉동 제품도 여전히 중요한 위치를 차지하고 있습니다.
미국 의약품 콜드체인 항공 물류 시장에서 초저온 제품 및 극저온 제품 시장 규모는 2026-2031년에 연평균 성장률(CAGR) 11.55%로 확대될 것으로 예측됩니다. 이 성장 속도는 다른 온도 범주를 상회하고 있습니다. 세포 치료 및 유전자 치료가 이러한 수요의 주요 요인으로 작용하고 있습니다. 그 대부분은 -150°C 이하의 온도에서 액체 질소 증기를 이용한 운송이 필요하기 때문입니다. IATA는 UN 1977로 지정된 액체 질소의 운송을 특정 취급 규정을 포함한 위험물 규정에 따라 관리하고 있습니다. 성장은 활발한 컨테이너 구역을 갖추고, 지상에서 대기 중인 냉장 설비를 관리할 수 있는 인증된 게이트웨이에 집중될 전망입니다. 이러한 역량을 갖추지 못한 공항은 첨단 치료제 운송 경로에서 수행할 수 있는 역할이 제한적입니다. 이처럼 운송이 집중됨에 따라 인프라의 질은 미국 의약품 콜드체인 항공 물류 시장에서 중요한 요소가 됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요와 의약품 콜드체인 항공화물 물류의 중요성
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- 규제 상황
- 기술 전망
- 주요 의약품 항공화물 허브공항과 인프라
- 의약품의 수출 입동향과 주요 무역 루트
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 온도 범위별
- 의약품 제품 유형별
- 출하 동향별
- 지역별
- 북동
- 남동
- 중서부
- 남서부
- 서부
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- United Parcel Service, Inc.(UPS Healthcare, including Marken)
- FedEx Corporation
- DHL Group
- Kuehne+Nagel International AG
- DSV A/S
- CEVA Logistics(CMA CGM Group)
- GEODIS
- World Courier(Cencora, Inc.)
- Cryoport, Inc.
- AIT Worldwide Logistics, Inc.
- JAS Worldwide
- Biocair(Geopost)
- Nippon Express Holdings, Inc.(NX Group)
- Expeditors International of Washington, Inc.
- Hellmann Worldwide Logistics SE & Co. KG
- Yusen Logistics Co., Ltd
- Kintetsu World Express, Inc.
- A.P. Moller-Maersk A/S
- Crane Worldwide Logistics
- Rhenus Group
- DACHSER SE
- Scan Global Logistics A/S
- GXO Logistics, Inc.
- XPO, Inc.
제7장 시장 기회와 향후 전망
제8장 부록
KSA 26.10.29According to Mordor Intelligence, the United States pharmaceutical cold chain air logistics market size was valued at USD 10.69 billion in 2025 and estimated to grow from USD 11.54 billion in 2026 to reach USD 16.63 billion by 2031, at a CAGR of 7.57% during the forecast period (2026-2031).
The expansion reflects a larger pipeline of temperature-sensitive medicines and a distribution model that is moving closer to patients. This report is Segmented by Temperature Range (Chilled, Frozen, Ambient, Deep-Frozen/Ultra-Low), by Pharmaceutical Product Type (Small-Molecule, Biological, Specialty, Cell and Gene Therapies, Veterinary, Other), by Shipment Flow (Domestic, International), and by Region (Northeast, Southeast, Midwest, Southwest, West). The Market Forecasts are Provided in Terms of Value (USD).
United States Pharmaceutical Cold Chain Air Logistics Market Trends and Insights
Biologics and Specialty-Pharmaceutical Shipment Growth
Biologics are reshaping the cost structure of the United States pharmaceutical cold chain air logistics market because they need controlled transport and documented release procedures. CDER approved 46 novel drugs during 2025, including 12 biologics, while the combined number of novel approvals across CDER and CBER reached 58. Each launch creates transport qualification work because the product must move through a validated lane before commercial distribution begins. The United States pharmaceutical cold chain air logistics market, therefore, gains demand from both shipment movement and the qualification work that accompanies a new product. FDA approvals included 18 biosimilars for 10 reference products in 2025. Separate biosimilar manufacturers need their own qualified packaging and carrier arrangements, which increases the number of active freight relationships rather than combining freight under one originator program.
Cell and Gene Therapy Commercialization
Cell and gene therapies are moving from clinical activity into commercial distribution and have become the most demanding cargo category in the United States pharmaceutical cold chain air logistics market. Cryoport reported support for 21 commercially approved cell and gene therapies and 766 global clinical trials as of March 31, 2026. FDA approvals of GENGLYCOS in August 2026 and TREGZI in July 2026 added therapies that need specialized distribution to certified treatment centers. Autologous therapies require patient cells to travel from a hospital to a manufacturing site and then return to the same care location. That two-way movement makes identity control, timing, and temperature performance central to the shipment process. Liquid nitrogen vapor shippers operating below -150 °C are subject to IATA dangerous goods requirements for UN 1977, which limit carrier options and increase handling requirements.
High Validation, Packaging, and Temperature-Control Costs
Validation requirements establish a cost floor for pharmaceutical cold-chain air lanes, regardless of shipment volume. Under 21 CFR Part 211.142 and 211.150, manufacturers and distributors must maintain written procedures that protect a drug product's identity, strength, quality, and purity during storage and distribution. The United States pharmaceutical cold chain air logistics market must account for seasonal lane qualification, packaging performance, and documented transport procedures. USP General Chapter 1079 provides good storage and distribution practices for drug products and supports formal temperature-control processes. Active containers and qualified equipment add recurring certification and operating costs. These requirements are harder to absorb for smaller providers and sponsors managing low-volume, high-value therapy shipments.
Other drivers and restraints analyzed in the detailed report include:
- Direct-to-Patient and Specialty-Pharmacy Fulfillment
- Clinical-Trial Decentralization and Patient-Specific Shipments
- Temperature Excursion, Delay, and Product-Disposal Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ambient shipments held 46.62% of the market share in 2025, the largest position within the United States pharmaceutical cold chain air logistics market. This category includes GLP-1 injectables with controlled room-temperature requirements and oral specialty medicines with extended room-temperature profiles. Their high volume supports investment in airport cargo facilities and handling processes. That investment can also support specialized cargo moving along the same corridors. Chilled products require close handling control for many biologics and vaccines. FDA materials describe the importance of proper distribution conditions for approved drug products. Frozen products also remain important where product stability calls for lower temperature exposure.
The United States pharmaceutical cold chain air logistics market size for deep-frozen and ultra-low products is forecast to increase at an 11.55% CAGR between 2026 and 2031. This pace exceeds that of the other temperature categories. Cell and gene therapies are the main source of this demand because many require liquid nitrogen vapor shipment at temperatures below -150 °C. IATA treats UN 1977 liquid nitrogen shipments under dangerous goods rules that include specific handling controls. Growth is likely to concentrate at certified gateways with active container areas and the ability to manage cold equipment during ground dwell. Airports without these capabilities have a limited role in advanced therapy lanes. This channeling of traffic makes infrastructure quality a material factor in the United States pharmaceutical cold chain air logistics market.
Complete Report Scope:
- By Temperature Range
- Chilled (0-5 °C)
- Frozen (-18-0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (More than -20 °C)
- By Pharmaceutical Product Type
- Small-Molecule Pharmaceuticals
- Branded Pharmaceuticals
- Over-the-Counter (OTC) Pharmaceuticals
- Generic Pharmaceuticals
- Biological Pharmaceuticals (Biologics, Biosimilars, Vaccines, and Blood-Derived Medicinal Products)
- Specialty Pharmaceuticals
- Cell and Gene Therapies
- Veterinary Pharmaceuticals
- Other Pharmaceutical Products
- Small-Molecule Pharmaceuticals
- By Shipment Flow
- Domestic Shipments
- International Shipments
- By Region
- Northeast
- Southeast
- Midwest
- Southwest
- West
List of Companies Covered in this Report:
- United Parcel Service, Inc. (UPS Healthcare, including Marken)
- FedEx Corporation
- DHL Group
- Kuehne+Nagel International AG
- DSV A/S
- CEVA Logistics (CMA CGM Group)
- GEODIS
- World Courier (Cencora, Inc.)
- Cryoport, Inc.
- AIT Worldwide Logistics, Inc.
- JAS Worldwide
- Biocair (Geopost)
- Nippon Express Holdings, Inc. (NX Group)
- Expeditors International of Washington, Inc.
- Hellmann Worldwide Logistics SE & Co. KG
- Yusen Logistics Co., Ltd
- Kintetsu World Express, Inc.
- A.P. Moller - Maersk A/S
- Crane Worldwide Logistics
- Rhenus Group
- DACHSER SE
- Scan Global Logistics A/S
- GXO Logistics, Inc.
- XPO, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview and Importance of Pharmaceutical Cold Chain Air Freight Logistics
- 4.2 Market Drivers
- 4.2.1 Biologics and Specialty-Pharmaceutical Shipment Growth
- 4.2.2 Cell and Gene Therapy Commercialization
- 4.2.3 Direct-to-Patient and Specialty-Pharmacy Fulfillment
- 4.2.4 Clinical-Trial Decentralization and Patient-Specific Shipments
- 4.2.5 Airport-Level Cold-Chain Resilience and Qualified Cross-Dock Expansion
- 4.2.6 Digital Chain-of-Custody and Predictive Exception Management
- 4.3 Market Restraints
- 4.3.1 High Validation, Packaging and Temperature-Control Costs
- 4.3.2 Temperature Excursion, Delay and Product-Disposal Risk
- 4.3.3 Dry-Ice and Cryogenic Supply Volatility at Air Hubs
- 4.3.4 Limited GxP-Trained Labor and Site-of-Care Cryogenic Readiness
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Major Pharmaceutical Air Cargo Gateways and Infrastructure
- 4.8 Pharmaceutical Import Export Flows and Major Trade Corridors
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Buyers and Consumers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of Substitute Services
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Temperature Range
- 5.1.1 Chilled (0-5 °C)
- 5.1.2 Frozen (-18-0 °C)
- 5.1.3 Ambient
- 5.1.4 Deep-Frozen / Ultra-Low (More than -20 °C)
- 5.2 By Pharmaceutical Product Type
- 5.2.1 Small-Molecule Pharmaceuticals
- 5.2.1.1 Branded Pharmaceuticals
- 5.2.1.2 Over-the-Counter (OTC) Pharmaceuticals
- 5.2.1.3 Generic Pharmaceuticals
- 5.2.2 Biological Pharmaceuticals (Biologics, Biosimilars, Vaccines, and Blood-Derived Medicinal Products)
- 5.2.3 Specialty Pharmaceuticals
- 5.2.4 Cell and Gene Therapies
- 5.2.5 Veterinary Pharmaceuticals
- 5.2.6 Other Pharmaceutical Products
- 5.2.1 Small-Molecule Pharmaceuticals
- 5.3 By Shipment Flow
- 5.3.1 Domestic Shipments
- 5.3.2 International Shipments
- 5.4 By Region
- 5.4.1 Northeast
- 5.4.2 Southeast
- 5.4.3 Midwest
- 5.4.4 Southwest
- 5.4.5 West
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 United Parcel Service, Inc. (UPS Healthcare, including Marken)
- 6.4.2 FedEx Corporation
- 6.4.3 DHL Group
- 6.4.4 Kuehne+Nagel International AG
- 6.4.5 DSV A/S
- 6.4.6 CEVA Logistics (CMA CGM Group)
- 6.4.7 GEODIS
- 6.4.8 World Courier (Cencora, Inc.)
- 6.4.9 Cryoport, Inc.
- 6.4.10 AIT Worldwide Logistics, Inc.
- 6.4.11 JAS Worldwide
- 6.4.12 Biocair (Geopost)
- 6.4.13 Nippon Express Holdings, Inc. (NX Group)
- 6.4.14 Expeditors International of Washington, Inc.
- 6.4.15 Hellmann Worldwide Logistics SE & Co. KG
- 6.4.16 Yusen Logistics Co., Ltd
- 6.4.17 Kintetsu World Express, Inc.
- 6.4.18 A.P. Moller - Maersk A/S
- 6.4.19 Crane Worldwide Logistics
- 6.4.20 Rhenus Group
- 6.4.21 DACHSER SE
- 6.4.22 Scan Global Logistics A/S
- 6.4.23 GXO Logistics, Inc.
- 6.4.24 XPO, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


