|
시장보고서
상품코드
2105651
이벤트 관리 소프트웨어 시장 예측(-2031년) : 소프트웨어(이벤트 기획 및 운영, 이벤트 마케팅, 가상 및 하이브리드 플랫폼, 분석, AI 및 이벤트 인텔리전스), 이벤트 유형별(제품 발표회, 기업 회의, 컨퍼런스)Event Management Software Market by Software (Event Planning & Operations, Event Marketing, Virtual & Hybrid Platform, and Analytics, AI & Event Intelligence), Event Type (Product Launches, Corporate Meetings, and Conferences) - Global Forecast to 2031 |
||||||

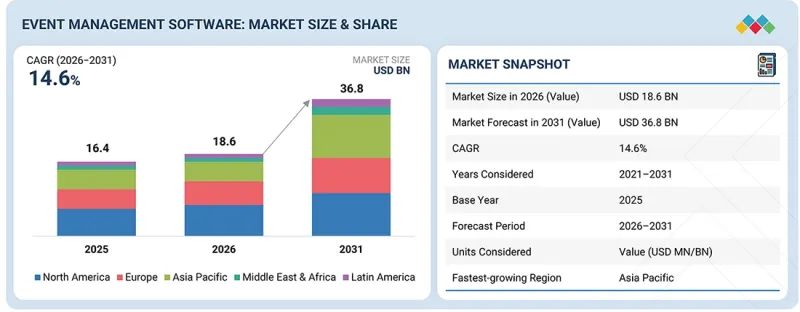
세계의 이벤트 관리 소프트웨어 시장은 급속히 확대하고 있으며, 시장 규모는 2026년 약 186억 달러에서 2031년에는 368억 달러로 확대하며, CAGR은 14.6%에 달할 것으로 예측됩니다.
시장 성장 요인은 기업이 브랜드 충성도 및 사내 문화 강화를 위해 체험형 참여를 중시함에 따라 고객 및 직원을 대상으로 한 이벤트에 대한 투자가 증가하고 있다는 점에 있습니다. AI를 활용한 기획 및 참가자 참여 유도 툴의 활용 확대에 따라 등록 절차 자동화, 컨텐츠 개인화, 참가자와의 실시간 교류가 가능해지면서 도입이 가속화되고 있습니다. 또한 컨퍼런스, 제품 발표회, 박람회 등 비즈니스 이벤트의 개최 빈도와 복잡성이 증가함에 따라 기업은 더욱 정교한 조정 툴의 도입을 요구받고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러) |
| 부문 | 제공, 소프트웨어, 이벤트 유형, 기술, 조직 규모, 최종사용자 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카 |
또한 분산된 툴에서 통합형 이벤트 플랫폼으로의 전환을 통해 기업은 등록, 마케팅, 분석 기능을 단일 시스템으로 통합하도록 유도받고 있으며, 이로 인해 효율성과 데이터 가시성이 향상되고 있습니다. 한편, 시장에는 특히 이벤트 플랫폼을 기존 CRM, 마케팅 자동화, 기업 시스템과 연동할 때 발생하는 도입 및 통합의 복잡성과 같은 제약이 존재하며, 이는 도입 지연이나 비용 증가로 이어질 수 있습니다. 소규모 이벤트 주최자의 예산 제약도 도입을 더욱 가로막고 있습니다. 많은 독립 기획자나 중소기업은 자사의 이벤트 건수나 규모를 고려할 때, 포괄적인 EMS 플랫폼의 비용이 지나치게 부담스럽다고 느끼기 때문입니다.
"기술별로는 AI 지원 이벤트 관리 소프트웨어가 가장 큰 시장 점유율을 차지할 전망입니다."
AI 기반 이벤트 관리 소프트웨어는 기계학습, 자연 언어 처리, 예측 분석을 기획, 마케팅, 참여 유도 워크플로우에 직접 통합하여, 주요 플랫폼의 차별화 요소로 점점 더 중요해지고 있는 인텔리전스 계층을 형성하고 있습니다. 이러한 기능을 통해 주최자는 등록자 수 예측을 자동화하고, 참가자와의 커뮤니케이션을 개인화하며, 수동 데이터 분석 없이도 실시간 참여도에 대한 인사이트를 도출할 수 있습니다. AI를 이벤트 워크플로우에 직접 통합함으로써 참가 등록 예측 모델링, 컨텐츠 자동 생성, 실시간 참여도 평가가 가능해지며, 주최자는 수작업에 따른 기획 부담을 줄이면서 측정 가능한 마케팅 성과를 향상시킬 수 있습니다.
2025년 6월, Cvent는 Cvent CONNECT에서 독자적인 인사이트, 분석 기능, 지능형 인프라를 아우르는 AI 레이어 ‘CventIQ’를 발표하고, 세션 실시간 텍스트 변환, 제안서 자동 작성, 몰입형 3D 행사장 시각화 등의 기능을 도입했습니다. 마찬가지로 2025년 9월, Zoom은 Zoomtopia에서 ‘AI Companion 3.0’을 발표했습니다. 이는 Zoom의 독자적인 모델과 타사 모델을 결합한 연합형 AI 아키텍처로, 이벤트나 회의에 대해 맥락을 더욱 깊이 고려한 인사이트를 제공하는 것입니다. 이러한 움직임은 이벤트 플랫폼의 차별화 측면에서 내장형 AI에 대한 의존도가 높아지고 있음을 보여줍니다. 신규 벤더나 솔루션 제공업체에게는 모듈형 AI 애드온이나 업계 특화형 AI 코파일럿 개발에 사업 기회가 있습니다. 데이터 개인정보 보호, 모델 정확도, 통합의 복잡성 등의 과제를 해결함으로써 진화하는 AI 지원 EMS 시장에서 가치를 창출할 수 있습니다.
"제공 유형별로는 소프트웨어 부문이 가장 큰 시장 점유율을 차지할 전망"
소프트웨어는 이벤트 관리 소프트웨어 시장의 기반을 형성하며, 거의 모든 이벤트 프로그램이 의존하는 등록, 기획, 마케팅, 분석과 같은 핵심 기능을 제공합니다. 이 부문에 진출하는 벤더는 AI를 활용한 컨텐츠 제작, 확정적인 등록 워크플로우, CRM, 마케팅 자동화, 결제 시스템 간의 원활한 상호 운용성을 제공함으로써 차별화를 꾀할 수 있습니다. 고객은 이벤트 소프트웨어가 단순한 기록 시스템으로서뿐만 아니라, 관련 참가자 및 참여도에 대한 인사이트를 자동으로 추출하는 지능형 계층으로 기능하기를 점점 더 기대하고 있습니다.
Cvent가 2026년 4월, 클라우드 네이티브 웨비나 및 디지털 참여 플랫폼인 ON24의 인수를 완료한 것은 소프트웨어 벤더들이 이벤트 운영에서 상시 운영형 디지털 참여로 사업 범위를 확대하고 있음을 보여줍니다. 2025년 12월, Eventbrite가 Bending Spoons에 의한 인수에 대한 최종 합의에 도달했는데, 이는 각 플랫폼 기업이 더 광범위한 기능과 규모를 추구하는 가운데 소프트웨어 분야의 통합이 지속되고 있음을 반영합니다. 신규 벤더에게 주어진 기회는 CRM과의 강력한 상호 운용성과 AI 기반 분석 기능을 갖춘 경량형 모듈식 소프트웨어 구성 요소를 구축하는 동시에, 레거시 시스템이나 스프레드시트 기반 툴로부터의 원활한 전환을 돕는 데 있습니다. 공급업체는 복잡하고 정기적인 이벤트 일정을 가진 업종을 타겟으로 삼아, 등록 및 계획의 핵심 기반이 마련된 단계에서 인접한 소프트웨어 모듈로 사업을 확장함으로써 확고한 입지를 다질 수 있습니다.
"북미는 기업내 디지털 기술의 적극적인 도입, AI 기반 이벤트 플랫폼의 광범위한 활용, 그리고 기술, 금융 서비스, 전문 서비스 분야에서의 클라우드 기반 툴 높은 보급률 덕분에 이벤트 관리 소프트웨어 시장을 선도하고 있습니다. 한편, 아시아태평양은 기업 이벤트 활동의 활성화, 디지털 인프라 구축, 클라우드 네이티브형 이벤트 플랫폼의 보급 확대에 힘입어 가장 빠르게 성장하는 지역입니다."
북미는 이벤트 개최 건수가 많은 부문에서의 AI 지원 이벤트 플랫폼 도입 확대, 클라우드 기반 도입 모델, 고도화된 참여도 분석 기능의 보급에 힘입어 이벤트 관리 소프트웨어 시장을 독점할 것으로 예상됩니다. 벤더와 솔루션 제공업체에게 이는 기술, 금융 서비스, 전문 서비스 등의 업계에서 참가자의 참여도를 높이고 측정 가능한 마케팅 성과를 가져다주는 확장 가능한 플랫폼을 제공할 수 있는 큰 기회가 될 것입니다. 이 지역의 성숙한 기업 소프트웨어 도입 현황과 AI 및 마케팅 자동화 통합의 가속화로 인해 조직들은 수작업이나 스프레드시트에 의존하던 이벤트 조정 방식에서 통합된 데이터베이스 이벤트 플랫폼으로 전환하고 있습니다. EMS 제공업체, CRM 벤더, 클라우드 하이퍼스케일러 간의 전략적 제휴는 생태계를 더욱 강화하고, 분산된 이벤트 포트폴리오 전반에 걸쳐 원활한 데이터 통합과 의사결정 향상을 보장합니다. 이벤트 기획에 따르는 부담 경감, 마케팅 전략의 기여도 측정 극대화, 참가자 데이터의 개인정보 보호 확보와 같은 기업의 주요 요구 사항을 충족함으로써, 벤더는 급속한 기술 도입과 지속적인 플랫폼 통합이 진행되는 이 시장에서 큰 가치를 창출할 가능성이 있습니다.
이 보고서에서는 전 세계 이벤트 관리 소프트웨어 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 각종 요인 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 정리하여 전해드립니다.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 고객 상황과 구매 행동
제7장 규제 상황
제8장 기술, 특허, 디지털 기술, AI의 도입에 의한 전략적 디스럽션
제9장 이벤트 관리 소프트웨어 시장 : 제공 서비스별
제10장 이벤트 관리 소프트웨어 시장 : 소프트웨어 유형별
제11장 이벤트 관리 소프트웨어 시장 : 이벤트 유형별
제12장 이벤트 관리 소프트웨어 시장 : 도입 형태별
제13장 이벤트 관리 소프트웨어 시장 : 기술 유형별
제14장 이벤트 관리 소프트웨어 시장 : 조직 규모별
제15장 이벤트 관리 소프트웨어 시장 : 최종사용자별
제16장 이벤트 관리 소프트웨어 시장 : 지역별
제17장 경쟁 구도
제18장 기업 개요
제19장 조사 방법
제20장 부록
KSA 26.08.19The global event management software market is expanding rapidly, with a projected market size anticipated to rise from about USD 18.6 billion in 2026 to USD 36.8 billion by 2031, featuring a CAGR of 14.6%. The event management software market drivers are centered on increasing enterprise investment in customer and employee events, as organizations prioritize experiential engagement to strengthen brand loyalty and workforce culture. The increasing use of AI-driven planning and attendee engagement tools accelerates adoption by automating registration, content personalization, and real-time audience interaction. The increasing frequency and complexity of business events, spanning conferences, product launches, and trade shows, push organizations toward more sophisticated coordination tools.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) |
| Segments | Offering, Software, Event Type, Technology, Organization Size, and End User |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
Additionally, the shift from fragmented tools to unified event platforms pushes enterprises to consolidate registration, marketing, and analytics functions into a single system, improving efficiency and data visibility. On the other hand, the market faces restraints such as high implementation and integration complexity, particularly when connecting event platforms with existing CRM, marketing automation, and enterprise systems, which can delay deployments and increase costs. Budget constraints among small event organizers further hinder adoption, as many independent planners and small businesses find comprehensive EMS platforms cost-prohibitive given their event volume and scale.
By technology, AI-enabled event management software to hold the largest market share"
AI-enabled event management software integrates machine learning, natural language processing, and predictive analytics directly into planning, marketing, and engagement workflows, forming the intelligence layer that increasingly differentiates leading platforms. These capabilities allow organizers to automate registration forecasting, personalize attendee communications, and surface real-time engagement insights without manual data analysis. Integrating AI directly into event workflows enables predictive registration modeling, automated content generation, and real-time engagement scoring, helping organizers reduce manual planning effort while improving measurable marketing outcomes. In June 2025, Cvent launched CventIQ at Cvent CONNECT, its AI layer spanning proprietary insights, analytics, and intelligent infrastructure, introducing live session transcription, automated proposal creation, and immersive 3D venue visualization. Similarly, in September 2025, Zoom introduced AI Companion 3.0 at Zoomtopia, a federated AI architecture combining Zoom's own models with third-party models to deliver deeper, context-aware event and meeting insights. These developments underscore the growing reliance on embedded AI to differentiate event platforms. For new vendors and solution providers, opportunities lie in building modular AI add-ons and vertical-specific AI copilots, addressing challenges such as data privacy, model accuracy, and integration complexity to capture value in the evolving AI-enabled EMS landscape.
"By offering, the software segment to hold the largest market share"
Software forms the foundational layer of the event management software market, providing the core registration, planning, marketing, and analytics functionality that nearly every event program depends on. Vendors entering this segment can differentiate by delivering AI-assisted content creation, deterministic registration workflows, and seamless interoperability across CRM, marketing automation, and payment systems. Customers increasingly expect event software to serve not only as a system of record but as an intelligent layer that surfaces relevant attendee and engagement insights automatically. Cvent's April 2026 completed acquisition of ON24, a cloud-native webinar and digital engagement platform, demonstrates how software vendors are extending their reach from event execution into always-on digital engagement. In December 2025, Eventbrite entered a definitive agreement to be acquired by Bending Spoons, reflecting continued consolidation within the software segment as platforms seek broader capability and scale. For new vendors, opportunities lie in building lightweight, modular software components with strong CRM interoperability and AI-assisted analytics, while offering low-friction migration paths from legacy and spreadsheet-based tools. Providers can establish strong footholds by targeting industries with complex, recurring event calendars and expanding into adjacent software modules once the core registration and planning backbone is in place.
"North America leads the event management software market with strong enterprise digital adoption, widespread use of AI-driven event platforms, and high adoption of cloud-based tools across technology, financial services, and professional services, while Asia Pacific is the fastest-growing region driven by rising corporate event activity, growing digital infrastructure, and expanding adoption of cloud-native event platforms."
North America is expected to dominate the event management software market, driven by the rising adoption of AI-powered event platforms, cloud-based deployment models, and advanced engagement analytics capabilities across high-event-volume sectors. For vendors and solution providers, this presents significant opportunities to deliver scalable platforms that improve attendee engagement and measurable marketing return across industries such as technology, financial services, and professional services. The region's mature enterprise software adoption and accelerated integration of AI and marketing automation push organizations away from manual, spreadsheet-based event coordination toward unified, data-driven event platforms. Strategic collaborations between EMS providers, CRM vendors, and cloud hyperscalers further strengthen the ecosystem, ensuring seamless data integration and improving decision-making across distributed event portfolios. By addressing key enterprise requirements such as reducing planning overhead, maximizing marketing attribution, and ensuring attendee data privacy, vendors can capture substantial value in a market defined by rapid technological adoption and continued platform consolidation.
Breakdown of Primaries
In-depth interviews were conducted with Chief Executive Officers (CEOs), innovation and technology directors, system integrators, and executives from various key organizations operating in the event management software market.
- By Company: Tier I - 34%, Tier II - 43%, and Tier III - 23%
- By Designation: C-Level Executives - 50%, Directors -30%, and others - 20%
- By Region: North America - 25%, Europe - 30%, Asia Pacific - 30%, Middle East & Africa - 5%, and Latin America - 5%
The report includes a study of key players offering event management software products. It profiles major vendors in the event management software market. The major market players include Cvent (US), Eventbrite (US), Zoom (US), Stova (US), RingCentral (US), Momentus Technologies (US), Bizzabo (US), Whova (US), EventMobi (Canada), Certain (US), Aventri (US), Hubilo (US), 6Connex (US), and vFairs (US).
Research Coverage
This research report categorizes the event management software market, which has been segmented based on offering, software, event type, technology, organization size, end user, and region. The offering segment comprises software and services, with services further split into professional services (consulting, deployment & integration, support & maintenance) and managed services (platform administration, technical support, managed event operations). The software segment comprises event planning & operations software, registration & ticketing software, event marketing software, attendee engagement & networking software, onsite event management software, analytics & event intelligence software, and other software. The event type segment covers association events, government events, entertainment & sports events, conferences, trade shows & exhibitions, corporate meetings, product launches, and other event types. The technology segment comprises AI-enabled event management software and conventional event management software. The organization size segment is bifurcated into large enterprises and small & medium-sized enterprises. The end user segment covers event management companies (event management agencies, professional conference organizers, exhibition & trade show organizers), corporate enterprises (BFSI, IT & telecom, manufacturing, retail & e-commerce, media & entertainment, hospitality, and others), education institutions, cultural & sports organizations, and others, and region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America). The report's scope covers detailed information regarding the major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the event management software market. A thorough analysis of the key industry players was done to provide insights into their business overview, solutions, and services; key strategies; contracts, partnerships, agreements, new product & service launches, and mergers and acquisitions; and recent developments associated with the event management software market. This report also covers the competitive analysis of upcoming startups in the event management software market ecosystem.
Reason to buy this Report
The report would provide market leaders and new entrants with information on the closest approximations of the revenue numbers for the overall event management software market and its subsegments. It would help stakeholders understand the competitive landscape and gain more insights to better position their businesses and plan suitable go-to-market strategies. It also helps stakeholders understand the market's pulse and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of key drivers (Increasing enterprise investment in customer and employee events, Increasing use of AI-driven planning and attendee engagement, Increasing frequency and complexity of business events, Shift from fragmented tools to unified event platforms), restraints (High implementation and integration complexity, Budget constraints among small event organizers), opportunities (AI-powered event orchestration and predictive intelligence, Integration with CRM and marketing automation ecosystems, Growth of on-site automation and smart badging solutions), and challenges (Supporting large-scale events without performance disruption, Maintaining interoperability across multiple event technologies).
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the event management software market.
- Market Development: Comprehensive information about lucrative markets - the report analyzes the event management software market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the event management software market.
Competitive Assessment: In-depth assessment of market shares, growth strategies and service offerings of leading players such as Cvent (US), Eventbrite (US), Zoom (US), Stova (US), RingCentral (US), Momentus Technologies (US), Bizzabo (US), Whova (US), EventMobi (Canada), EventX (US), Aventri (US), Hubilo (US), Zoho (US), and Cisco (US). The report also helps stakeholders understand the event management software market's pulse and provides information on key market drivers, restraints, challenges, and opportunities.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN EVENT MANAGEMENT SOFTWARE MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN EVENT MANAGEMENT SOFTWARE MARKET
- 3.2 EVENT MANAGEMENT SOFTWARE MARKET, BY OFFERING
- 3.3 EVENT MANAGEMENT SOFTWARE MARKET, BY END USER
- 3.4 EVENT MANAGEMENT SOFTWARE MARKET, BY SOFTWARE TYPE
- 3.5 EVENT MANAGEMENT SOFTWARE MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising enterprise investment in customer and employee events
- 4.2.1.2 Increasing usage of AI-driven planning and attendee engagement
- 4.2.2 RESTRAINTS
- 4.2.2.1 High implementation and integration complexity
- 4.2.2.2 Budget constraints among small event organizers
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 AI-powered event orchestration and predictive intelligence
- 4.2.3.2 Growth of on-site automation and smart badging solutions
- 4.2.3.3 Integration with CRM and marketing automation ecosystems
- 4.2.4 CHALLENGES
- 4.2.4.1 Maintaining interoperability across multiple event technologies
- 4.2.4.2 Balancing product innovation with platform reliability
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN EVENT MANAGEMENT SOFTWARE MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.1.1 Event Management Software Business Models
- 4.5.2 ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.6 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS & FORECASTS
- 5.2.3 TRENDS IN GLOBAL CLOUD SYSTEM MANAGEMENT MARKET
- 5.2.4 TRENDS IN GLOBAL DIGITAL MARKETING SOFTWARE MARKET
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TRENDS OF VENDORS, BY REGION,2025
- 5.5.1.1 North America
- 5.5.1.2 Europe
- 5.5.1.3 Asia Pacific
- 5.5.1.4 Middle East & Africa
- 5.5.1.5 Latin America
- 5.5.2 PRICING LANDSCAPE FOR EVENT MANAGEMENT SOFTWARE MARKET, 2025
- 5.5.3 INDICATIVE PRICING TREND, BY KEY VENDOR,2025
- 5.5.1 AVERAGE SELLING PRICE TRENDS OF VENDORS, BY REGION,2025
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.10 IMPACT OF 2025 US TARIFF - EVENT MANAGEMENT SOFTWARE MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRY/REGION
- 5.10.4.1 North America
- 5.10.4.2 Europe
- 5.10.4.3 Asia Pacific
- 5.10.5 IMPACT ON END USERS
- 5.10.5.1 Event management companies
- 5.10.5.2 Corporate enterprises
- 5.10.5.3 Educational institutions
6 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 6.1 DECISION-MAKING PROCESS
- 6.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 6.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 6.2.2 BUYING CRITERIA
- 6.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 6.4 UNMET NEEDS OF VARIOUS END USERS
- 6.5 MARKET PROFITABILITY
- 6.5.1 REVENUE POTENTIAL
- 6.5.2 COST DYNAMICS
- 6.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
7 REGULATORY LANDSCAPE
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATIONS, BY REGION
- 7.1.1.1 North America
- 7.1.1.2 Europe
- 7.1.1.3 Asia Pacific
- 7.1.1.4 Middle East & South Africa
- 7.1.1.5 Latin America
- 7.1.2 INDUSTRY STANDARDS, BY REGION
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Rest of the world
- 7.1.1 REGULATIONS, BY REGION
8 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
- 8.1 TECHNOLOGY ANALYSIS
- 8.1.1 KEY EMERGING TECHNOLOGIES
- 8.1.1.1 Digital thread & model-based systems engineering (MBSE)
- 8.1.1.2 Virtual collaboration technologies
- 8.1.1.3 Event data analytics and predictive intelligence
- 8.1.2 COMPLEMENTARY TECHNOLOGIES
- 8.1.2.1 CRM & marketing automation platforms
- 8.1.2.2 Contactless check-in and smart badging technologies
- 8.1.2.3 Mobile event application & audience engagement technologies
- 8.1.3 ADJACENT TECHNOLOGIES
- 8.1.3.1 Customer experience management technologies
- 8.1.3.2 Sales enablement & lead intelligence technologies
- 8.1.3.3 Workforce engagement & learning management technologies
- 8.1.1 KEY EMERGING TECHNOLOGIES
- 8.2 TECHNOLOGY/PRODUCT ROADMAP
- 8.2.1 SHORT-TERM (2026-2028) | AI-ASSISTED EVENT AUTOMATION & EXPERIENCE DIGITIZATION
- 8.2.1.1 Focus Areas
- 8.2.1.1.1 Technology Development
- 8.2.1.1.2 Product Innovations
- 8.2.1.1.3 Market Adoption
- 8.2.1.1 Focus Areas
- 8.2.2 MID-TERM (2028-2031) | PREDICTIVE EVENT INTELLIGENCE & CONNECTED EVENT-TO-REVENUE WORKFLOWS
- 8.2.2.1 Focus Areas
- 8.2.2.1.1 Technology Development
- 8.2.2.1.2 Product Innovations
- 8.2.2.1.3 Market Adoption
- 8.2.2.1 Focus Areas
- 8.2.3 LONG-TERM (2031-2035+) | AUTONOMOUS EVENT ORCHESTRATION & IMMERSIVE EVENT ECOSYSTEMS
- 8.2.3.1 Focus Areas
- 8.2.3.1.1 Technology Development
- 8.2.3.1.2 Product Innovations
- 8.2.3.1.3 Market Adoption
- 8.2.3.1 Focus Areas
- 8.2.1 SHORT-TERM (2026-2028) | AI-ASSISTED EVENT AUTOMATION & EXPERIENCE DIGITIZATION
- 8.3 PATENT ANALYSIS
- 8.4 IMPACT OF AI/GENERATIVE AI ON THE EVENT MANAGEMENT SOFTWARE MARKET
- 8.4.1 TOP USE CASES AND MARKET POTENTIAL
- 8.4.2 BEST PRACTICES IN EVENT MANAGEMENT SOFTWARE MARKET
- 8.4.3 CASE STUDY OF AI IMPLEMENTATION IN EVENT MANAGEMENT SOFTWARE MARKET
- 8.4.4 INTERCONNECTED ADJACENCY ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 8.4.5 CLIENT READINESS TO ADOPT GENERATIVE AI IN THE EVENT MANAGEMENT SOFTWARE MARKET
9 EVENT MANAGEMENT SOFTWARE MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 OFFERING: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 9.2 SOFTWARE
- 9.2.1 INCREASING SHIFT TOWARD UNIFIED, AI-ENABLED PLATFORMS DRIVES DOMINANCE
- 9.3 SERVICES
- 9.3.1 RISING PLATFORM INTEGRATION COMPLEXITY DRIVES DEMAND
- 9.3.2 PROFESSIONAL SERVICES
- 9.3.2.1 Consulting
- 9.3.2.2 Deployment & Integration
- 9.3.2.3 Support & Maintenance
- 9.3.3 MANAGED SERVICE
- 9.3.3.1 Platform Administration
- 9.3.3.2 Technical Support
- 9.3.3.3 Managed Event Operations
10 EVENT MANAGEMENT SOFTWARE MARKET, BY SOFTWARE TYPE
- 10.1 INTRODUCTION
- 10.1.1 SOFTWARE TYPE: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 10.2 EVENT PLANNING & OPERATIONS SOFTWARE
- 10.2.1 INCREASING NEED FOR CENTRALIZED PLANNING WORKFLOWS BOOSTS GROWTH
- 10.2.2 EVENT PLANNING
- 10.2.3 VENUE & RESOURCE MANAGEMENT
- 10.2.4 TEAM COLLABORATION
- 10.2.5 BUDGET MANAGEMENT
- 10.2.6 OTHERS
- 10.3 REGISTRATION & TICKETING SOFTWARE
- 10.3.1 RISING DEMAND FOR FRICTIONLESS ATTENDEE SIGN-UP DRIVES ADOPTION
- 10.3.2 REGISTRATION MANAGEMENT
- 10.3.3 PAYMENT PROCESSING
- 10.3.4 QR CODE REGISTRATION
- 10.3.5 OTHERS
- 10.4 EVENT MARKETING SOFTWARE
- 10.4.1 GROWING FOCUS ON MEASURABLE REGISTRATION PIPELINES ENHANCES DEMAND
- 10.4.2 EVENT WEBSITES
- 10.4.3 EMAIL CAMPAIGNS
- 10.4.4 SOCIAL MEDIA PROMOTIONS
- 10.4.5 OTHERS
- 10.5 ATTENDEE ENGAGEMENT & NETWORKING SOFTWARE
- 10.5.1 RISING ATTENDEE EXPECTATIONS FOR INTERACTIVE EXPERIENCES DRIVES ADOPTION
- 10.5.2 NETWORKING
- 10.5.3 MOBILE EVENT APPS
- 10.5.4 LIVE POLLS
- 10.5.5 GAMIFICATION
- 10.5.6 OTHERS
- 10.6 VIRTUAL & HYBRID EVENT PLATFORM
- 10.6.1 CONTINUED NORMALIZATION OF HYBRID FORMATS SUSTAINS DEMAND
- 10.6.2 LIVE STREAMING
- 10.6.3 VIRTUAL NETWORKING
- 10.6.4 WEBINAR PLATFORM
- 10.6.5 BREAKOUT SESSIONS
- 10.6.6 OTHERS
- 10.7 ONSITE EVENT MANAGEMENT SOFTWARE
- 10.7.1 GROWING EVENT SCALE AND ATTENDEE VOLUMES DRIVE SEGMENT
- 10.7.2 CHECK-IN
- 10.7.3 BADGE PRINTING
- 10.7.4 SESSION SCANNING
- 10.7.5 SELF-SERVICE KIOSKS
- 10.7.6 OTHERS
- 10.8 ANALYTICS, AI, AND EVENT INTELLIGENCE
- 10.8.1 INTEGRATION OF AI INTO EVENT WORKFLOWS ACCELERATES ADOPTION
- 10.8.2 EVENT ANALYTICS
- 10.8.3 PREDICTIVE ANALYTICS
- 10.8.4 AI INSIGHTS
- 10.8.5 OTHERS
- 10.9 OTHER SOFTWARE
- 10.9.1 INCREASING COMPLEXITY OF SPONSOR AND EXHIBITOR RELATIONSHIPS DRIVES DEMAND
11 EVENT MANAGEMENT SOFTWARE MARKET, BY EVENT TYPE
- 11.1 INTRODUCTION
- 11.1.1 EVENT TYPE: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 11.2 ENTERTAINMENT & SPORTS EVENTS
- 11.2.1 RISING FREQUENCY OF LARGE-SCALE ENTERTAINMENT AND SPORTING EVENTS TO BOOST SEGMENT
- 11.3 CONFERENCES
- 11.3.1 RISING ENTERPRISE INVESTMENT IN RECURRING CONFERENCES DRIVES DEMAND
- 11.4 TRADE SHOWS & EXHIBITIONS
- 11.4.1 CONTINUED IMPORTANCE OF TRADE SHOWS IN B2B MARKETING TO BOOST MARKET
- 11.5 CORPORATE MEETINGS
- 11.5.1 INCREASING FREQUENCY OF INTERNAL CORPORATE EVENTS PROPELS MARKET
- 11.6 PRODUCT LAUNCHES
- 11.6.1 GROWING PACE OF PRODUCT LAUNCHES DRIVES DEMAND FOR RAPID-DEPLOYMENT EVENT SOFTWARE
- 11.7 GOVERNMENT EVENTS
- 11.7.1 EXPANDING USE OF PUBLIC CONSULTATIONS AND CIVIC EVENTS DRIVES ADOPTION OF COMPLIANT EVENT SOFTWARE
- 11.8 OTHERS
- 11.8.1 RISING DIVERSITY OF NICHE AND COMMUNITY EVENTS ENHANCES DEMAND FOR FLEXIBLE EVENT SOFTWARE
12 EVENT MANAGEMENT SOFTWARE MARKET, BY DEPLOYMENT TYPE
- 12.1 INTRODUCTION
- 12.1.1 DEPLOYMENT TYPE: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 12.2 CLOUD
- 12.2.1 GROWING PREFERENCE FOR SCALABLE, SUBSCRIPTION-BASED ACCESS ACCELERATES SEGMENT GROWTH
- 12.3 ON-PREMISES
- 12.3.1 STRINGENT DATA RESIDENCY REQUIREMENTS SUSTAIN DEMAND
13 EVENT MANAGEMENT SOFTWARE MARKET, BY TECHNOLOGY TYPE
- 13.1 INTRODUCTION
- 13.1.1 TECHNOLOGY TYPE: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 13.2 CONVENTIONAL EVENT MANAGEMENT SOFTWARE
- 13.2.1 ESTABLISHED EVENT WORKFLOWS AND BROAD FUNCTIONAL COVERAGE SUPPORT ADOPTION
- 13.3 AI-ENABLED EVENT MANAGEMENT SOFTWARE
- 13.3.1 DEMAND FOR AUTOMATION, PERSONALIZATION, AND REAL-TIME EVENT INTELLIGENCE ACCELERATES ADOPTION
14 EVENT MANAGEMENT SOFTWARE MARKET, BY ORGANIZATION SIZE
- 14.1 INTRODUCTION
- 14.1.1 ORGANIZATION SIZE: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 14.2 LARGE ENTERPRISES
- 14.2.1 ENTERPRISE-WIDE PLATFORM CONSOLIDATION DRIVES SEGMENT
- 14.3 SMALL & MEDIUM-SIZED ENTERPRISES
- 14.3.1 ACCESSIBLE, CLOUD-BASED PRICING MODELS DRIVE ADOPTION AMONG SMES
15 EVENT MANAGEMENT SOFTWARE MARKET, BY END USER
- 15.1 INTRODUCTION
- 15.1.1 END USER: EVENT MANAGEMENT SOFTWARE MARKET DRIVERS
- 15.2 EVENT MANAGEMENT COMPANIES
- 15.2.1 GROWING OUTSOURCING OF EVENT PLANNING DRIVES SOFTWARE ADOPTION
- 15.2.2 EVENT MANAGEMENT AGENCIES
- 15.2.3 PROFESSIONAL CONFERENCE ORGANIZERS
- 15.2.4 EXHIBITION & TRADE SHOW ORGANIZERS
- 15.3 CORPORATE ENTERPRISES
- 15.3.1 INCREASING ENTERPRISE INVESTMENT IN CUSTOMER AND EMPLOYEE EVENTS DRIVES SEGMENT
- 15.3.2 BFSI
- 15.3.3 IT & TELECOM
- 15.3.4 MANUFACTURING
- 15.3.5 RETAIL & E-COMMERCE
- 15.3.6 MEDIA & ENTERTAINMENT
- 15.3.7 HOSPITALITY
- 15.3.8 OTHERS
- 15.4 EDUCATION INSTITUTIONS
- 15.4.1 RISING USE OF VIRTUAL AND HYBRID FORMATS DRIVES EVENT SOFTWARE ADOPTION
- 15.5 SPORTS & CULTURAL ORGANIZATIONS
- 15.5.1 GROWING FAN ENGAGEMENT REQUIREMENTS DRIVE EVENT SOFTWARE ADOPTION
- 15.6 OTHERS
- 15.6.1 GROWING RELIANCE ON VIRTUAL FUNDRAISING AND PUBLIC CONSULTATIONS DRIVES ADOPTION
16 EVENT MANAGEMENT SOFTWARE MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 Enterprise marketing budgets and AI-driven planning adoption accelerate market growth
- 16.2.2 CANADA
- 16.2.2.1 Increase in association events and bilingual compliance requirements to drive market
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 UK
- 16.3.1.1 High financial service conference density and data protection requirements accelerate adoption
- 16.3.2 GERMANY
- 16.3.2.1 Trade fair leadership and industrial conference density drive market growth
- 16.3.3 FRANCE
- 16.3.3.1 Luxury and aerospace conference growth and digital sovereignty priorities - key drivers
- 16.3.4 ITALY
- 16.3.4.1 SME exhibitor participation and fashion & design trade show growth drive market
- 16.3.5 REST OF EUROPE
- 16.3.1 UK
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Technology conference expansion and domestic platform localization boost market growth
- 16.4.2 INDIA
- 16.4.2.1 IT sector conference growth and convention infrastructure expansion - key drivers
- 16.4.3 JAPAN
- 16.4.3.1 Precision manufacturing trade show density and enterprise digitalization drive adoption
- 16.4.4 AUSTRALIA & NEW ZEALAND
- 16.4.4.1 Business events infrastructure investment and association conference growth support market expansion
- 16.4.5 SOUTH KOREA
- 16.4.5.1 Technology launch density and smart convention center investment propel market growth
- 16.4.6 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 MIDDLE EAST & AFRICA
- 16.5.1 GCC COUNTRIES
- 16.5.1.1 Saudi Arabia
- 16.5.1.1.1 Vision 2030 business events investment accelerates market growth
- 16.5.1.2 UAE
- 16.5.1.2.1 Global business events hub status positions UAE as key market
- 16.5.1.3 Other GCC countries
- 16.5.1.1 Saudi Arabia
- 16.5.2 SOUTH AFRICA
- 16.5.2.1 Financial services conference growth and regional business hub status drive market
- 16.5.3 REST OF MIDDLE EAST & AFRICA
- 16.5.1 GCC COUNTRIES
- 16.6 LATIN AMERICA
- 16.6.1 BRAZIL
- 16.6.1.1 Financial services conference density and trade show digitalization to drive market
- 16.6.2 MEXICO
- 16.6.2.1 Nearshoring-led corporate expansion to boost market
- 16.6.3 REST OF LATIN AMERICA
- 16.6.1 BRAZIL
17 COMPETITIVE LANDSCAPE
- 17.1 INTRODUCTION
- 17.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 17.3 REVENUE ANALYSIS, 2021-2025
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.4.1 CVENT
- 17.4.2 EVENTBRITE
- 17.4.3 ZOOM
- 17.4.4 ZOHO
- 17.4.5 RINGCENTRAL
- 17.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.5.1 STARS
- 17.5.2 EMERGING LEADERS
- 17.5.3 PERVASIVE PLAYERS
- 17.5.4 PARTICIPANTS
- 17.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.5.5.1 Company footprint
- 17.5.5.2 Region footprint
- 17.5.5.3 Software Type footprint
- 17.5.5.4 Deployment type footprint
- 17.5.5.5 End user footprint
- 17.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.6.1 PROGRESSIVE COMPANIES
- 17.6.2 RESPONSIVE COMPANIES
- 17.6.3 DYNAMIC COMPANIES
- 17.6.4 STARTING BLOCKS
- 17.6.5 COMPETITIVE BENCHMARKING: STARTUP/SMES, 2025
- 17.6.5.1 Detailed list of key startups/SMEs
- 17.6.5.2 Competitive benchmarking of key startups/SMEs
- 17.7 COMPANY VALUATION AND FINANCIAL METRICS
- 17.7.1 COMPANY VALUATION OF KEY VENDORS
- 17.7.2 FINANCIAL METRICS OF KEY VENDORS
- 17.8 COMPETITIVE SCENARIO
- 17.8.1 PRODUCT LAUNCHES/ENHANCEMENTS
- 17.8.2 DEALS
18 COMPANY PROFILES
- 18.1 INTRODUCTION
- 18.2 KEY PLAYERS
- 18.2.1 CVENT
- 18.2.1.1 Business overview
- 18.2.1.2 Products/Solutions/Services offered
- 18.2.1.3 Recent developments
- 18.2.1.3.1 Product/service launches and enhancements
- 18.2.1.3.2 Deals
- 18.2.1.4 MnM view
- 18.2.1.4.1 Right to win
- 18.2.1.4.2 Strategic choices
- 18.2.1.4.3 Weaknesses and competitive threats
- 18.2.2 EVENTBRITE
- 18.2.2.1 Business overview
- 18.2.2.2 Products/Solutions/Services offered
- 18.2.2.3 Recent developments
- 18.2.2.3.1 Product/service launches and enhancements
- 18.2.2.3.2 Deals
- 18.2.2.4 MnM view
- 18.2.2.4.1 Right to win
- 18.2.2.4.2 Strategic choices
- 18.2.2.4.3 Weaknesses and competitive threats
- 18.2.3 ZOOM
- 18.2.3.1 Business overview
- 18.2.3.2 Products/Solutions/Services offered
- 18.2.3.3 Recent developments
- 18.2.3.3.1 Product/Service launches and enhancements
- 18.2.3.3.2 Deals
- 18.2.3.4 MnM view
- 18.2.3.4.1 Right to win
- 18.2.3.4.2 Strategic choices
- 18.2.3.4.3 Weaknesses and competitive threats
- 18.2.4 ZOHO CORPORATION
- 18.2.4.1 Business overview
- 18.2.4.2 Products/Solutions/Services offered
- 18.2.4.3 Recent developments
- 18.2.4.3.1 Product/Service launches and enhancements
- 18.2.4.3.2 Deals
- 18.2.5 RINGCENTRAL
- 18.2.5.1 Business overview
- 18.2.5.2 Products/Solutions/Services offered
- 18.2.5.3 Recent developments
- 18.2.5.3.1 Product/Service launches and enhancements
- 18.2.5.4 MnM view
- 18.2.5.4.1 Right to win
- 18.2.5.4.2 Strategic choices
- 18.2.5.4.3 Weaknesses and competitive threats
- 18.2.6 ACTIVE NETWORK
- 18.2.6.1 Business overview
- 18.2.6.2 Products/Solutions/Services offered
- 18.2.6.3 Recent developments
- 18.2.6.3.1 Product/Service launches and enhancements
- 18.2.6.3.2 Deals
- 18.2.7 CISCO
- 18.2.7.1 Business overview
- 18.2.7.2 Products/Solutions/Services offered
- 18.2.7.3 Recent developments
- 18.2.7.3.1 Product launches and enhancements
- 18.2.7.3.2 Deals
- 18.2.8 MOMENTUS TECHNOLOGIES
- 18.2.8.1 Business overview
- 18.2.8.2 Products/Solutions/Services offered
- 18.2.8.3 Recent developments
- 18.2.8.3.1 Product/Service launches and enhancements
- 18.2.8.3.2 Deals
- 18.2.9 RAINFOCUS
- 18.2.9.1 Business overview
- 18.2.9.2 Products/Solutions/Services offered
- 18.2.9.3 Recent developments
- 18.2.9.3.1 Product/Service launches and enhancements
- 18.2.9.3.2 Deals
- 18.2.10 STOVA
- 18.2.10.1 Business overview
- 18.2.10.2 Products/Solutions/Services offered
- 18.2.10.3 Recent developments
- 18.2.10.3.1 Product/Service launches and enhancements
- 18.2.1 CVENT
- 18.3 OTHER PLAYERS
- 18.3.1 KALTURA
- 18.3.2 BIZZABO
- 18.3.3 AIRMEET
- 18.3.4 WHOVA
- 18.3.5 EVENTX
- 18.3.6 ZUDDL
- 18.3.7 EVENTMOBI
- 18.3.8 WEBMOBI
- 18.3.9 SPOTME
- 18.3.10 ARLO
- 18.3.11 PLANNING POD
- 18.3.12 IDLOOM
- 18.3.13 REGPACK
- 18.3.14 CIRCA (FORMERLY EVENTGEEK)
- 18.3.15 GRENADINE TECHNOLOGIES
- 18.3.16 SWOOGO
- 18.3.17 VFAIRS
- 18.3.18 ACCELEVENTS
- 18.3.19 EVENTLEAF
- 18.3.20 NUNIFY
- 18.3.21 INEVENT
- 18.3.22 EVENTDEX
- 18.3.23 EVENT ESPRESSO
- 18.3.24 EVENTBOOST
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH APPROACH
- 19.1.1 SECONDARY DATA
- 19.1.1.1 Key data from secondary sources
- 19.1.1.2 Breakup of primary profiles
- 19.1.1.3 Key industry insights
- 19.1.1 SECONDARY DATA
- 19.2 MARKET BREAKUP AND DATA TRIANGULATION
- 19.3 MARKET SIZE ESTIMATION
- 19.4 MARKET FORECAST
- 19.5 RESEARCH ASSUMPTIONS
- 19.6 RESEARCH LIMITATIONS
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS