

|
시장보고서
상품코드
2114281
단층막 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Single Ply Membrane - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
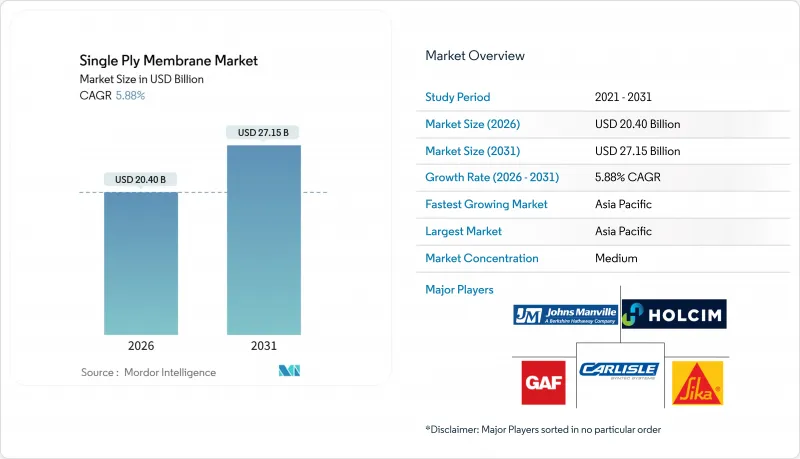
에 의하면, 단층막 시장 규모는 2026년에 204억 달러로 추정되고 예측 기간(2026-2031년) CAGR 5.88%로 확대되어 2031년에는 271억 5,000만 달러에 이를 전망입니다.
본 보고서에서는 업계를 ‘유형’(에틸렌·프로파일렌·디엔·모노머(EPDM), 열가소성 폴리올레핀(TPO), 폴리염화비닐(PVC), 개질 아스팔트, 기타),‘용도’(주거, 상업시설, 공공시설, 인프라), ‘건설 형태’(신축, 개보수), ‘지역’(아시아태평양, 기타)별로 분류하고 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 단층막 시장 동향 및 인사이트
에너지 절약형 및 쿨 루프 시스템에 대한 수요 증가
쿨루프용 막재는 쿨루프 평가 위원회(Cool Roof Rating Council)의 엄격한 경년 반사율 기준을 충족하면서, ENERGY STAR 인증 및 LEED v4 포인트 획득을 가능하게 합니다. 캘리포니아주의 ‘타이틀 24(Title 24)’ 건축 기준에 따라 현재 모든 저경사 상업용 건물에 쿨 루프 채택이 의무화되어 있으며, 2024년 하반기에는 흰색 TPO 및 PVC 시공업체의 납기 기간이 8주를 초과하는 상황이 발생했습니다. 미국 환경보호청(EPA)은 2026년에 ‘열섬 현상 저감 프로그램’을 15개 도시권으로 새롭게 확대할 예정이며, 이에 따라 정부 시설의 반사성 개보수 공사에 대해 지자체로부터 보조금이 지급될 것입니다. 대규모 태양광 발전 개발업체들은 태양광 모듈에 가해지는 열적 스트레스를 억제하는 밝은 색상의 필름 소재를 선호하고 있으며, 이러한 요건에는 높은 알베도와 유도 용접 이음매를 결합한 칼라일(Carlyle)의 ‘SeamShield’ 코팅이 부합합니다.
북미의 상업용 지붕 재시공 붐
2024년, 미국의 비주거용 지붕재 부문은 노후화된 저경사 지붕 재고를 배경으로 눈부신 성장을 이루었습니다. 시공업체들은 주로 단층막을 선호하며, 이것이 프로젝트 구성의 대부분을 차지하고 있습니다. 이 카테고리 내에서 TPO가 가장 큰 점유율을 차지하고 있으며, 그 뒤를 PVC, EPDM이 따르고 있습니다. 칼라일의 건축자재 부문 매출은 유통업체의 재고가 정상화되고, 시공업체의 미수주 물량이 견조했던 덕분에 높은 EBITDA 마진에 힘입어 증가했습니다. 2024년 3월에 발표되어 2025년 6월에 착공 예정인 캔자스주 뉴턴에 건설될 GAF의 새로운 지붕재 공장은 해당 기업이 지붕 교체 수요의 지속을 확신하고 있음을 뒷받침합니다. 그러나 자동화가 진행되고 있어, 직원 수 증가는 극히 일부 직종에 국한되어 있습니다.
폴리머 및 첨가제 가격 변동
2025년 6월, 미국의 PVC 수지 가격은 전년 동월 대비 하락했습니다. 반면, 유럽에서는 가격이 상승하여 전 세계 생산 업체들의 이익률이 압박을 받았습니다. TPO의 원료인 프로파일렌은 걸프 코스트 정유시설의 정기 정비 영향으로 2024년 내내 가격 변동이 나타났습니다. EPDM용 에틸렌 가격도 주로 크래커 가동 중단으로 인해 변동했습니다. 이산화티타늄 비용은 2023년에 정점을 찍은 후 2025년에는 안정화되었습니다. 그러나 공급이 전 세계 3개 업체에 집중되어 있어, 과점 구조에 따른 가격 결정력은 여전히 유지되고 있습니다. 주요 멤브레인 제조업체들은 전략적 조치로 다년 계약을 통해 수지 조달을 확보하고 있습니다. 이러한 계약에는 최저가·최고가 조항이 포함되어 있어 원료 가격 변동 위험의 상당 부분을 헤지할 수 있는 반면, 현물 가격이 하락할 경우의 잠재적 이익도 제한되게 됩니다.
부문별 분석
열가소성 폴리올레핀(TPO)은 인력 절감으로 이어지는 16피트 롤 소재와 더욱 엄격해진 쿨 루프 규제의 뒷받침을 받아, 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 7.01%를 나타낼 것으로 예측되며, 이는 재료 분류 중 가장 높은 성장률입니다. 폴리염화비닐(PVC)은 뛰어난 내화학성과 방화 성능에 힘입어 2025년 기준 단층 필름 시장에서 36.39%의 점유율을 유지했으나, 독일, 프랑스, 북유럽 국가들의 지자체에 의한 사용 금지 조치로 인해 유럽 내 점유율은 축소되는 추세입니다. 에틸렌·프로파일렌·디엔·모노머(EPDM)는 자본 비용이 반사율보다 우선시되는 창고 지붕에서 여전히 인기가 높지만, EPDM의 색상이 짙기 때문에 많은 전력 회사의 보조금 대상에서 제외되고 있습니다. 개질 아스팔트는 시공 업체들이 시공 기간을 단축할 수 있는 열풍 용접식 TPO 솔루션으로 전환함에 따라 그 중요성을 계속해서 잃어가고 있습니다.
혁신이 다시 활기를 띠고 있습니다. 시카(Sika)사의 펠트 뒷면 처리형 자가 접착식 PVC는 기존의 용제계 접착제로는 대응하기 어려운 화씨 40도 미만의 환경에서 사용될 수 있도록 설계되었습니다. 한편, 칼라일(Carlisle)사의 ‘Sure-Weld TPO’는 ASTM 규격을 상회하는 인장 강도를 자랑합니다. KEE나 복합 시트와 같은 특수 혼합 제품은 시장 점유율이 그리 크지는 않지만, 내천공성 및 전기 절연성이 뛰어나기 때문에 그린 루프나 태양광 발전 일체형 시스템에 채택되는 사례가 점점 늘고 있습니다. 허리케인이 빈번하게 발생하는 지역의 시설에서 FM Global 클래스 90 인증이 필수화되고 있음에 따라, 이음매 용접 및 부풀음 시험 역량에 대한 투자가 현저히 증가하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 33.97%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.55%로 다른 모든 지역을 능가하는 성장이 예상됩니다. 전자, 전기차(EV), 제약 분야의 국경을 초월한 투자가 클린 루프용 PVC 시스템을 점점 더 선호하는 공장 건설을 주도하고 있습니다. 동시에 데이터센터의 수용 능력이 대폭 확대되면서, 각 시설에서는 무거운 공조 설비를 지탱하기 위해 견고한 저경사 지붕이 필요해지고 있습니다. 인도의 전례 없는 인프라 투자에 더해, 고온 지역에서의 쿨 루프 도입 의무화가 맞물려 해당 지역에서의 채택을 더욱 촉진하고 있습니다. 중국의 부동산 부문에서는 조정 국면이 나타나고 있지만, 방대한 기존 건축물의 개보수가 지속되면서 특히 비용 효율이 뛰어난 EPDM 오버레이에 대한 수요를 계속 뒷받침하고 있습니다.
북미는 단층막 시장에서 두 번째로 큰 규모를 자랑합니다. 미국의 비주거용 지붕 분야는 성장을 계속하고 있으며, 프로젝트 포트폴리오에서 단층 구조가 중심적인 역할을 하고 있습니다. ‘타이틀 24’의 쿨 루프 의무화 및 허리케인 대책 기준인 ‘FORTIFIED’에 힘입어 TPO 및 PVC의 채택이 가속화되고 있습니다. 캐나다는 연방 정부의 인프라 투자 혜택을 받고 있는 반면, 멕시코에서는 자동차 및 전자 산업의 니어쇼어링 붐이 누에보 레온주와 과나후아토주 등에서 물류 단지 건설을 견인하고 있습니다. 그러나 특히 앨버타주, 브리티시컬럼비아주 및 미국의 선벨트 지역에서는 인력 부족으로 인해 리드타임이 길어지고 인건비가 급등하고 있습니다.
유럽은 모순으로 가득 찬 상황에 직면해 있습니다. 유럽연합 집행위원회 규정 2023/923에 따른 PVC 내 납 함량 규제 강화와 일부 지방 자치단체의 공공 건축물에 대한 PVC 지붕 사용 금지 조치로 인해, 시장은 TPO나 EPDM과 같은 대체 소재로 전환되고 있습니다. 한편, EU의 ‘제로 에미션 건축’ 의무화로 인해 특히 독일, 프랑스, 영국에서 개보수 공사가 급증하고 있습니다. 이들 국가에서는 부동산 소유주가 탄소 배출 감축 목표를 달성하기 위해 기존 지붕에 반사성 TPO를 시공하고 있습니다. 그러나 독일의 견습 기술자 감소와 영국의 브렉시트 이후 노동력 부족으로 인해 프로젝트 공사 기간이 길어지고 있습니다. 러시아에서는 제재로 인한 시장 위축으로 현지에서 생산된 EPDM 및 아스팔트가 선호되고 있습니다. 반면, 브라질, 사우디아라비아, 남아프리카공화국 등의 국가에서는 공항, 경기장, 유틸리티 관련 프로젝트를 원동력으로 선택적인 성장이 나타나고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the single ply membrane market size is estimated at USD 20.40 billion in 2026, and is expected to reach USD 27.15 billion by 2031, at a CAGR of 5.88% during the forecast period (2026-2031).
This report Segments the Industry Into Type (Ethylene Propylene Diene Monomer (EPDM), Thermoplastic Polyolefin (TPO), Poly Vinyl Chloride (PVC), Modified Bitumen, and Other Types), Application (Residential, Commercial, Institutional, and Infrastructural), Construction Type (New Construction and Refurbished), and Geography (Asia-Pacific, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Single Ply Membrane Market Trends and Insights
Rising Demand for Energy-Efficient and Cool-Roof Systems
Cool-roof membranes enable ENERGY STAR certification and LEED v4 points, all while meeting the Cool Roof Rating Council's stringent aged-reflectance standards. California's Title 24 code now mandates cool roofs on every low-slope commercial building, pushing contractor lead times for white TPO and PVC beyond eight weeks in late 2024. The U.S. EPA is expanding its Heat-Island Reduction Program to 15 new metro areas in 2026, triggering municipal subsidies for reflective retrofits on government facilities. Large-scale solar developers favor bright membranes that limit thermal stress on photovoltaic modules, a requirement addressed by Carlisle's SeamShield coating that pairs high albedo with induction-welded seams.
Commercial Reroofing Boom in North America
In 2024, the U.S. nonresidential roofing sector experienced significant growth, supported by aging low-slope stock. Contractors predominantly favor single-ply membranes, which constitute the majority of their project mix. Within this category, TPO holds the largest share, followed by PVC and EPDM. Carlisle's construction-materials revenue was bolstered by a strong EBITDA margin, thanks to normalized distributor inventories and robust contractor backlogs. GAF's upcoming shingle plant in Newton, Kansas, announced in March 2024 and set to break ground in June 2025, underscores the company's faith in sustained reroofing demand. However, with automation in play, the workforce expansion is limited to a modest number of roles.
Polymer and Additive Price Volatility
In June 2025, PVC resin prices in the U.S. declined year over year. Meanwhile, European prices increased, tightening the margins for global producers. Propylene, the feedstock for TPO, experienced fluctuations throughout 2024, influenced by turnarounds at Gulf Coast refineries. Ethylene prices for EPDM also varied, primarily due to outages at crackers. After peaking in 2023, titanium-dioxide costs stabilized in 2025. However, with supply concentrated among just three global vendors, an oligopoly pricing power remains intact. In a strategic move, major membrane producers are securing multi-year resin contracts. These contracts, featuring floor-and-ceiling clauses, shield a significant portion of their feedstock exposure but cap potential gains when spot prices dip.
Other drivers and restraints analyzed in the detailed report include:
- Urbanization-Led Construction Up-Cycle in Asia-Pacific
- Government Incentives and Stricter Green-Building Codes
- Shortage of Certified Single-Ply Installers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Thermoplastic Polyolefin is projected to post a 7.01% CAGR from 2026-2031, the fastest rate among material classes, buoyed by labor-saving 16-foot rolls and stricter cool-roof codes. Poly Vinyl Chloride retained a 36.39% single ply membrane market share in 2025, protected by strong chemical resistance and fire-safety credentials, yet municipal bans in Germany, France, and Nordic countries are eroding its European footprint. Ethylene Propylene Diene Monomer remains popular for warehouse roofs where capital cost eclipses reflectivity, although EPDM's darker color disqualifies it from many utility rebates. Modified bitumen continues to lose relevance as contractors migrate toward hot-air-welded TPO solutions that cut installation schedules.
Innovation is witnessing a resurgence. Sika's felt-back self-adhered PVC is designed for sub-40 °F applications, where traditional solvent-based adhesives falter. Meanwhile, Carlisle's Sure-Weld TPO boasts tensile strengths exceeding ASTM standards. While specialty blends like KEE and composite sheets command a modest share, they're increasingly chosen for green roofs and photovoltaic-integrated setups due to their puncture resistance and electrical insulation properties. With FM Global Class 90 ratings becoming essential for facilities in hurricane-prone areas, there's a noticeable uptick in investments towards seam-welding and uplift-test capabilities.
Complete Report Scope:
- By Type
- Ethylene Propylene Diene Monomer (EPDM)
- Thermoplastic Polyolefin (TPO)
- Poly Vinyl Chloride (PVC)
- Modified Bitumen
- Other Types
- By Application
- Residential
- Commercial
- Institutional
- Infrastructure
- By Construction Type
- New Construction
- Refurbished/Renovation
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific controlled 33.97% of global revenue in 2025 and is expected to outpace every other region with a 6.55% CAGR to 2031. Cross-border investments in electronics, electric vehicles (EVs), and pharmaceuticals are driving the construction of factories that increasingly favor clean-roof PVC systems. Concurrently, data centers have boosted their capacity significantly, each requiring sturdy low-slope roofs to support heavy HVAC equipment. India's unprecedented infrastructure allocations, coupled with mandatory cool-roof initiatives in hotter regions, are further propelling regional adoption. Despite a pullback in China's real estate sector, the ongoing renovation of its vast existing stock continues to bolster demand, particularly for cost-effective EPDM overlays.
North America stands as the second-largest market for single-ply membranes. The U.S. nonresidential roofing sector is experiencing growth, with single-ply assemblies taking center stage in project portfolios. The push from Title 24 cool-roof mandates, alongside FORTIFIED hurricane standards, is accelerating the adoption of TPO and PVC. While Canada reaps the benefits of federal infrastructure investments, Mexico's automotive and electronics near-shoring boom is driving the construction of logistics parks in states like Nuevo Leon and Guanajuato. However, labor shortages are extending lead times and inflating labor costs, particularly in Alberta, British Columbia, and the U.S. Sunbelt.
Europe is navigating a landscape of contradictions. The tightening of lead limits in PVC by Commission Regulation 2023/923, along with bans on PVC roofs for public buildings in several municipalities, is pushing the market towards TPO and EPDM alternatives. On the other hand, the EU's zero-emission-building mandate is spurring a surge in retrofit activities, especially in Germany, France, and the U.K. Here, property owners are overlaying existing roofs with reflective TPO to align with carbon reduction targets. However, declining apprenticeship rates in Germany and labor shortages post-Brexit in the U.K. are extending project timelines. In Russia, due to market constraints from sanctions, there's a preference for locally produced EPDM and bitumen. Meanwhile, countries like Brazil, Saudi Arabia, and South Africa are witnessing selective growth, driven by projects in airports, stadiums, and utilities.
- Bauder GmbH
- BMI Group (Icopal)
- Carlisle SynTec Systems
- Dow
- Duro-Last Inc.
- Firestone Building Products Company LLC
- GAF
- Godfrey Roofing Inc.
- Holcim Elevate (Firestone)
- IKO Industries
- Johns Manville
- Kingspan Group
- Owens Corning
- Protan AS
- RENOLIT SE
- Seaman Corporation
- Sika AG
- Soprema Group
- Versico Roofing Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for energy-efficient and cool-roof systems
- 4.2.2 Commercial reroofing boom in North America
- 4.2.3 Urbanisation-led construction up-cycle in Asia-Pacific
- 4.2.4 Government incentives and stricter green-building codes
- 4.2.5 Adoption of 16-ft wide TPO rolls cuts labour 15-20%
- 4.3 Market Restraints
- 4.3.1 Polymer and additive price volatility
- 4.3.2 Shortage of certified single-ply installers
- 4.3.3 Municipal PVC bans in parts of EU
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Ethylene Propylene Diene Monomer (EPDM)
- 5.1.2 Thermoplastic Polyolefin (TPO)
- 5.1.3 Poly Vinyl Chloride (PVC)
- 5.1.4 Modified Bitumen
- 5.1.5 Other Types
- 5.2 By Application
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Institutional
- 5.2.4 Infrastructure
- 5.3 By Construction Type
- 5.3.1 New Construction
- 5.3.2 Refurbished/Renovation
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 Italy
- 5.4.3.4 France
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Bauder GmbH
- 6.4.2 BMI Group (Icopal)
- 6.4.3 Carlisle SynTec Systems
- 6.4.4 Dow
- 6.4.5 Duro-Last Inc.
- 6.4.6 Firestone Building Products Company LLC
- 6.4.7 GAF
- 6.4.8 Godfrey Roofing Inc.
- 6.4.9 Holcim Elevate (Firestone)
- 6.4.10 IKO Industries
- 6.4.11 Johns Manville
- 6.4.12 Kingspan Group
- 6.4.13 Owens Corning
- 6.4.14 Protan AS
- 6.4.15 RENOLIT SE
- 6.4.16 Seaman Corporation
- 6.4.17 Sika AG
- 6.4.18 Soprema Group
- 6.4.19 Versico Roofing Systems
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


