|
시장보고서
상품코드
2120465
북미의 플라스틱 뚜껑 및 마개 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Plastic Caps And Closures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
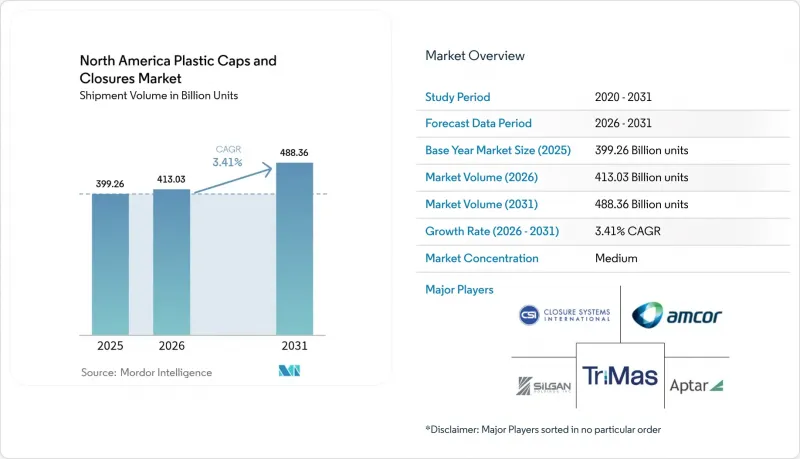
에 의하면, 북미의 플라스틱 뚜껑 및 마개 시장 규모는 2025년 3,992억 6,000만 개로 평가되었습니다. 2026년 4,130억 3,000만 개로부터, 2031년까지 4,883억 6,000만 개로 확대되고 2026-2031년까지 기간 CAGR은 3.41%를 나타낼 전망입니다.
본 보고서는 소재별(폴리에틸렌(PE), 폴리에틸렌 테레프탈레이트(PET), 기타), 유형별(나사식, 디스펜싱식, 비나사식, 기타), 최종 사용자 산업별(음료, 식품, 의약품 및 의료, 기타), 제조 공정별(사출 성형, 압축 성형, 기타), 지역별로 분류되어 있습니다. 시장 예측은 수량(개) 기준으로 제시되어 있습니다.
북미의 플라스틱 뚜껑 및 마개 시장 동향 및 인사이트
병입 음료 및 기능성 음료 수요 급증
2025년에는 기능성 음료의 신제품 출시 수가 전년 대비 23% 증가했으며, 15psi의 밀봉 강도를 유지하는 위조 방지 기능을 갖춘 28mm 및 38mm 뚜껑에 대한 수요가 가속화되었습니다. 일회용 생수병은 현재 해당 카테고리 매출의 62%를 차지하고 있으며, 각 브랜드는 개당 0.003달러의 원자재 비용을 절감할 수 있는 경량 뚜껑의 채택을 추진하고 있습니다. 스포츠 영양 식품 제조업체들은 역류로 인한 오염을 방지하는 실리콘 체크 밸브가 장착된 플립탑식 디스펜서를 표준화하고 있습니다. 미국에서는 2025년에 기능성 물의 1인당 섭취량이 14.7갤런에 달하고, 캐나다보다 50% 이상 높은 것으로 나타나, 이 나라가 뚜껑 출하량에 미치는 영향이 얼마나 큰지 여실히 드러나고 있습니다. 휴대성의 중요성과 건강 지향적인 제품 출시가 맞물리면서, 음료는 북미의 플라스틱 뚜껑 및 마개 시장의 중심을 계속 차지하고 있습니다.
온라인 의약품 및 영양보조식품 시장의 급속한 성장에 따른 CRC 수요 증가
2025년, 미국 온라인 약국의 매출액은 920억 달러에 달했으며, 처방약 병의 38%가 통신 판매를 통해 출하되었습니다. ‘독극물 방지 포장법’에 따라 유아용 안전 뚜껑의 채택이 의무화되어 있으며, 영양 보충제 판매업체들도 현재 ASTM D3475 프로토콜 E를 준수하는 고령자용 ‘돌리고 누르는’ 방식의 디자인을 채택하고 있습니다. 이를 통해 유아의 안전을 확보하면서도 성인의 개봉 성공률을 85%로 높이고 있습니다. AptarGroup은 GLP-1 제제의 포장량이 급증함에 따라 2025년 3분기 의약품용 뚜껑 출하량이 22% 증가했습니다. 고령화가 진행되고 광대역 보급률이 높은 플로리다주, 애리조나주, 캘리포니아주에서의 성장이 단기적인 상승 추세를 뒷받침하고 있습니다. 이러한 동향은 북미의 플라스틱 뚜껑 및 마개 시장에서 어린이 안전 제품의 프리미엄 위상을 더욱 공고히 하고 있습니다.
버진 수지에 대한 확대 생산자 책임(EPR) 수수료
2025년 이후, 미국 9개 주와 캐나다 4개 주에서는 재활용 체계 확충 자금을 조달하기 위해 버진 수지 뚜껑 1개당 0.02-0.04달러의 EPR(확대 생산자 책임) 수수료를 부과하고 있습니다. 메인주의 제도에서는 재생 소재를 100% 사용한 제품의 수수료가 면제되어 톤당 80-120달러의 비용 우위를 가져다주고 있지만, 북미의 식품 등급 재생 PP 공급량은 수요의 불과 56%만을 충족하고 있습니다. 브리티시컬럼비아주의 제도에서는 가구별 수거 개선을 위해 개당 0.015달러의 추가 요금이 부과됩니다. 법규제가 분산되어 있어 가공업체들은 SKU 및 재고 관리에 어려움을 겪고 있으며, 북미의 플라스틱 뚜껑 및 마개 시장 전체에서 간접비가 증가하고 있습니다.
부문별 분석
폴리에틸렌 테레프탈레이트(PET)로 만든 뚜껑은 2025년 출하량의 불과 12%를 차지했을 뿐이지만, 생수 제조업체들이 재활용 수율을 높이는 라이너리스 PET 뚜껑으로 전환을 추진함에 따라 2031년까지 연평균 4.31%의 성장이 예상됩니다. 폴리프로필렌(PP)은 그 차단성 덕분에 탄산음료의 산소 투과량을 하루 0.5cc 이하로 억제할 수 있어 여전히 46.47%의 점유율을 차지하며 시장을 독점하고 있습니다. 뚜껑을 재활용 소재 함유율 목표에 포함시키는 캘리포니아주 AB 793법에 따라, 실간(Silgan)사는 텍사스주의 3개 생산 라인을 재활용 PET 대응으로 개조하여 연간 생산 능력을 6,000만 개 확대했습니다.
식품 등급 재활용 PET의 경우, 톤당 200달러의 프리미엄을 붙여 장기 계약을 확보한 각 컨버터 기업들은 안정적인 공급을 유지하고 있습니다. 대조적으로, 멕시코에서는 재활용 인프라가 제한적이라는 점을 반영하여 여전히 78%가 버진 PP를 사용하고 있지만, 2025년 ‘국가 재활용 전략’에서는 2030년까지 재활용 소재 함유율 30%를 목표로 하고 있습니다. 따라서 북미의 플라스틱 뚜껑 및 마개 시장에서 소재 전환은 지역별로 고르지 않게 진행되고 있습니다.
2025년 출하량의 48.83%를 차지하는 나사식 뚜껑이 선두를 유지했으며, 청량음료의 압력 유지에 필수적입니다. 캐나다 보건부가 정한 대마초 식용 제품의 토크 임계값 규제와 미국 온라인 약국 시장의 성장에 힘입어, 어린이 안전(유아가 열기 어려운) 설계는 4.02%의 성장세를 보이고 있습니다. 아프터(Aptar)사의 ‘스퀴즈 앤 턴(Squeeze and Turn)’ 방식 CRC는 어린이 안전 기능을 저해하지 않으면서도 성인의 개봉 성공률을 92%로 높여, 얼리 어답터들의 관심을 모으고 있습니다.
출하량의 18%를 차지하는 디스펜싱 뚜껑은 한 손으로 열 수 있는 플립탑이 스포츠 음료에서 인기를 끌고 있으며, 특히 멕시코에서는 1회용 스포츠 음료가 연간 14%의 성장률을 보이고 있습니다. 나사가 없는 스냅온 유형은 전자상거래 운송 중 누출 문제로 인해 광범위한 보급이 저해되고 있어 여전히 틈새 시장으로 남아 있습니다. 이러한 경향은 북미의 플라스틱 뚜껑 및 마개 시장에서 부문의 다양성을 유지하기 위한 제품 고유의 성능 요건을 부각시키고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the North America plastic caps and closures market size is projected to expand from 399.26 billion units in 2025 and 413.03 billion units in 2026 to 488.36 billion units by 2031, registering a CAGR of 3.41% between 2026 and 2031.
This report is Segmented by Material (Polyethylene, Polyethylene Terephthalate, and More), Type (Threaded, Dispensing, Unthreaded, and More), End-User Industry (Beverage, Food, Pharmaceutical and Healthcare, and More), Manufacturing Process (Injection Molding, Compression Molding, and More), and Geography. The Market Forecasts are Provided in Terms of Volume (Units).
North America Plastic Caps And Closures Market Trends and Insights
Demand Surge for Bottled and Functional Beverages
Functional beverage launches jumped 23% year-over-year in 2025, accelerating demand for tamper-evident 28- and 38-millimeter closures that hold 15 psi seal integrity. Single-serve bottled water now captures 62% of category sales, pushing brands to specify lighter closures that trim material costs by USD 0.003 each. Sports-nutrition players are standardizing flip-top dispensers with silicone check valves that prevent backflow contamination. In the United States, per-capita intake of enhanced water climbed to 14.7 gallons in 2025, more than 50% higher than Canada, highlighting the country's outsized pull on closure volumes. The convergence of portability preferences and health-centric product launches keeps beverages at the core of the North America plastic caps and closures market.
On-line Pharma and Nutraceutical Boom Fuels CRC Demand
U.S. online pharmacy revenue reached USD 92 billion in 2025, channeling 38% of prescription bottles through mail order fulfillment. The Poison Prevention Packaging Act requires child-resistant closures, and nutraceutical sellers now apply senior-friendly squeeze-and-turn designs that meet ASTM D3475 Protocol E, improving adult-opening success to 85% while retaining child safety. AptarGroup recorded a 22% lift in pharmaceutical closure shipments in Q3 2025 as GLP-1 drug packaging volumes surged. Growth clusters in Florida, Arizona, and California, where aging populations intersect with broadband penetration, underpin near-term upside. These dynamics reinforce the premium positioning of child-resistant offerings within the North America plastic caps and closures market.
Extended Producer Responsibility Fees on Virgin Resin
Since 2025, nine U.S. states and four Canadian provinces have levied EPR fees of USD 0.02-0.04 per virgin-resin closure to finance recycling upgrades. Maine's program waives fees for 100% recycled content, conferring a USD 80-120 per-ton cost edge, yet the North American supply of food-grade recycled PP meets just 56% of demand. British Columbia's scheme adds USD 0.015 per unit to fund improvements to curbside collection. Fragmented statutes compel converters to juggle SKUs and inventory, raising overhead across the North America plastic caps and closures market.
Other drivers and restraints analyzed in the detailed report include:
- Brand-Owner Push for Tethered and E-commerce-Ready Closures
- Shift Toward PP Mono-Material Caps for Easier Recycling
- Rise of Stand-Up Pouches with Fitments Replacing Screw Caps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene terephthalate closures, although only 12% of 2025 shipments, are growing at 4.31% through 2031 as bottled-water producers convert to liner-free PET caps that improve recycling yields. Polypropylene still dominates with 46.47% share because its barrier properties keep oxygen ingress below 0.5 cc/day for carbonated drinks. California's AB 793, which counts closures in recycled-content targets, has prompted Silgan to re-tool three Texas lines for recycled PET, adding 60 million units of annual capacity.
Converters that secure long-term contracts for food-grade recycled PET at USD 200-per-ton premiums are safeguarding supply. In contrast, Mexico remains 78% virgin PP, reflecting limited recycling infrastructure, although the 2025 National Recycling Strategy targets 30% recycled content by 2030. Material transitions therefore proceed unevenly across the North America plastic caps and closures market.
Threaded closures led with 48.83% of 2025 volume, vital for pressure retention in soft drinks. Child-resistant designs are advancing at 4.02%, aided by Health Canada's torque threshold rules for cannabis edibles and U.S. e-pharmacy growth. Aptar's squeeze-and-turn CRC raised adult-opening success to 92% without compromising child resistance, capturing early adopter interest.
Dispensing caps, 18% of shipments, are gaining popularity in sports beverages where flip-tops support one-hand use, particularly in Mexico, where single-serve sports drinks grow 14% annually. Unthreaded snap-on variants remain niche because leakage during e-commerce transit limits broader acceptance. These patterns underscore product-specific performance needs that sustain segment diversity within the North America plastic caps and closures market.
Complete Report Scope:
- By Material
- Polyethylene (PE)
- Polyethylene Terephthalate (PET)
- Polypropylene (PP)
- Other Materials
- By Type
- Threaded
- Dispensing
- Unthreaded
- Child-Resistant
- By End-user Industry
- Beverage
- Bottled Water
- Soft Drinks
- Spirits
- Other Beverages
- Food
- Pharmaceutical and Healthcare
- Cosmetics and Toiletries
- Household Chemicals
- Other Industries
- Beverage
- By Manufacturing Process
- Injection Molding
- Compression Molding
- 3-D Printing / Rapid Prototyping
- Other Manufacturing Process
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Silgan Holdings Inc.
- Amcor plc
- AptarGroup Inc.
- Closure Systems International Inc.
- TriMas Corporation
- Guala Closures SpA
- Tetra Pak Group
- O.Berk Company LLC
- BERICAP Holding GmbH
- Pano Cap Canada Ltd
- Erie Molded Plastics Inc.
- Crown Holdings Inc.
- Phoenix Closures Inc.
- Mold-Rite Plastics LLC
- Comar LLC
- Husky Technologies
- SACMI Imola S.C.
- Sonoco Products Company
- Plastipak Holdings Inc.
- Albea Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand Surge for Bottled and Functional Beverages
- 4.2.2 Brand-owner Push for Tethered / E-commerce-ready Closures
- 4.2.3 Shift Toward PP Mono-material Caps for Easier Recycling
- 4.2.4 On-line Pharma and Nutraceutical Boom Fuels CRC Demand
- 4.2.5 AI-enabled In-line Vision Lowers Defect Rates and Costs
- 4.2.6 Smart Caps with Embedded NFC/QR Authentication
- 4.3 Market Restraints
- 4.3.1 Extended Producer Responsibility (EPR) Fees on Virgin Resin
- 4.3.2 Rise of Stand-up Pouches with Fitments Replacing Screw Caps
- 4.3.3 U.S./Canada rPET Content Mandates Squeeze Virgin PP Demand
- 4.3.4 Beverage Brand Trials of Aluminium Crown Re-seals
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Material
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polyethylene Terephthalate (PET)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Other Materials
- 5.2 By Type
- 5.2.1 Threaded
- 5.2.2 Dispensing
- 5.2.3 Unthreaded
- 5.2.4 Child-Resistant
- 5.3 By End-user Industry
- 5.3.1 Beverage
- 5.3.1.1 Bottled Water
- 5.3.1.2 Soft Drinks
- 5.3.1.3 Spirits
- 5.3.1.4 Other Beverages
- 5.3.2 Food
- 5.3.3 Pharmaceutical and Healthcare
- 5.3.4 Cosmetics and Toiletries
- 5.3.5 Household Chemicals
- 5.3.6 Other Industries
- 5.3.1 Beverage
- 5.4 By Manufacturing Process
- 5.4.1 Injection Molding
- 5.4.2 Compression Molding
- 5.4.3 3-D Printing / Rapid Prototyping
- 5.4.4 Other Manufacturing Process
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Silgan Holdings Inc.
- 6.4.2 Amcor plc
- 6.4.3 AptarGroup Inc.
- 6.4.4 Closure Systems International Inc.
- 6.4.5 TriMas Corporation
- 6.4.6 Guala Closures SpA
- 6.4.7 Tetra Pak Group
- 6.4.8 O.Berk Company LLC
- 6.4.9 BERICAP Holding GmbH
- 6.4.10 Pano Cap Canada Ltd
- 6.4.11 Erie Molded Plastics Inc.
- 6.4.12 Crown Holdings Inc.
- 6.4.13 Phoenix Closures Inc.
- 6.4.14 Mold-Rite Plastics LLC
- 6.4.15 Comar LLC
- 6.4.16 Husky Technologies
- 6.4.17 SACMI Imola S.C.
- 6.4.18 Sonoco Products Company
- 6.4.19 Plastipak Holdings Inc.
- 6.4.20 Albea Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment