|
시장보고서
상품코드
2124049
미국의 플라스틱 뚜껑 및 마개 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States (US) Plastic Caps And Closures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
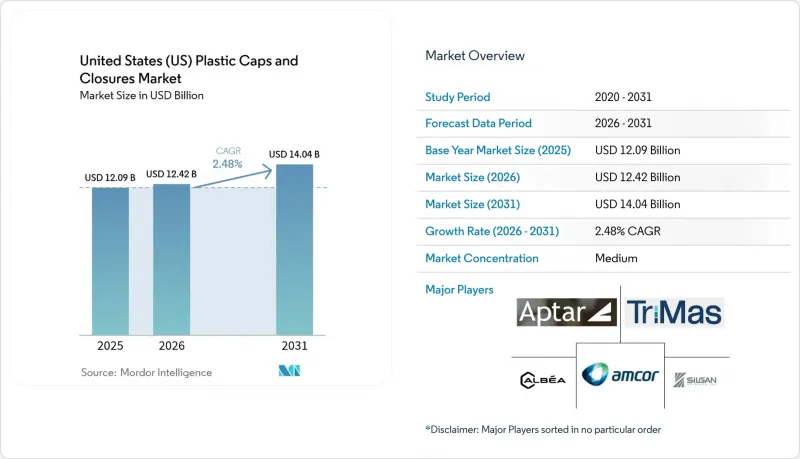
에 의하면, 미국의 플라스틱 뚜껑 및 마개 시장 규모는 2025년 120억 9,000만 달러로 평가되었고, 2026년 124억 2,000만 달러에서 2031년까지 140억 4,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 2.48%를 나타낼 전망입니다.
본 보고서는 소재별(폴리에틸렌 테레프탈레이트(PET), 폴리프로필렌(PP) 등), 최종 사용자 산업별(음료, 식품 등), 뚜껑 유형별(나사식 뚜껑, 테더가 부착된 뚜껑 등), 제조 기술별(사출 성형, 압축 성형 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국(US)의 플라스틱 뚜껑 및 마개 시장 동향과 인사이트
편리한 포장 음료에 대한 수요 급증
싱글 서브 커피, 기능성 물, 단백질 쉐이크에 대한 수요 증가에 따라 2025년 즉석 음료 출하량은 7.2% 증가했으며, 전미 음료 거래의 34%를 차지하는 편의점에서 플립탑 및 스냅온 방식의 스포츠 뚜껑 진열 공간이 확대되었습니다. Keurig Dr Pepper사의 보고서에 따르면, 2025년에는 재밀봉 기능이 소비자의 구매 결정에 62%의 영향을 미치고 있으며, 이는 2년 동안 8포인트 상승한 수치로, 뚜껑의 기능성이 브랜드 전략의 중요한 요소임을 여실히 보여주고 있습니다. 이에 대응해 각 뚜껑 공급업체들은 전자상거래 배송 시 누출을 방지하기 위해 실리콘 밸브를 내장한 폴리프로필렌 재질의 플립탑 뚜껑을 개발했습니다. 음료 브랜드들이 소셜 미디어 트렌드에 발맞추어 한정판 맛 출시를 가속화하는 가운데, 성형 제조업체와 조기에 뚜껑 사양을 공동 개발함으로써 상품화까지의 기간을 단축하고 있습니다. 이러한 요인들이 맞물리면서 탄산 음료의 품질을 유지하기 위한 고처리량 성형 셀과 정밀한 게이트 설계에 대한 수요가 증가하고 있습니다.
전자상거래의 성장이 변조 방지 설계를 필요로 하고 있습니다.
2025년에는 온라인 식료품 판매 시장 침투율이 미국 식품 및 음료 총매출의 12.3%를 나타낸 것으로 평가되었으며, 취급 공정이 증가함에 따라 변조 위험이 높아지고 있습니다. 연방 규정에서는 이미 일반의약품에 대해 개봉 흔적을 확인할 수 있는 표시를 의무화하고 있지만, 대형 전자상거래 업체들도 현재 고급 식용유나 영양 보충제 분말에 대해 유사한 요건을 요구하고 있습니다. 2025년 3월에 출시된 앱터 그룹의 ‘SimpliSqueeze’ 밸브는 파단 링을 일체화하여 유도 씰을 불필요하게 만들었고, 조립 라인의 복잡성을 20% 줄였습니다. 또한, 풀필먼트 센터에서는 기존 매장 진열대 높이의 2배에 해당하는 1.2미터 낙하 시험을 견딜 수 있는 뚜껑을 지정하고 있으며, 이에 따라 성형 제조업체는 벽 두께를 0.15mm 더 두껍게 하고, 영하의 온도에서도 연성을 유지하는 내충격성 폴리프로필렌 등급을 채택하고 있습니다. 이러한 성능 향상으로 인해 뚜껑 1개당 평균 수지 사용량이 증가하여, 패키지의 다른 부분에서 실현된 경량화 효과를 일부 상쇄하고 있습니다.
수지 가격 변동
2025년, 폴리프로필렌의 현물 가격은 파운드당 0.62달러에서 0.81달러 사이에서 변동했습니다. 이는 원유 가격 변동 및 멕시코만 연안 지역의 예기치 못한 크래커 가동 중단과 연동된 것으로, ICIS.COM의 가격 에스컬레이터가 발동되지 않는 한, 이러한 변동으로 인해 컨버터의 EBITDA는 200-300 베이시스 포인트 하락했습니다. 수지 가격 변동 위험을 헤지할 규모의 여력이 없는 소규모 성형 업체들은 운전 자금 부족에 직면했으며, 이는 베리 세계(Berry Global)이 2024년에 지역 공장 3곳을 인수하는 등 업계 재편의 요인이 되었습니다. 선물 임베디드는 이익률을 확보하는 한편, 창고 용량을 묶어두게 되어 20-30%의 프리미엄으로 거래되는 바이오 수지를 시험해 볼 수 있는 유연성을 제한하고 있습니다. HDPE도 유사한 가격 변동을 보였으나, 2025년 하반기 새로운 에탄 크래커의 가동으로 공급이 완화되었습니다. 수지 가격의 지속적인 변동은 이미 고품질 컴파운드를 필요로 하는 테더형 뚜껑용 금형이나 NFC 지원 스마트 뚜껑의 장기 예산 수립을 어렵게 만들고 있습니다.
부문 분석
폴리프로필렌은 고캐비테이션 사출 성형 금형에 적합한 용융 유동 속도에 힘입어 2025년 출하량의 43.21%를 차지했습니다. 한편, 소비재(CPG) 기업들이 검증 가능한 Scope 3 배출 감축을 추구하는 가운데, 바이오 PET는 연평균 성장률(CAGR) 3.56%로 가장 빠른 성장이 예상됩니다. 다니머 사이언티피크(Danimer Scientific)의 PHA 뚜껑은 2025년 4월 서부 해안의 콤부차 브랜드를 통해 출시되어 소매 가격 대비 25%의 프리미엄을 실현함과 동시에 해양 생분해성을 입증했습니다. 미국 바이오 PET 플라스틱 뚜껑 및 마개 시장 규모는 화석 원료 가격 급등으로부터 보호해 주는 안정적인 원료 공급 계약에 힘입어 확대될 것으로 전망됩니다. 플라스틱 재활용업자 협회(Association of Plastic Recyclers)는 2025년 천연 HDPE 뚜껑의 선별 정확도가 92%였습니다고 보고했으며, 이는 유제품 및 가정용 화학제품 공급망에서 HDPE의 역할을 뒷받침하는 것입니다. 오리진 머티리얼즈(Origin Materials)의 탄소 네거티브 PET는 2025년 9월, 1억 5,000만 달러 규모의 음료용 판매 계약을 체결했습니다. 이는 2027년까지 주류 시장에서 규모가 확대될 것임을 시사하며, 수량 기준 가격 차이가 기존 폴리머와의 격차를 좁힌다면 미국 플라스틱 뚜껑 및 마개 시장에서 바이오 수지의 점유율이 상승할 전망입니다.
캘리포니아주 의회 법안 1200호는 2030년까지 음료용 뚜껑에 15%의 PCR(재활용 플라스틱) 사용을 의무화하고 있어, 간접적으로 폴리프로필렌의 폐쇄형 순환 재활용을 촉진하고 있습니다. 성형 업체에 따르면, 25%의 PCR PP를 사용할 경우 인장 강도가 6-8% 저하되므로 벽 두께를 두껍게 해야 하며, 이로 인해 경량화에 따른 이점이 부분적으로 상쇄됩니다. 아반티움(Avantium)사의 폴리에틸렌 프라노에이트는 여전히 파일럿 규모에 머물러 있지만, 뛰어난 기체 차단성 덕분에 2028년까지 탄산음료용 틈새 시장이 형성될 가능성이 있습니다. 수지 선택의 폭이 넓어짐에 따라, 금형용 강재 선정과 게이트 설계가 컨버터가 비용이 많이 드는 핫러너를 재구축하지 않고도 기존 등급과 바이오 등급을 전환할 수 있는지 여부를 좌우하게 될 것입니다.
음료 분야는 여전히 주력 분야로, 2025년 출하량의 57.21%를 차지했습니다. 그러나 고급 스킨케어 제품에 대한 에어리스 펌프 수요로 인해, 화장품 및 위생용품 뚜껑 및 마개 시장은 2031년까지 연평균 성장률(CAGR) 3.71%로 성장할 전망입니다. 에어리스 시스템이 유통 기한을 연장하고 방부제 사용을 줄인다는 마케팅적 어필이 성분에 민감한 소비자들의 공감을 얻고 있어, 미국의 화장품용 플라스틱 뚜껑 및 마개 시장 규모는 확대되고 있습니다. 밀키트의 보급으로 2025년에는 플립탑 방식의 식품용 뚜껑 출하량이 9.3% 증가했습니다. 한편, 헨켈(Henkel)사의 ‘트위스트 앤드 메저(Twist and Measure)’ 뚜껑은 세제 낭비를 12% 줄여 그 기능적 가치를 부각시키고 있습니다. 의약품용 뚜껑은 출하량의 고작 10%에 불과했으나, ISO 인증을 받은 문서를 통해 가격 결정력을 유지하고 있었습니다. 명품 브랜드들은 루프(Loop)사와 제휴하여 리필용으로 반환되는 자석식 나사 뚜껑을 시범 도입함으로써, 제품 수명 주기 전반에 걸쳐 일회용 플라스틱을 70% 줄였습니다. 이러한 변화들이 맞물리면서 수요는 대량 생산되는 탄산음료 및 생수 제품 라인을 넘어 다양화되고 있으며, 1인당 청량음료 소비량이 정체된 상황에서도 미국 플라스틱 뚜껑 및 마개 시장의 충격을 완화하는 역할을 하고 있습니다.
리필 시스템은 판매량 증가를 저해하는 한편, 복잡한 구조와 금속 재질의 오버뚜껑을 통해 더 높은 단가 이익률을 실현하고 있습니다. 어린이 안전 뚜껑이 장착된 의약품용 뚜껑은 개당 0.08-0.12달러의 매출 증가를 가져와, 범용 용도와 특수 용도 간의 세분화를 강화하고 있습니다. 따라서 미국의 플라스틱 뚜껑 및 마개 산업은 두 가지 길을 걷게 될 미래로 나아가고 있습니다. 하나는 몇 센트의 차이가 중요한 초고속 스크류 뚜껑이 주류를 이루는 길이고, 다른 하나는 고급 화장품 및 의약품 마개가 두 자릿수 이익률을 가져다주는 길입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the United States plastic caps and closures market size is projected to expand from USD 12.09 billion in 2025 and USD 12.42 billion in 2026 to USD 14.04 billion by 2031, registering a CAGR of 2.48% between 2026 to 2031.
This report is Segmented by Material (Polyethylene Terephthalate (PET), Polypropylene (PP), and More), End-User Industry (Beverage, Food, and More), Cap Type (Screw Closures, Tethered Caps, and More), and Manufacturing Technology (Injection Molding, Compression Molding, and More). The Market Forecasts are Provided in Value (USD).
United States (US) Plastic Caps And Closures Market Trends and Insights
Surge in Demand for Convenient Packaged Beverages
Single-serve coffee, functional waters, and protein shakes lifted 2025 unit volumes for ready-to-drink beverages by 7.2%, expanding shelf space for flip-top and snap-on sports caps in convenience stores that account for 34% of national beverage transactions. Keurig Dr Pepper reported that resealability influenced 62% of consumer purchase decisions in 2025, up eight percentage points in two years, highlighting closure functionality as a brand lever. Closure suppliers responded with polypropylene flip-tops integrating silicone valves to avoid leaks during e-commerce parcel drops. As beverage brands accelerate limited-edition flavors tied to social-media trends, early co-development of closure specifications with molders trims commercialization timelines. These factors collectively reinforce demand for high-throughput molding cells and precise gating that maintain carbonation integrity.
Growth of E-Commerce Requiring Tamper-Evident Designs
Online grocery penetration reached 12.3% of total U.S. food and beverage sales in 2025, adding extra handling touchpoints that elevate tampering risk. Federal rules already oblige over-the-counter drugs to display visible evidence of entry, and large e-tailers now extend the same expectation to premium food oils and nutritional powders. AptarGroup's SimpliSqueeze valve, launched in March 2025, integrates a breakaway ring, eliminates induction seals, and cuts assembly-line complexity by 20%. Fulfillment centers also specify closures that survive 1.2-meter drop tests, twice the height of conventional store shelving, prompting molders to thicken walls by 0.15 millimeters and adopt impact-modified polypropylene grades that remain ductile at sub-zero temperatures. These performance upgrades enlarge the average resin requirement per closure, partially offsetting lightweighting gains elsewhere in the package.
Volatility in Resin Prices
Polypropylene spot quotes swung from USD 0.62 to 0.81 per pound during 2025, tracking crude volatility and unplanned cracker outages along the Gulf Coast, a shift that shaved 200-300 basis points off converter EBITDA unless price escalators kicked in ICIS.COM. Small molders lacking scale to hedge resin exposure faced working-capital strain, motivating consolidation such as Berry Global's 2024 purchase of three regional plants. Forward-buying locks in margins yet ties up warehouse capacity, limiting flexibility to trial biobased resins that trade at 20-30% premiums. HDPE displayed similar turbulence before new ethane-cracker capacity eased supply in late 2025. Persistent resin swings complicate long-term budgeting for tethered-cap tooling and NFC-enabled smart closures that already demand higher-grade compounds.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Tethered Cap Legislation
- Expanding Pharmaceutical Packaging Requirements
- Competition From Sustainable Alternative Materials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polypropylene captured 43.21% of 2025 shipments, underpinned by melt-flow rates that suit high-cavitation injection molds. Biobased PET, however, is positioned for the fastest climb at 3.56% CAGR, as CPG firms pursue verifiable scope-3 cuts. Danimer Scientific's PHA closures launched with a West Coast kombucha label in April 2025, commanding a 25% shelf premium and validating marine-biodegradation claims. The United States plastic caps and closures market size for biobased PET is projected to expand alongside secure feedstock contracts that shield against fossil-feedstock price spikes. The Association of Plastic Recyclers reported 92% sortation accuracy for natural HDPE caps in 2025, reinforcing HDPE's role in dairy and household-chemical supply chains. Origin Materials' carbon-negative PET secured a USD 150 million beverage offtake in September 2025, signaling mainstream scaling by 2027 and lifting the United States plastic caps and closures market share for bio-resins once volume pricing narrows the gap with conventional polymers.
California Assembly Bill 1200 requires 15% PCR in beverage closures by 2030, indirectly encouraging closed-loop polypropylene streams. Molders report tensile-strength losses of 6-8% when running 25% PCR PP, requiring thicker walls that partially offset weight-reduction gains. Avantium's polyethylene furanoate remains in pilot scale, but its superior gas barrier may create a niche for carbonated drinks by 2028. As resin options proliferate, tool-steel selection and gate design will dictate whether converters can switch between conventional and bio-grades without costly hot-runner rebuilds.
Beverages remained the anchor, controlling 57.21% of 2025 volume; yet airless pump demand from prestige skincare pushes cosmetics and toiletries closures toward a 3.71% CAGR through 2031. The United States plastic caps and closures market size for cosmetics is expanding as airless systems extend shelf life and reduce preservatives, a marketing claim resonating with ingredient-conscious consumers. Meal-kit adoption lifted flip-top food closures 9.3% in 2025, while Henkel's twist-and-measure cap cut detergent waste 12%, underscoring functional value. Pharmaceutical caps generated only 10% of units yet carried pricing power due to ISO-validated documentation. Luxury brands partnered with Loop to trial magnetic screw closures returned for refill, reducing single-use plastic by 70% over a product's life. Collectively, these shifts diversify demand beyond high-volume soda and water lines, buffering the United States plastic caps and closures market against flat per-capita soft-drink consumption.
Refill systems challenge volume growth but unlock higher unit margins through complex mechanisms and metallic overcaps. Child-resistant pharmaceutical closures added a revenue uplift of USD 0.08-0.12 per piece, reinforcing segmentation between commodity and specialty applications. The United States plastic caps and closures industry therefore navigates a dual-track future: one path dominated by ultra-high-speed screw caps where pennies matter, and another where premium cosmetics and drug closures command double-digit margins.
Complete Report Scope:
- By Material
- Polyethylene Terephthalate (PET)
- Polypropylene (PP)
- Low-Density Polyethylene (LDPE)
- High-Density Polyethylene (HDPE)
- Other Materials
- By End-User Industry
- Beverage
- Food
- Pharmaceutical and Healthcare
- Cosmetics and Toiletries
- Household Chemicals
- Other End-User Industries
- By Cap Type
- Screw Closures
- Tethered Caps
- Flip-Top and Snap-On Caps
- Child-Resistant Closures
- Luxury/Premium Decorative Closures
- Dispensing Caps
- By Manufacturing Technology
- Injection Molding
- Compression Molding
- 3-Piece and In-Line Assembly
- Digitally Printed Smart Closures
List of Companies Covered in this Report:
- Silgan Holdings Inc.
- AptarGroup, Inc.
- Amcor plc
- Albea S.A.
- TriMas Corporation
- Tetra Pak International S.A.
- Guala Closures S.p.A.
- MJS Packaging, Inc.
- O. Berk Company, LLC
- Closure Systems International, Inc.
- BERICAP GmbH & Co. KG
- Crown Holdings, Inc.
- Evergreen Packaging LLC
- Phoenix Closures, Inc.
- Portola Packaging, Inc.
- Plastipak Packaging, Inc.
- Mold-Rite Plastics, LLC
- Smurfit WestRock
- SIG Combibloc Group AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Demand for Convenient Packaged Beverages
- 4.2.2 Expanding Pharmaceutical Packaging Requirements
- 4.2.3 Shift Toward Lightweight Plastic Over Metal Closures
- 4.2.4 Growth of E-commerce Requiring Tamper-Evident Designs
- 4.2.5 Adoption of Tethered Cap Legislation
- 4.2.6 Reshoring via High-Speed Compression-Molding Capacity
- 4.3 Market Restraints
- 4.3.1 Volatility in Resin Prices
- 4.3.2 Competition From Sustainable Alternative Materials
- 4.3.3 Prospective Federal Single-Use-Plastic Restrictions
- 4.3.4 Micro-Plastic Scrutiny Driving Liner-Less Closures
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Degree of Competition
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Polyethylene Terephthalate (PET)
- 5.1.2 Polypropylene (PP)
- 5.1.3 Low-Density Polyethylene (LDPE)
- 5.1.4 High-Density Polyethylene (HDPE)
- 5.1.5 Other Materials
- 5.2 By End-User Industry
- 5.2.1 Beverage
- 5.2.2 Food
- 5.2.3 Pharmaceutical and Healthcare
- 5.2.4 Cosmetics and Toiletries
- 5.2.5 Household Chemicals
- 5.2.6 Other End-User Industries
- 5.3 By Cap Type
- 5.3.1 Screw Closures
- 5.3.2 Tethered Caps
- 5.3.3 Flip-Top and Snap-On Caps
- 5.3.4 Child-Resistant Closures
- 5.3.5 Luxury/Premium Decorative Closures
- 5.3.6 Dispensing Caps
- 5.4 By Manufacturing Technology
- 5.4.1 Injection Molding
- 5.4.2 Compression Molding
- 5.4.3 3-Piece and In-Line Assembly
- 5.4.4 Digitally Printed Smart Closures
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Silgan Holdings Inc.
- 6.4.2 AptarGroup, Inc.
- 6.4.3 Amcor plc
- 6.4.4 Albea S.A.
- 6.4.5 TriMas Corporation
- 6.4.6 Tetra Pak International S.A.
- 6.4.7 Guala Closures S.p.A.
- 6.4.8 MJS Packaging, Inc.
- 6.4.9 O. Berk Company, LLC
- 6.4.10 Closure Systems International, Inc.
- 6.4.11 BERICAP GmbH & Co. KG
- 6.4.12 Crown Holdings, Inc.
- 6.4.13 Evergreen Packaging LLC
- 6.4.14 Phoenix Closures, Inc.
- 6.4.15 Portola Packaging, Inc.
- 6.4.16 Plastipak Packaging, Inc.
- 6.4.17 Mold-Rite Plastics, LLC
- 6.4.18 Smurfit WestRock
- 6.4.19 SIG Combibloc Group AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment