

|
시장보고서
상품코드
2120504
북미의 플라스틱 병 및 용기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Plastic Bottles And Containers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
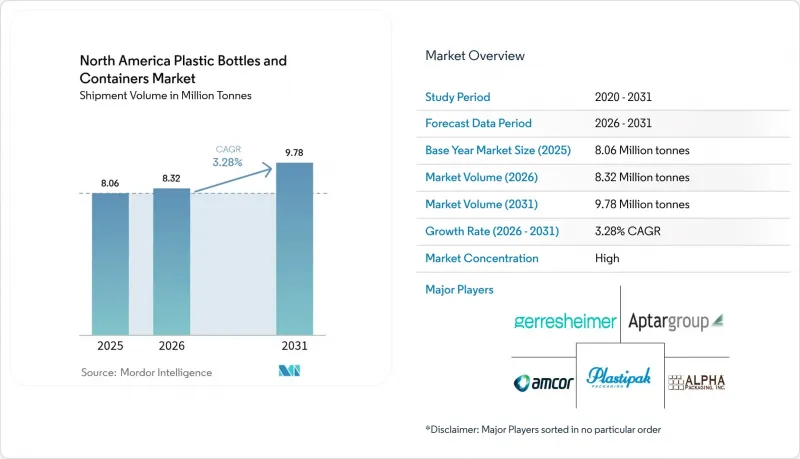
에 의하면, 2026년 북미의 플라스틱 병 및 용기 시장 규모는 832만 톤으로 추정되고 2025년 806만 톤으로부터 확대해, 2031년에는 978만 톤에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 3.28%가 될 것으로 전망됩니다.

본 보고서는 소재별(PET, HDPE, PP, LDPE, 바이오플라스틱, 기타), 포장 유형별(병, 항아리·캐니스터, 제리캔, 기타), 최종 사용자 산업별(음료, 식품, 의약품, 기타),제조 기술별(압출 블로우 성형, 사출 신장 블로우 성형, 기타), 국가별로 분류되어 있습니다. 시장 예측은 수량(톤) 단위로 제시되어 있습니다.
북미의 플라스틱 병 및 용기 시장 동향 및 인사이트
음료 부문에서 경량 포장 채택 확대
음료 제조업체들은 운송 비용 절감과 기후 변화 대응 공약 달성을 위해 경량화를 가속화하고 있으며, 첨단 사출 신장 블로우 성형 기술을 활용하여 차단 성능을 저하시키지 않으면서 병의 무게를 최대 15%까지 줄이는 데 성공했습니다. 코카콜라는 슬림한 포장 형태를 우대하는 부피 중량 기반 운임 제도를 발판으로 삼아, 2024년에 북미 사업 전반에서 플라스틱 사용량을 20% 감축했습니다. 소비자 조사에 따르면, 여전히 휴대성과 편의성이 소재에 대한 우려보다 우선시되고 있으며, 이것이 아웃도어 레크리에이션 부문에서 플라스틱의 채택을 뒷받침하고 있습니다. FDA의 식품 접촉 관련 규정에 따라 각 브랜드는 안전성을 확보하기 위해 벽 두께가 얇은 용기에 대한 검증을 의무화하고 있으며, 이에 따라 수지 공급업체들은 낙하 내구성을 유지하면서 고유 점도가 높은 PET 등급의 상품화를 추진하고 있습니다. 이러한 요인으로 인해 2030년까지 프리미엄 수분 보충 음료, 향이 첨가된 물, 기능성 스포츠 음료 부문에서 판매량이 한 자릿수 중반대의 성장률을 유지할 것으로 전망됩니다.
보증금 반환 제도에 따른 rPET 병 수요 증가
미국에서는 10개 주와 캐나다의 여러 주에서 보증금 반환 제도가 도입되어, 이에 따라 2024년 지역별 PET 재활용률은 41.3%에 달하고, 세계 평균을 크게 상회했습니다. 더 높은 품질의 재활용 펠릿과 폐쇄형 순환 경제를 통해, 컨버터는 식품 등급의 재활용 PET를 대규모로 인증할 수 있게 되었으며, 이는 2035년까지 재활용 소재 함유율을 30-35%로 높이겠다는 각 브랜드의 공약을 뒷받침하고 있습니다. 캘리포니아주에서는 2024년에 180억 개 이상의 음료 용기가 처리되어, 병에서 병으로 재가공용 고품질 rPET의 풍부한 공급원이 마련되었습니다. 펩시코의 재설정된 목표는 안정적인 재생 원료 공급에 의존하고 있으며, 이에 따라 재생 원료에 대한 장기 수지 계약이 확대되고 있습니다. 각 장비 제조업체들은 오염 제거 모듈과 생산 라인에서 펠릿의 투명도를 검증하는 비전 시스템을 통합하여 이에 대응하고 있으며, 북미의 플라스틱 병 및 용기 시장 전반에서 rPET의 채택이 가속화되고 있습니다.
석유계 원료 가격 변동
천연가스에 연동되는 에틸렌 가격은 2024년에 25-30% 변동하여, 분기별 계약에 묶인 수지 구매업체의 이익률을 압박했습니다. 중소 성형업체의 경우, 가격 급등 시 30-90일의 원가 전가 시차가 발생하여 수익성을 잠식하고 있습니다. 멕시코만 연안의 주요 크래커에서 발생한 플랜트 가동 중단은 가격 변동을 더욱 증폭시켜, 가공업체들이 헤지나 막대한 재고 보유를 할 수밖에 없게 만들고 있습니다. 실간(Silgan)사는 2024년, 수지 가격 변동을 상쇄하기 위해 5,000만 달러의 영업 비용을 절감했으나, 이는 공급망에 부과된 간접비 부담이 얼마나 큰지를 여실히 보여줍니다. 가격의 급격한 등락이 지속되면서 북미의 플라스틱 병 및 용기 시장의 단기적인 확장 계획에 큰 부담이 되고 있습니다.
부문별 분석
PET는 2025년 공급량의 51.87%를 차지하며, 비용 대비 뛰어난 차단 성능과 폐쇄형 ‘병에서 병으로(bottle-to-bottle)’ 프로그램을 뒷받침하는 대륙 규모의 회수 네트워크를 통해 선두 자리를 유지했습니다. 고밀도 폴리에틸렌은 내화학성 덕분에 유제품 및 가정용 화학제품 부문에서 확고한 입지를 유지하고 있는 반면, 폴리프로필렌은 내열성이 요구되는 의약품 및 퍼스널케어 제품 부문에서 주도적인 위치를 차지하고 있습니다. 바이오플라스틱은 현재로서는 틈새 시장이지만, 생산 능력 부족에도 불구하고 각 브랜드사가 퇴비화 가능하거나 저탄소 대체재를 추구하는 움직임을 반영하여 연평균 성장률(CAGR) 5.72%가 예상됩니다.
경량화가 진행됨에 따라 컨버터는 PET 병에서 수지 사용량을 15% 줄일 수 있게 되었으며, 이는 브랜드의 공약에 부합하는 운송 비용 및 이산화탄소 배출량 감축으로 이어집니다. 퍼플루오로알킬 물질 및 폴리플루오로알킬 물질에 대한 규제적 관심은 PET에 대해서는 최소한으로 그치고 있어, 이것이 PET 시장 점유율을 더욱 공고히 하고 있습니다. 따라서 프리미엄 화장품이나 특수 식품과 같은 고수익 용도에서 바이오플라스틱이 점차 시장 점유율을 빼앗기 시작하고 있음에도 불구하고, 북미의 PET 플라스틱 병 및 용기 시장 규모는 완만하게 확대될 전망입니다.
병은 2025년 출하량의 47.78%를 차지하며, 음료, 퍼스널케어 제품, 가정용 세제 등에 사용되었습니다. 새로운 기본 형태와 최적화된 목 나사 덕분에 경량화 후에도 강성을 유지할 수 있어 그 우위를 확고히 하고 있습니다. 앰플과 바이알은 정밀한 미량 투여가 필요한 주사제 및 바이오의약품에 힘입어 연평균 성장률(CAGR) 4.63%로 증가할 것으로 예측됩니다.
입자 관리 및 추출물을 중시하는 의약품 지침으로 인해 규정 준수 비용이 급등하고 있으며, 이러한 소형 제형에 대한 부가가치 가격 책정이 정착되고 있습니다. 따라서 주사제 치료 증가에 따라 북미의 앰플용 플라스틱 병 및 용기 시장 규모는 총 출하량을 웃도는 속도로 확대될 전망입니다.
한편, 항아리나 캐니스터 등 다른 유형의 용기는 산소에 민감한 배합을 배리어 라미네이트로 보호하는 고급 화장품 및 식품 보존과 같은 틈새 시장에서 여전히 중요한 위치를 차지하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, North America plastic bottles and containers market size in 2026 is estimated at 8.32 million tonnes, growing from 2025 value of 8.06 million tonnes with 2031 projections showing 9.78 million tonnes, growing at 3.28% CAGR over 2026-2031.
This report is Segmented by Material (PET, HDPE, PP, LDPE, Bioplastics, and More), Packaging Type (Bottles, Jars and Canisters, Jerrycans, and More), End-User Industry (Beverages, Food, Pharmaceuticals, and More), Manufacturing Technology (Extrusion Blow Moulding, Injection Stretch Blow Moulding, and More), and Country. The Market Forecasts are Provided in Terms of Volume (Tonnes).
North America Plastic Bottles And Containers Market Trends and Insights
Rising lightweight-packaging adoption in beverages
Beverage producers intensify lightweighting to cut transport costs and meet climate pledges, achieving up to 15% bottle weight cuts without losing barrier strength through advanced injection stretch blow molding. Coca-Cola cut plastic usage across its North American operations by 20% in 2024, encouraged by dimensional-weight freight charges that reward slimmer pack formats. Consumer research still ranks portability and convenience ahead of material concerns, which sustains plastic adoption in outdoor recreation channels. FDA food-contact rules oblige brands to validate thinner walls for safety, spurring resin suppliers to commercialize higher-intrinsic-viscosity PET grades that maintain drop resistance. The driver will sustain mid-single-digit volume gains in premium hydration, flavored waters, and enhanced sports drinks through 2030.
Deposit-return schemes boosting rPET bottle demand
Ten U.S. states and multiple Canadian provinces operate deposit-return systems that raised regional PET recycling to 41.3% in 2024, well above global averages. Cleaner bales and closed-loop economics let converters certify food-grade recycled PET at scale, feeding brand pledges for 30-35% recycled content by 2035. California processed more than 18 billion beverage containers in 2024, creating a dense supply of high-quality rPET for bottle-to-bottle reprocessing. PepsiCo's reset goals depend on a stable recycled supply, which lifts long-term resin contracts for reclaimed material. Equipment makers are responding by integrating decontamination modules and vision systems that validate pellet clarity in-line, accelerating rPET uptake across the North America plastic bottles and containers market.
Volatile petro-feedstock prices
Natural-gas-linked ethylene costs swung by 25-30% in 2024, pinching margins for resin buyers locked into quarterly contracts. Smaller molders face 30-90-day pass-through lags that erode profitability during spikes. Plant outages at major Gulf Coast crackers amplify volatility, forcing converters to hedge or carry high inventory. Silgan trimmed USD 50 million of operating costs in 2024 to offset resin swings, illustrating the overhead burden placed on the supply base. Continued price turbulence weighs on near-term expansion plans within the North America plastic bottles and containers market.
Other drivers and restraints analyzed in the detailed report include:
- Premiumisation trend in cosmetics and personal-care SKU sizing
- E-commerce demand spike for durable, shippable containers
- Escalating brand-owner sustainability commitments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PET supplied 51.87% of 2025 volume, retaining lead due to cost-effective barrier strength and a continent-wide collection network that supports closed-loop bottle-to-bottle programs. High-density polyethylene remains entrenched in dairy and household chemicals thanks to chemical resistance, whereas polypropylene commands heat-resistant drug and personal-care lines. Bioplastics, though just a niche today, are slated for a 5.72% CAGR, reflecting brand bids for compostable or low-carbon alternatives despite capacity shortages.
Intensified lightweighting lets converters shave 15% resin from PET bottles, translating to freight and carbon gains that sync with brand pledges. Regulatory attention to per- and polyfluoroalkyl substances is minimal for PET, further safeguarding its share. The North America plastic bottles and containers market size for PET will thus edge upwards, even as bioplastics nibble high-margin applications in premium cosmetics and specialty foods.
Bottles controlled 47.78% of 2025 shipments, serving beverages, personal care products, and household cleaners. New base geometries and optimized neck threads help maintain rigidity after weight reduction, locking in its dominance. Ampoules and vials are forecast to climb at 4.63% CAGR, propelled by parenteral drugs and biologics that require precise micro-dosing.
Pharmaceutical guidelines that stress particulate control and extractables run compliance costs high, cementing value-added pricing in these small formats. The North America plastic bottles and containers market size for ampoules will therefore outpace macro volumes as injectable therapies rise.
Other types, such as jars and canisters, remain important in premium beauty and food preservation niches, where barrier laminations guard oxygen-sensitive formulas.
Complete Report Scope:
- By Material
- Polyethylene Terephthalate (PET)
- High-Density Polyethylene (HDPE)
- Polypropylene (PP)
- Low-Density Polyethylene (LDPE)
- Bioplastics
- Other Plastics
- By Packaging Type
- Bottles
- Jars and Canisters
- Jerrycans
- Ampoules and Vials
- Other Packaging Types
- By End-user Industry
- Beverages
- Non-Alcoholic Beverages
- Bottled Water
- Carbonated Soft Drinks
- Dairy and Functional Drinks
- Other Non-Alcoholic Beverages
- Alcoholic Beverages
- Non-Alcoholic Beverages
- Food
- Pharmaceuticals
- Cosmetics and Personal Care
- Industrial Chemicals
- Other End-user Industries
- Beverages
- By Manufacturing Technology
- Extrusion Blow Moulding
- Injection Stretch Blow Moulding
- Injection Blow Moulding
- Compression Blow Moulding
- Other Manufacturing Technologies
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Amcor plc
- Plastipak Holdings Inc.
- Graham Packaging Company LP
- Alpha Packaging Inc.
- Altium Packaging LLC (Loews Corp.)
- Gerresheimer AG
- AptarGroup Inc.
- Comar LLC
- Silgan Holdings Inc.
- Consolidated Container Company LLC
- RPC MandH Plastics Ltd.
- Pretium Packaging LLC
- O.Berk Company LLC
- Inteplast Group Ltd.
- Ring Container Technologies
- Alpla Werke Alwin Lehner GmbH and Co KG
- KP Plastics Inc.
- Sonoco Products Company
- C.L. Smith Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising lightweight-packaging adoption in beverages
- 4.2.2 Premiumisation trend in cosmetics and personal-care SKU sizing
- 4.2.3 E-commerce demand spike for durable, shippable containers
- 4.2.4 Deposit-return schemes boosting rPET bottle demand
- 4.2.5 Craft RTD alcoholic beverages shifting to plastic cans
- 4.3 Market Restraints
- 4.3.1 Volatile petro-feedstock prices
- 4.3.2 Escalating brand-owner sustainability commitments
- 4.3.3 Municipal single-use-plastic bans in key U.S. states (under-reported)
- 4.3.4 Emergence of aluminum bottles in sports drinks (under-reported)
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers/Consumers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitute Products
- 4.4.5 Intensity of Competitive Rivalry
- 4.5 Industry Value Chain Analysis
- 4.6 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Material
- 5.1.1 Polyethylene Terephthalate (PET)
- 5.1.2 High-Density Polyethylene (HDPE)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Low-Density Polyethylene (LDPE)
- 5.1.5 Bioplastics
- 5.1.6 Other Plastics
- 5.2 By Packaging Type
- 5.2.1 Bottles
- 5.2.2 Jars and Canisters
- 5.2.3 Jerrycans
- 5.2.4 Ampoules and Vials
- 5.2.5 Other Packaging Types
- 5.3 By End-user Industry
- 5.3.1 Beverages
- 5.3.1.1 Non-Alcoholic Beverages
- 5.3.1.1.1 Bottled Water
- 5.3.1.1.2 Carbonated Soft Drinks
- 5.3.1.1.3 Dairy and Functional Drinks
- 5.3.1.1.4 Other Non-Alcoholic Beverages
- 5.3.1.2 Alcoholic Beverages
- 5.3.1.1 Non-Alcoholic Beverages
- 5.3.2 Food
- 5.3.3 Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Industrial Chemicals
- 5.3.6 Other End-user Industries
- 5.3.1 Beverages
- 5.4 By Manufacturing Technology
- 5.4.1 Extrusion Blow Moulding
- 5.4.2 Injection Stretch Blow Moulding
- 5.4.3 Injection Blow Moulding
- 5.4.4 Compression Blow Moulding
- 5.4.5 Other Manufacturing Technologies
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Plastipak Holdings Inc.
- 6.4.3 Graham Packaging Company LP
- 6.4.4 Alpha Packaging Inc.
- 6.4.5 Altium Packaging LLC (Loews Corp.)
- 6.4.6 Gerresheimer AG
- 6.4.7 AptarGroup Inc.
- 6.4.8 Comar LLC
- 6.4.9 Silgan Holdings Inc.
- 6.4.10 Consolidated Container Company LLC
- 6.4.11 RPC MandH Plastics Ltd.
- 6.4.12 Pretium Packaging LLC
- 6.4.13 O.Berk Company LLC
- 6.4.14 Inteplast Group Ltd.
- 6.4.15 Ring Container Technologies
- 6.4.16 Alpla Werke Alwin Lehner GmbH and Co KG
- 6.4.17 KP Plastics Inc.
- 6.4.18 Sonoco Products Company
- 6.4.19 C.L. Smith Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


