

|
시장보고서
상품코드
2122271
플라스틱병 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Plastic Bottles - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
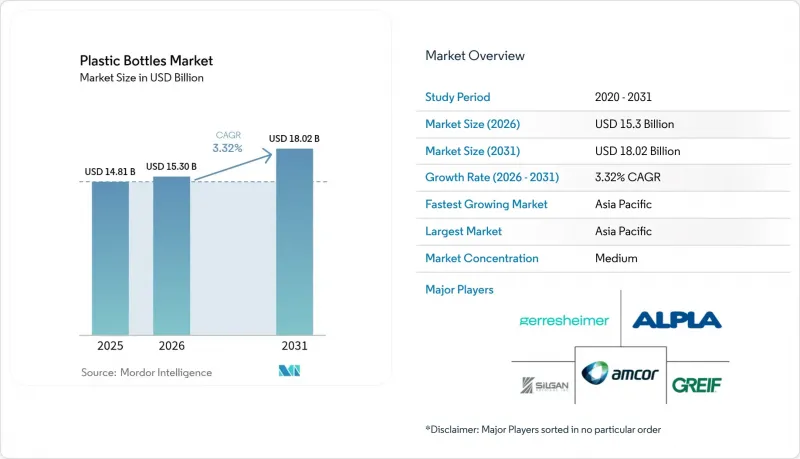
에 의하면, 2026년 플라스틱병 시장 규모는 153억 달러로 추정되고, 2025년 148억 1,000만 달러에서 성장하여 2031년에는 180억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 3.32%로 성장할 것으로 전망됩니다.

본 보고서는 소재별(폴리에틸렌 테레프탈레이트(PET), 고밀도 폴리에틸렌(HDPE) 등), 제조 공정별(압출 블로우 성형, 사출 블로우 성형 등), 용량 범위별(100mL 미만, 100-250mL, 251-500mL, 501-1,000mL, 기타), 최종 사용자 산업별(음료, 식품, 기타) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 플라스틱병 시장 동향 및 인사이트
경량화 및 내충격성이 뛰어난 포장에 대한 수요 증가
무게가 최적화된 PET 병은 기존 제품보다 30% 가벼워졌으면서도 구조적 강도를 유지하고 있어, 브랜드 소유자는 출하 단위당 최대 15%의 운송 비용을 절감할 수 있습니다. 전자상거래의 보급으로 인해 이러한 이점은 더욱 확대되고 있습니다. 이는 1그램이 가벼워질 때마다 장거리 소포 배송 경로에서 부피 중량 요금과 탄소 발자국이 감소하기 때문입니다. 수지 기술의 지속적인 발전으로 상부 하중에 대한 강도를 저하시키지 않으면서 두께를 얇게 만들 수 있게 되어, 고속 충진이 가능해질 뿐만 아니라 대량 유통 시 팔레트 무게를 줄이는 데에도 기여하고 있습니다. PET에 30%의 식물 유래 성분을 배합한 ‘PlantBottle’ 기술은 무게 감량과 재생 가능 원료가 주류 음료 용기에서 어떻게 공존할 수 있는지를 보여주고 있습니다. 이러한 발전들이 결합되어, 물류 집약형 공급망에서 플라스틱병 시장은 유리나 알루미늄에 비해 경쟁력을 유지하고 있습니다.
PET/HDPE의 비용 우위성과 확장성
생산 경제성은 여전히 매력적입니다. PET 및 HDPE 병은 1리터당 비용이 알루미늄 병보다 40-60% 저렴하고, 유리병보다 70-80% 저렴합니다. 2024년 공급망 혼란 당시, 플라스틱 가공업체들은 가마 가동 중단 시간이 짧고 인력 수요가 더 유연했기 때문에 유리 제조업체보다 3배 빠른 속도로 정상 생산량을 회복했습니다. 새로운 고속 사출 성형 시스템 덕분에 생산성이 25% 향상되고 병 1개당 kW시 소비량이 15% 감소하여, 원유 유래 수지 가격이 변동하더라도 운영비 부담을 줄일 수 있습니다. 확장 가능한 라인 전환을 통해 위탁 충전 업체는 계절별 프로모션에 따른 SKU 교체에 신속하게 대응할 수 있으며, 그 결과 소비재 부문 전반에서 플라스틱병 시장의 우위가 더욱 공고해지고 있습니다.
일회용 플라스틱 금지 및 과세
유럽연합(EU)의 지침에 따라 2024년에는 23억 개의 병이 유통에서 제외되었습니다. 한편, 독일에서 도입된 1kg당 0.49달러의 플라스틱세는 규정 준수 비용을 증가시키는 동시에 재생 소재의 채택을 가속화했습니다. 캐나다와 미국의 여러 주에서도 유사한 조치가 마련되면서, 전 세계적인 SKU 관리 및 표시 요건이 복잡해지고 있습니다. 소규모 가공업체들은 생산 라인 개조나 대체 소재로의 다각화에 필요한 자본이 부족하여 불균형한 이익률 압박을 느끼고 있습니다. 단계적인 시행 일정에 따라 단기적인 충격은 완화되고 있지만, 그 누적된 영향으로 인해 플라스틱병 시장 내 판매량 증가세가 억제되고 있습니다.
부문 분석
2025년, PET는 플라스틱병 시장 규모의 74.86%를 차지했으며, 투명성, 강도, 재활용성의 균형 잡힌 성능을 반영하고 있습니다. HDPE는 내화학성이 필요한 가정용품 및 의약품에 사용되며, LDPE는 짜낼 수 있는 용기에, PP는 핫필(고온 충전) 요구에 대응하고 있습니다. PLA나 PHA와 같은 바이오 수지는 가격대가 높지만, 유럽의 재생 가능 원료 함유율 목표에 따라 보급이 확대되고 있습니다. 2026년부터 2031년에 걸쳐 PET는 주도적인 위치를 유지할 것으로 예상되는 반면, 브랜드 소유자들이 틈새 시장용 사례에 대해 퇴비화 가능한 솔루션을 시험적으로 도입함에 따라 바이오 블렌드 소재가 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다.
연구 개발(R&D) 협력도 확대되고 있습니다. Danimer사와 PepsiCo사는 PHA의 상용화를 추진하고 있으며, NatureWorks사는 태국에서의 사업 확장에 따라 PLA 생산량을 연간 15만 톤으로 두 배로 늘렸습니다. 이러한 움직임은 소재 선택의 폭을 넓히고, 배리어 코팅의 혁신을 촉진하며, 플라스틱병 시장 전체의 조달 전략을 재구축하는 결과로 이어질 것입니다.
2025년에는 의약품 및 화장품 분야에서 필수적인 정밀 공차와 표면 마감의 균일성 덕분에 사출 블로우 성형이 플라스틱병 시장의 47.55% 점유율을 차지했습니다. 고투명도 음료병 생산에서는 스트레치 블로우 성형 시스템이 주류를 이루고 있습니다. 한편, 압출 블로우 성형은 생산량 기준으로는 두 번째로 인기 있는 방식에 불과하지만, 금형의 유연성과 재생 재료에 대한 대응 능력 덕분에 2031년까지 연평균 성장률(CAGR) 4.45%를 나타낼 것으로 예측됩니다.
인더스트리 4.0에 따른 업그레이드로 인해 압출 라인에 비전 시스템과 예측 유지보수가 도입되어 가동 중단 시간과 불량품을 최소화하고 있습니다. 압출 성형과 사출 성형이 모두 가능한 하이브리드 기계는 제품 개발 주기의 단축을 촉진하며, 플라스틱병 시장에서 사설 브랜드 소매업체들이 요구하는 유연한 SKU 갱신을 뒷받침하고 있습니다.
지역별 분석
아시아태평양은 2025년 플라스틱병 시장에서 45.92%의 시장 점유율을 차지했으며, 2031년까지 연평균 성장률(CAGR) 4.36%를 나타낼 것으로 예측됩니다. 이 지역의 생산량의 절반 이상을 차지하는 중국은 통합된 PET 수지 공급 체계와 비용 경쟁력 있는 노동력을 활용하여 국내 및 수출 수요 모두를 충족시키고 있습니다. 인도에서는 전자상거래의 급속한 확산과 식품 포장에 관한 규제 강화가 맞물려 수량 기준으로 두 자릿수 성장을 이끌고 있습니다. 한편, 인도네시아, 말레이시아, 태국은 다국적 브랜드 소유주를 위한 위탁 생산 거점으로 부상하고 있습니다. 이 지역 각국에서는 사용 후 제품 회수를 촉진하는 보증금 반환 제도가 도입되어 있지만, 회수율은 여전히 유럽 수준에는 미치지 못하고 있습니다.
북미는 성숙한 시장이지만, 혁신의 깊이 측면에서는 그다지 높지 않습니다. 미국에서는 첨단 화학 재활용 실증 실험이 진행되고 있으며, 브랜드 주도의 사용 후 수지 회수 계약을 통해 rPET 원료 확보가 추진되고 있습니다. 캐나다 연방 정부의 일회용 플라스틱 금지 조치는 기판 및 디자인 전환을 가속화하고 있으며, 멕시코는 국내 및 수출 지향형 충전 공장에 모두 서비스를 제공하는 비용 경쟁력 있는 가공 능력을 활용하고 있습니다. 지속가능성 표시 및 캘리포니아주의 2024년 재활용 소재 함유율 최저 기준법은 공급망의 투명성을 의무화하여 플라스틱병 시장 전반에서 재생 수지의 가격을 상승시키고 있습니다.
유럽은 여전히 규제 주도형입니다. 독일의 보증금 제도를 통해 PET의 90% 이상이 회수되고 있으며, 캡 고정화 규제가 금형 및 하드웨어 업그레이드를 촉진하고 있습니다. 프랑스는 PCR(소비 후 재활용 플라스틱) 의무화를 강화하고 있는 반면, 이탈리아는 생분해성 제품에 주력하고 있습니다. 영국은 브렉시트 이후, 병행하면서도 서로 다른 EPR(생산자 책임 확대) 요금 제도를 확립하여 지역별 설계 개선을 촉진하고 있습니다. 중동유럽에서는 가공업체들이 에너지비 및 인건비 절감을 추구하는 가운데, 생산 능력에 대한 투자가 진행되고 있습니다. 그 밖의 지역에서는 남미에서 포장 제품 시장 침투가 진행되고 있으며, 중동 및 아프리카 시장에서는 도시화와 콜드체인 인프라 구축이 진전됨에 따라 장기적인 전망이 확고해지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, plastic bottles market size in 2026 is estimated at USD 15.3 billion, growing from 2025 value of USD 14.81 billion with 2031 projections showing USD 18.02 billion, growing at 3.32% CAGR over 2026-2031.
This report is Segmented by Material (Polyethylene Terephthalate (PET), High-Density Polyethylene (HDPE), and More), Manufacturing Process (Extrusion Blow Molding, Injection Blow Molding, and More), Capacity Range (Less Than 100 ML, 100 - 250 ML, 251 - 500 ML, 501 - 1, 000 ML, and More), End-User Vertical (Beverages, Food, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Plastic Bottles Market Trends and Insights
Rising Demand for Lightweight, Shatter-Resistant Packaging
Weight-optimized PET bottles now come in 30% lighter than earlier versions yet maintain structural integrity, letting brand owners cut transport costs by as much as 15% per unit shipped. E-commerce amplifies the benefit because each gram saved lowers dimensional-weight charges and carbon footprints over long, parcel-based distribution routes. Continuous resin engineering enables thinner wall sections without compromising top-load strength, allowing for high-speed filling and reducing pallet weight in bulk channels. PlantBottle technology, which blends PET with 30% plant-derived content, illustrates how weight reduction and renewable feedstocks can coexist for mainstream beverage formats. Collectively, these advances keep the plastic bottles market competitive against glass and aluminum in logistics-intensive supply chains.
Cost Advantage and Scalability of PET/HDPE
Production economics remain compelling: PET and HDPE bottles cost 40-60% less per liter of capacity than aluminum and 70-80% less than glass. During the 2024 supply-chain disruptions, plastic converters restored normal output 3 times faster than glass producers, thanks to shorter furnace downtime and more flexible labor needs. New high-speed injection systems deliver 25% productivity gains and 15% lower kilowatt-hour consumption per bottle, easing operating-expense pressure even when crude-derived resin prices fluctuate. Scalable line changeovers allow contract packers to adjust quickly to SKU rotations tied to seasonal promotions, thereby reinforcing the dominance of the plastic bottles market across mass-volume consumer categories.
Single-Use-Plastic Bans and Taxes
The European Union's directive removed 2.3 billion bottles from circulation in 2024, while Germany's 0.49 USD per kg plastic tax increased compliance costs and accelerated the adoption of recycled content. Canada and multiple U.S. states drafted comparable measures, complicating global SKU management and labeling requirements. Smaller converters feel disproportionate margin pressure because they lack the capital to retrofit lines or diversify into alternative substrates. Although phased timelines soften the short-term shock, the cumulative impact clips volume growth inside the plastic bottles market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in E-Commerce Logistics
- Brand Circularity Push for rPET
- Shift to Aluminum and Paper Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PET accounted for 74.86% of the plastic bottles market size in 2025, reflecting its performance balance of clarity, strength, and recyclability. HDPE is used for chemical-resistant household and pharma products, while LDPE serves squeezable formats and PP supports hot-fill needs. Bio-based resins such as PLA and PHA command premium pricing but gain traction under Europe's renewable-content targets. Between 2026 and 2031, PET is projected to retain its leadership position, while bio-based blends are expected to log the highest CAGR, as brand owners pilot compostable solutions for niche use cases.
R&D collaborations proliferate: Danimer and PepsiCo advance PHA commercialization, and NatureWorks doubles PLA output to 150,000 tpa in its Thailand expansion. These moves expand material options, stimulate barrier-coating innovation, and reshape procurement strategies across the plastic bottles market.
Injection blow molding captured 47.55 of % plastic bottles market share in 2025, owing to precision tolerance and surface-finish uniformity critical for pharma and cosmetics lines. Stretch-blow systems dominate the production of high-clarity beverage bottles, while extrusion blow molding, although only the second most popular by volume, is projected to grow at a 4.45% CAGR to 2031 due to its tooling flexibility and tolerance for recycled materials.
Industry 4.0 upgrades layer vision systems and predictive maintenance onto extrusion lines, minimizing downtime and scrap. Hybrid machines capable of both extrusion and injection operations facilitate shorter product-development cycles, supporting the agile SKU refreshes demanded by private-label retailers in the plastic bottles market.
Complete Report Scope:
- By Material
- Polyethylene Terephthalate (PET)
- High-density Polyethylene (HDPE)
- Low-density Polyethylene (LDPE)
- Polypropylene (PP)
- Bio-based and Compostable Plastics
- Other Materials
- By Manufacturing Process
- Extrusion Blow Molding
- Injection Blow Molding
- Stretch Blow Molding
- Other Manufacturing Processes
- By Capacity Range
- Less than 100 mL
- 100 - 250 mL
- 251 - 500 mL
- 501 - 1,000 mL
- More than 1,000 mL
- By End-user Vertical
- Beverages
- Food
- Cosmetics and Personal Care
- Pharmaceuticals
- Household Care
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia
- Malaysia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
The Asia Pacific held a 45.92% market share of the plastic bottles market in 2025 and is projected to grow at a 4.36% CAGR through 2031. China, accounting for more than half of the regional volume, leverages an integrated PET resin supply and cost-competitive labor to meet both domestic and export demand. India's rapid adoption of e-commerce, combined with stricter food packaging laws, fuels double-digit unit growth, while Indonesia, Malaysia, and Thailand emerge as contract manufacturing nodes for multinational brand owners. Nations across the region are rolling out deposit-return schemes that stimulate post-consumer collection, yet they still lag behind European recovery rates.
North America displays maturity, but not as much innovation depth. The United States hosts advanced chemical recycling pilots and brand-led post-consumer resin offtake contracts that secure rPET feedstock. Canada's federal single-use plastic ban accelerates substrate and design shifts, and Mexico leverages cost-advantaged conversion capacity that serves both domestic and export-oriented filling plants. Sustainability labeling and California's 2024 minimum-recycled-content law compel supply-chain transparency and elevate recycled-resin pricing across the plastic bottles market.
Europe remains regulation-driven. Germany's deposit system recovers more than 90% of PET, and tethered-cap rules drive mold and hardware upgrades. France intensifies PCR mandates, while Italy focuses on biodegradable products. The United Kingdom, post-Brexit, establishes parallel but divergent EPR fees that spur localized design tweaks. Central and Eastern Europe see capacity investment as converters chase lower utilities and labor expenses. Elsewhere, South America expands its penetration of packaged goods, while the Middle East and Africa markets anchor long-term prospects as urbanization and cold-chain infrastructure mature.
- Amcor plc
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Graham Packaging Company
- Silgan Holdings Inc.
- Gerresheimer AG
- Greiner Packaging International GmbH
- Resilux NV
- Altium Packaging LLC
- Retal Industries Ltd.
- Nampak Ltd.
- Comar LLC
- Alpha Packaging Pvt. Ltd.
- Plastipak Holdings Inc.
- Pretium Packaging LLC
- CoastPak Industrial Co. Ltd.
- Grief, Inc.
- O.Berk Company, LLC
- Richards Glass Co. Ltd.
- Triumbari Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for lightweight, shatter-resistant packaging
- 4.2.2 Cost advantage and scalability of PET/HDPE
- 4.2.3 Surge in e-commerce logistics
- 4.2.4 Brand circularity push for rPET
- 4.2.5 EU tethered-cap regulation-driven volumes
- 4.2.6 Aseptic cold-fill for dairy-alternatives
- 4.3 Market Restraints
- 4.3.1 Single-use-plastic bans and taxes
- 4.3.2 Shift to aluminum and paper alternatives
- 4.3.3 Volatile PCR resin supply
- 4.3.4 Lightweight glass tech eroding weight edge
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Polyethylene Terephthalate (PET)
- 5.1.2 High-density Polyethylene (HDPE)
- 5.1.3 Low-density Polyethylene (LDPE)
- 5.1.4 Polypropylene (PP)
- 5.1.5 Bio-based and Compostable Plastics
- 5.1.6 Other Materials
- 5.2 By Manufacturing Process
- 5.2.1 Extrusion Blow Molding
- 5.2.2 Injection Blow Molding
- 5.2.3 Stretch Blow Molding
- 5.2.4 Other Manufacturing Processes
- 5.3 By Capacity Range
- 5.3.1 Less than 100 mL
- 5.3.2 100 - 250 mL
- 5.3.3 251 - 500 mL
- 5.3.4 501 - 1,000 mL
- 5.3.5 More than 1,000 mL
- 5.4 By End-user Vertical
- 5.4.1 Beverages
- 5.4.2 Food
- 5.4.3 Cosmetics and Personal Care
- 5.4.4 Pharmaceuticals
- 5.4.5 Household Care
- 5.4.6 Other End-user Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Malaysia
- 5.5.4.7 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 ALPLA Werke Alwin Lehner GmbH & Co KG
- 6.4.3 Graham Packaging Company
- 6.4.4 Silgan Holdings Inc.
- 6.4.5 Gerresheimer AG
- 6.4.6 Greiner Packaging International GmbH
- 6.4.7 Resilux NV
- 6.4.8 Altium Packaging LLC
- 6.4.9 Retal Industries Ltd.
- 6.4.10 Nampak Ltd.
- 6.4.11 Comar LLC
- 6.4.12 Alpha Packaging Pvt. Ltd.
- 6.4.13 Plastipak Holdings Inc.
- 6.4.14 Pretium Packaging LLC
- 6.4.15 CoastPak Industrial Co. Ltd.
- 6.4.16 Grief, Inc.
- 6.4.17 O.Berk Company, LLC
- 6.4.18 Richards Glass Co. Ltd.
- 6.4.19 Triumbari Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


