

|
시장보고서
상품코드
2121971
유럽의 플라스틱병 및 용기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Plastic Bottles And Containers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
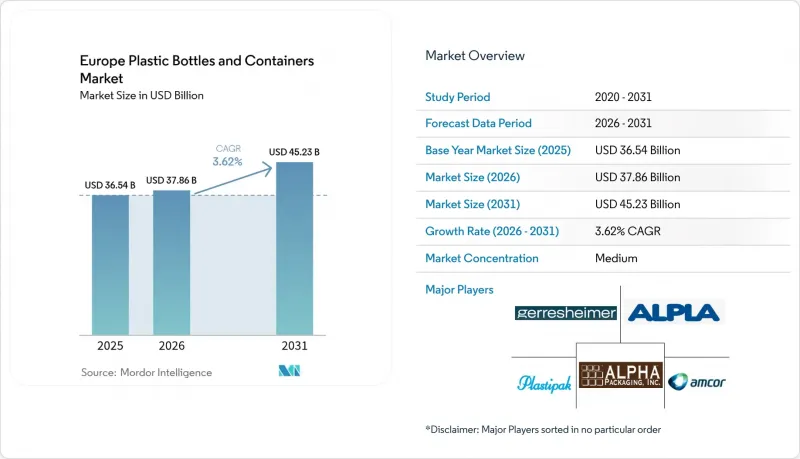
에 따르면 유럽의 플라스틱병 및 용기 시장 규모는 2025년 365억 4,000만 달러에서 2026년에는 378억 6,000만 달러로 확대하며, 2026-2031년에 CAGR 3.62%로 추이하며, 2031년에는 452억 3,000만 달러에 달할 것으로 예측됩니다.

이 보고서는 소재별(PET, HDPE, PP, LDPE 등), 포장 형태별(병, 자(Jar) 및 캐니스터, 제리캔 등), 최종사용자 산업별(음료, 식품 등),제조 기술(압출 블로우 성형, 사출 신장 블로우 성형 등) 및 지역(영국, 독일 등)별로 분류되어 있습니다. 시장 예측은 금액() 기준으로 제시되어 있습니다.
유럽 플라스틱병 및 용기 시장의 동향과 인사이트
생수 및 휴대용 음료 수요 증가
남유럽의 관광 산업 회복과 건강에 대한 의식의 향상가 맞물려 1인당 생수 및 기능성 음료 소비량이 증가하고 있습니다. 각 브랜드 소유 기업은 탄산 및 풍미를 유지하는 차단 성능을 강화한 PET와 경량 캡을 도입하여 이에 대응하고 있습니다. 네슬레는 상부 하중에 대한 강도를 유지하면서 수지 사용량을 줄임으로써, 판매량 확대와 지속가능성 목표를 동시에 달성할 수 있음을 보여주었습니다. 스포츠 영양 브랜드 역시 운동 중 한 손으로 사용할 수 있는 인체공학적인 병 형태로 전환하고 있으며, 이를 통해 1팩당 부가가치가 높아지고 있습니다. 프리미엄 워터가 재생 PET로 전환되는 가운데, 식품 등급 r-PET 생산 라인을 보유한 가공업체들은 수익성 측면에서 우위를 점하고 있으며, 이는 유럽의 플라스틱병 및 용기 시장 전반에 걸쳐 소재 순환에 대한 투자를 촉진하고 있습니다.
E-Commerce가 내구성과 누수 방지 성능이 뛰어난 포장을 촉진
소포의 증가는 경질 용기의 성능 기준을 재정의하고 있습니다. InPost사가 6억 유로를 투자해 전개하는 공용 보관함의 도입은 컨베이어에서의 충격과 온도 변화를 견딜 수 있는 형태의 포장에 대한 수요를 창출하고 있습니다. 미용·퍼스널 케어 업계 기업은 현재 소비자에게 직접 배송되는 상품에 대해 낙하 테스트를 통과한 어린이 안전 캡(어린이가 열기 어려운 캡)을 지정하고 있습니다. 구독 모델은 내구성과 소재 최소화를 동시에 달성한 리필 가능한 병 구조를 촉진하고 있습니다. 자동화된 주문 처리에서는 치수의 표준화가 요구되며, 이에 따라 각 컨버터 업체들은 SKU 간 목 부분 마감 처리를 통일하고 있습니다. 이러한 수요로 인해 유럽의 플라스틱병 및 용기 시장은 더 높은 사양으로, E-Commerce에 최적화된 디자인으로 전환되고 있습니다.
격화되는 일회용 플라스틱 규제
‘일회용 플라스틱 지침’이 회원국들의 국내법에 반영됨에 따라 설계에 대한 급격한 재검토가 진행되고 있습니다. 폴란드에서는 2025년까지 r-PET 함유율을 25%로 해야 한다는 요건이 마련되었으며, 위반시 최대 50만 즈워티의 벌금이 부과되므로 각 컨버터 기업은 공급망 인증을 서두르고 있습니다. 2024년 7월부터 시행되는 캡 일체형 규정에 따라 목 마감부 재설계 및 새로운 힌지용 금형 도입이 의무화되었습니다. 재활용 가능성 점수에 연동된 확대 생산자 책임(EPR) 수수료는 SKU의 수익성에 변화를 주며, 폐쇄형 루프 시스템을 도입한 기업에 유리하게 작용합니다. PFAS의 단계적 폐지를 위해서는 새로운 차단 기술이 필요하며, 유럽의 플라스틱병 및 용기 시장 전반에서 연구개발비가 증가하고 있습니다.
부문 분석
PET는 투명성, 기체 차단 성능, 그리고 확립된 병-대-병(bottle-to-bottle) 회수 루프 덕분에 2025년 유럽 플라스틱병 및 용기 시장에서 51.04%의 점유율을 차지했습니다. 각 브랜드 소유 기업은 위험을 줄이면서 규정을 준수하는 PCR(소비 후 재활용) 소재의 배합을 가능하게 하기 위해 음료 및 경구용 의약품에 식품 등급의 r-PET를 계속해서 지정하고 있습니다. 고밀도 폴리에틸렌(HDPE)은 내화학성을 중시하는 농약 및 퍼스널 케어 분야를 지원하고 있는 반면, 폴리프로필렌(PP)은 핫필용 소스나 멸균 처리된 의약품 접촉 용도로 사용되고 있습니다. 저밀도 폴리에틸렌(LDPE)은 유연하고 짜내기 쉬운 특성으로 인해 화장품 튜브라는 틈새 시장을 개발하고 있지만, 재활용률이 낮아 보급 범위가 제한되고 있습니다.
바이오플라스틱은 유럽의 플라스틱병 및 용기 시장에서 한 자릿수 점유율에 머물러 있지만, 2031년까지 연평균 성장률(CAGR) 4.78%로 확대되고 있습니다. 그라이너 패키징(Greiner Packaging) 등의 제조업체는 공급망과의 호환성을 해치지 않으면서 탄소발자국을 줄일 수 있을 것으로 기대되는 바이오 기반 PET의 시험을 시작했습니다. 생산 능력 증대가 여전히 미미한 탓에 가격은 석유 유래 수지보다 높은 수준을 유지하고 있습니다. 그럼에도 불구하고 고급 화장품 및 기능성 음료 브랜드들은 환경적 리더십을 보여주기 위해 이 높은 가격을 수용하고 있으며, 이에 따라 유럽의 플라스틱병 및 용기 업계는 주류 생산 공정에 바이오소재를 배합한 제품의 양산을 점차 도입하기 시작하고 있습니다.
2025년, 병은 유럽 플라스틱병 및 용기 시장 규모의 48.26%를 차지하며, 250밀리리터 생수 용기부터 5리터 식용유 팩에 이르기까지 모든 제품을 아우르고 있습니다. 형상의 표준화를 통해 컨버터는 목 마감 처리를 신속하게 전환할 수 있으며, 비용 효율적인 생산 전환이 가능해졌습니다. 두께 최적화 및 테더가 부착된 캡의 도입을 통해 병은 PPWR의 기준치를 충족하며 그 우위를 강화하고 있습니다. 자(Jar), 캐니스터, 제리캔은 점도가 높은 식품, 분말, 산업용 액체에 사용되며, 넓은 입구와 손잡이가 일체형으로 설계된 점이 장점으로 작용하여 시장 점유율이 안정적입니다.
앰플과 바이알은 유럽내 바이오의약품 파이프라인 확대 및 무균 충진에 대한 투자 열풍에 힘입어 연평균 성장률(CAGR) 4.63%로 가장 빠르게 성장하고 있는 포장 유형입니다. SCHOTT Pharma의 스냅온 바이알 플랫폼은 캡과의 호환성을 단순화하여 비강용 백신 생산 라인의 설정 시간을 단축합니다. 위조 방지 기능과 데이터 매트릭스를 통한 일련번호 부여로 인해 이러한 소형 용기는 정밀한 사출 블로우 성형이 필요한 고부가가치 제품으로 변모하고 있습니다. 이러한 추세는 높은 수익률을 추구하는 전문 컨버터를 끌어들이며, 유럽의 플라스틱병 및 용기 시장에서 혁신의 흐름을 지원하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.03According to Mordor Intelligence, the Europe plastic bottles and containers market size is expected to grow from USD 36.54 billion in 2025 to USD 37.86 billion in 2026 and is forecast to reach USD 45.23 billion by 2031 at 3.62% CAGR over 2026-2031.
This report is Segmented by Material (PET, HDPE, PP, LDPE, and More), Packaging Type (Bottles, Jars and Canisters, Jerrycans, and More), End-User Industry (Beverages, Food, and More), Manufacturing Technology (Extrusion Blow Moulding, Injection Stretch Blow Moulding, and More), and Geography (UK, Germany, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Plastic Bottles And Containers Market Trends and Insights
Rising Demand for Bottled Water and On-the-Go Beverages
Southern Europe's tourism rebound, combined with heightened health awareness, is lifting per-capita bottled-water and functional-drink consumption. Brand owners are responding with barrier-enhanced PET and lightweight closures that preserve carbonation and taste. Nestle reduced resin use while keeping top-load strength intact, showing that volume growth can coexist with sustainability targets. Sports-nutrition brands are also shifting to ergonomic bottle profiles that support single-hand use during activity, elevating value per pack. As premium waters migrate to recycled-PET, converters with food-grade r-PET lines gain a margin edge, reinforcing material-loop investments across the Europe plastic bottles and containers market.
E-commerce Boosting Durable Leak-proof Packs
Parcel growth is redefining performance thresholds for rigid containers. InPost's EUR 600 million out-of-home locker rollout triggers packaging demand for formats that can withstand conveyor impacts and temperature swings. Beauty and personal-care players now specify drop-tested, child-resistant closures for direct-to-consumer shipments. Subscription models stimulate refill-ready bottle architectures that balance durability with material minimization. Automated fulfillment favors dimensional standardization, prompting converters to harmonize neck finishes across SKUs. These needs reinforce the pivot of the Europe plastic bottles and containers market toward higher-specification, e-commerce-optimized designs.
Escalating Anti-Single-Use-Plastic Regulations
Member-state transposition of the Single-Use Plastics Directive drives rapid design overhauls. Poland set 25% r-PET requirements by 2025 with fines up to PLN 500,000 for non-compliance, pushing converters to certify supply chains quickly. Attached-cap rules effective July 2024 force neck-finish redesigns and new hinge tooling. Extended Producer Responsibility fees, indexed to recyclability scores, alter SKU profitability and favor companies with closed-loop systems. PFAS phase-outs require fresh barrier technologies, lifting R&D spend across the Europe plastic bottles and containers market.
Other drivers and restraints analyzed in the detailed report include:
- Lightweighting Initiatives to Cut Logistics Cost
- Brand Shift to Mono-material Packs for Easier Recycling
- Feedstock Volatility Inflating Virgin-Resin Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PET captured 51.04% of the Europe plastic bottles and containers market share in 2025 thanks to clarity, gas-barrier performance, and established bottle-to-bottle collection loops. Brand owners continue to specify food-grade r-PET for beverages and oral pharmaceuticals as it enables compliant PCR incorporation at lower risk. High-Density Polyethylene supports agrochemical and personal-care streams that prioritize chemical resistance, while Polypropylene serves hot-fill sauces and sterilized drug-contact formats. Low-Density Polyethylene's flexible-squeeze properties carve a niche in cosmetic tubes, although low recycling rates restrain its scope.
Bioplastics, while only a single-digit slice of the Europe plastic bottles and containers market, are expanding at a 4.78% CAGR through 2031. Producers such as Greiner Packaging have initiated bio-based PET trials that promise carbon-footprint cuts without compromising supply-chain compatibility. Capacity additions remain modest, keeping price points above petroleum-based resins. Nevertheless, premium cosmetics and functional-beverage lines accept the premium to signal environmental leadership, ensuring that the Europe plastic bottles and containers industry begins accommodating blended bio-content volumes in mainstream production flows.
Bottles commanded 48.26% of the Europe plastic bottles and containers market size in 2025, covering everything from 250 milliliter water units to five-liter edible-oil packs. Format standardization allows converters to switch between neck finishes rapidly, supporting cost-effective changeovers. Wall-thickness optimizations and tethered-cap rollouts align bottles with PPWR thresholds, reinforcing their primacy. Jars, canisters, and jerrycans serve viscous foods, powders, and industrial fluids that benefit from wide-mouth or handle-integrated designs, keeping their shares stable.
Ampoules and vials are the fastest-growing packaging type at 4.63% CAGR, riding Europe's biologics pipeline and aseptic-fill investment wave. SCHOTT Pharma's snap-on vial platform simplifies closure compatibility, cutting line-setup time for nasal vaccines. Tamper-evidence and data-matrix serialization turn these tiny containers into high-value units demanding precise injection blow molding. This dynamic attracts specialist converters seeking premium margins, sustaining innovation flow in the Europe plastic bottles and containers market.
Complete Report Scope:
- By Material
- Polyethylene Terephthalate (PET)
- High-Density Polyethylene (HDPE)
- Polypropylene (PP)
- Low-Density Polyethylene (LDPE)
- Bioplastics
- Other Plastics
- By Packaging Type
- Bottles
- Jars and Canisters
- Jerrycans
- Ampoules and Vials
- Other Packaging Types
- By End-user Industry
- Beverages
- Non-Alcoholic Beverages
- Bottled Water
- Carbonated Soft Drinks
- Dairy and Functional Drinks
- Other Non-Alcoholic Beverages
- Alcoholic Beverages
- Non-Alcoholic Beverages
- Food
- Pharmaceuticals
- Cosmetics and Personal Care
- Industrial Chemicals
- Other End-user Industries
- Beverages
- By Manufacturing Technology
- Extrusion Blow Moulding
- Injection Stretch Blow Moulding
- Injection Blow Moulding
- Compression Blow Moulding
- Other Manufacturing Technologies
- By Country
- United Kingdom
- Germany
- Italy
- France
- Spain
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Amcor plc
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Gerresheimer AG
- Plastipak Holdings, Inc.
- Alpha Packaging, Inc.
- Graham Packaging Company, L.P.
- Resilux NV
- Greiner Packaging International GmbH
- Comar, LLC
- PACCOR Packaging GmbH
- RETAL Industries Ltd.
- Logoplaste Consultores Tecnicos S.A.
- Serioplast S.p.A.
- Esterform Packaging Limited
- Faerch A/S
- Pont Europe NV
- ALPA S.p.A.
- PTM Packaging Solutions S.r.l.
- Pack Group (Groupe Plastivaloire)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for bottled water and on-the-go beverages
- 4.2.2 E-commerce boosting durable leak-proof packs
- 4.2.3 Lightweighting initiatives to cut logistics cost
- 4.2.4 Brand shift to mono-material packs for easier recycling
- 4.2.5 Surge in chemical-recycling off-take contracts for food-grade PCR
- 4.2.6 Early adoption of digital watermarking enabling high-speed sorting
- 4.3 Market Restraints
- 4.3.1 Escalating anti-single-use-plastic regulations
- 4.3.2 Feed-stock volatility inflating virgin-resin prices
- 4.3.3 Mandatory recycled-content targets inflating compliance cost
- 4.3.4 Retailer refill-station pilots cannibalising single-use volumes
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Polyethylene Terephthalate (PET)
- 5.1.2 High-Density Polyethylene (HDPE)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Low-Density Polyethylene (LDPE)
- 5.1.5 Bioplastics
- 5.1.6 Other Plastics
- 5.2 By Packaging Type
- 5.2.1 Bottles
- 5.2.2 Jars and Canisters
- 5.2.3 Jerrycans
- 5.2.4 Ampoules and Vials
- 5.2.5 Other Packaging Types
- 5.3 By End-user Industry
- 5.3.1 Beverages
- 5.3.1.1 Non-Alcoholic Beverages
- 5.3.1.1.1 Bottled Water
- 5.3.1.1.2 Carbonated Soft Drinks
- 5.3.1.1.3 Dairy and Functional Drinks
- 5.3.1.1.4 Other Non-Alcoholic Beverages
- 5.3.1.2 Alcoholic Beverages
- 5.3.1.1 Non-Alcoholic Beverages
- 5.3.2 Food
- 5.3.3 Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Industrial Chemicals
- 5.3.6 Other End-user Industries
- 5.3.1 Beverages
- 5.4 By Manufacturing Technology
- 5.4.1 Extrusion Blow Moulding
- 5.4.2 Injection Stretch Blow Moulding
- 5.4.3 Injection Blow Moulding
- 5.4.4 Compression Blow Moulding
- 5.4.5 Other Manufacturing Technologies
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 Italy
- 5.5.4 France
- 5.5.5 Spain
- 5.5.6 Poland
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (INCLUDES GLOBAL OVERVIEW, MARKET-LEVEL OVERVIEW, CORE SEGMENTS, FINANCIALS AS AVAILABLE, STRATEGIC INFORMATION, MARKET RANK/SHARE, PRODUCTS and SERVICES, RECENT DEVELOPMENTS)
- 6.4.1 Amcor plc
- 6.4.2 ALPLA Werke Alwin Lehner GmbH & Co KG
- 6.4.3 Gerresheimer AG
- 6.4.4 Plastipak Holdings, Inc.
- 6.4.5 Alpha Packaging, Inc.
- 6.4.6 Graham Packaging Company, L.P.
- 6.4.7 Resilux NV
- 6.4.8 Greiner Packaging International GmbH
- 6.4.9 Comar, LLC
- 6.4.10 PACCOR Packaging GmbH
- 6.4.11 RETAL Industries Ltd.
- 6.4.12 Logoplaste Consultores Tecnicos S.A.
- 6.4.13 Serioplast S.p.A.
- 6.4.14 Esterform Packaging Limited
- 6.4.15 Faerch A/S
- 6.4.16 Pont Europe NV
- 6.4.17 ALPA S.p.A.
- 6.4.18 PTM Packaging Solutions S.r.l.
- 6.4.19 Pack Group (Groupe Plastivaloire)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


