

|
시장보고서
상품코드
2120582
미국의 풍력에너지 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Wind Energy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
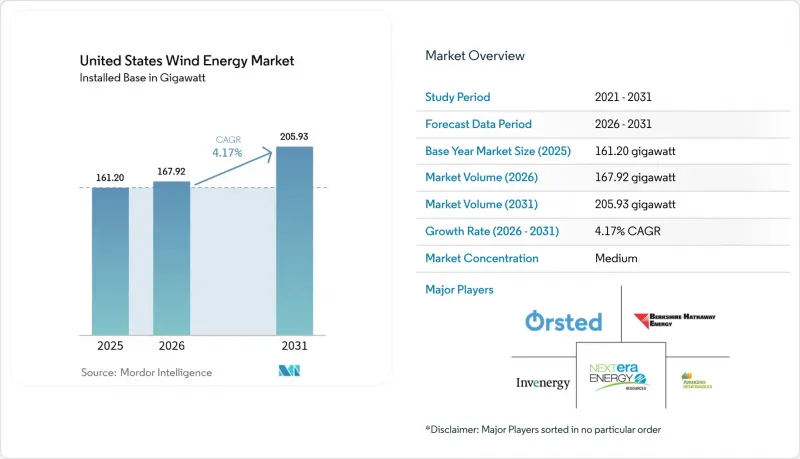
에 의하면, 미국의 풍력에너지 시장 규모는 2025년에 161.20기가와트라고 평가되었습니다. 2026년 167.92기가와트에서 2031년까지 205.93기가와트에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 4.17%를 나타낼 전망입니다.
본 보고서는 입지(육상 및 해상), 터빈 출력(3MW 미만, 3-6MW, 6MW 이상), 용도(유틸리티 규모, 상업 및 산업용, 커뮤니티 프로젝트)별로 분류되어 있습니다. 시장 규모 및 전망은 설치 용량(GW) 단위로 표시되어 있습니다.
미국의 풍력에너지 시장 동향 및 인사이트
IRA 세액 공제 및 PTC 연장
IRA에 따른 2032년까지 10년간의 생산 세액 공제 연장에 더해, 10퍼센트포인트의 국내 조달률 가산이 적용됨에 따라 세후 프로젝트 수익률은 6.5%에서 8.2%로 상승했습니다. 이 법안이 통과된 후, 2024년에는 18GW의 신규 발전 용량에 대한 발표가 있었으며, 이들이 개발 파이프라인에 포함되었습니다. 이 법안은 2025년까지 철강의 40%, 제조 부품의 55%를 국내산으로할 것을 의무화하고 있어, 이로 인해 아이오와주와 콜로라도주의 공장으로의 수주가 촉진되고 있습니다. 2024년 하반기에 실시된 국세청(IRS) 감사에서는 외국산 베어링 사용을 이유로 1.2 GW 규모의 프로젝트가 적용 대상에서 제외되어, 추적성의 미비점이 드러났습니다. ERCOT 지역의 개발 사업자들은 현재 변동이 심한 베이시스 리스크로 인해 장기 전력 구매 계약(PPA) 체결이 어려운 상황에서 가치를 조기에 현금화하기 위해 IRA(인플레이션 억제법)에 따른 30%의 투자 세액 공제를 선택하고 있습니다.
터빈 높이 증가에 따른 LCOE 하락
국립재생에너지연구소(NREL)의 데이터에 따르면, 로터 직경이 170m, 허브 높이가 110m에 달함에 따라 2024년 육상 풍력 발전의 LCOE는 1MWh당 26달러까지 낮아졌습니다. GE Vernova 및 Vestas의 6MW를 초과하는 플랫폼은 과거 풍력 발전이 수익성이 없었던 아칸소주와 테네시주의 클래스 4 부지에서 52%의 설비 가동률을 달성하고 있습니다. 열가소성 복합재로 제작된 블레이드 덕분에 무게가 12% 감소하여 터빈 1기당 BOS(Balance of System) 비용이 8만 달러 절감되었습니다. 이러한 비용 절감으로 인해 2024년에는 8기가와트 규모의 가스 화력 발전소가 조기 폐쇄되게 되었으며, 이는 미국의 풍력 발전 시장에 있어 매우 중요한 전환점이 되었습니다.
송전 및 계통 연계의 병목 현상
2024년 12월, 지역별 송전 대기 용량은 2,600기가와트에 달하며, 그중 풍력 발전이 950기가와트를 차지했고, 평균 심사 기간은 5.2년에 이르렀습니다. MISO만 해도 180기가와트가 대기 중이며, 480억 달러 규모의 송전망 업그레이드가 필요한 상황입니다. 이 중 60%는 허가 취득에 7년이 소요되는 새로운 345kV 송전선이 필요합니다. FERC 지침 2023에 따라 ‘준비가 완료된 순서대로 우선 처리’하는 방식으로의 전환이 진행되고 있지만, 2024년 중반 시점에서 이를 완전히 시행하고 있는 곳은 CAISO뿐이므로, 대부분의 개발사는 여전히 순차적 처리에 직면해 있습니다. 60억 달러에 달하는 송전 비용 분담 방식을 둘러싼 분쟁으로 인해, 작년에는 5개의 프로젝트가 중단되었습니다.
부문 분석
2025년 누적 발전 용량의 99.88%를 육상 자산이 차지했으며, 이는 텍사스주와 그레이트 플레인스 지역에서 수십 년에 걸쳐 단계적으로 확장되어 온 것을 반영한 것입니다. 이 지역에서는 5-7등급의 풍력 자원이 45-50%의 설비 이용률을 가져다주고 있습니다. 그러나 해양에너지관리국(BOEM)은 2022년 이후 8개의 임대 구역을 경매에 부쳤으며, 이를 통해 해상 풍력 발전 용량이 연평균 성장률(CAGR) 47.69%로 확대될 기반이 마련되어 미국의 풍력 발전 시장을 재편하게 될 것입니다. ‘비니야드 윈드 1’은 2024년 5월 상업 운전을 시작하여 13 MW 터빈으로 60%의 설비 이용률을 유지했으며, 해상 풍력 발전의 경쟁력을 입증했습니다. 텍사스주와 오클라호마주에서는 육상 풍력 발전 건설 사이클이 지속되고 있으며, 2024년에는 두 주를 합쳐 5GW가 추가되었습니다. 이는 ERCOT의 머천트 모델 덕분에 여전히 18개월 이내에 프로젝트 승인이 이루어지고 있기 때문입니다.
존스법의 제약으로 인해 2026년까지 해상 풍력 발전의 건설 규모는 연간 약 2GW로 제한되어 있지만, 프로젝트 파이프라인은 총 30GW에 달할 전망입니다. 도미니언 에너지(Dominion Energy)사의 2.6GW 규모 ‘코스트 버지니아(Coast Virginia)’ 사업은 미국에서 건조된 최초의 설치선을 확보했으나, 일일 임대료가 50만 달러를 초과하기 때문에 유럽의 유사 사례와 비교해 설비 투자액이 12% 더 높습니다. 노후화된 육상 발전소의 리파워링도 병행되는 성장의 원동력이 됩니다. 넥스텔라의 아이오와주 1.8GW 규모 프로젝트에서는 새로운 계통 연계 신청 없이 발전소의 발전량을 3배로 늘렸습니다. 캘리포니아주의 25GW 자원을 대상으로 한 부유식 해상 풍력 발전 구상은 여전히 상용화 전 시험 단계에 머물러 있습니다. 이는 계류 시스템 비용이 현재 1MW당 100만 달러이며, 이 장벽이 2028년 이전에 해소될 전망이 희박하기 때문입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the United States wind energy market size was valued at 161.20 gigawatt in 2025 and estimated to grow from 167.92 gigawatt in 2026 to reach 205.93 gigawatt by 2031, at a CAGR of 4.17% during the forecast period (2026-2031).
This report is Segmented by Location (Onshore and Offshore), Turbine Capacity (Less Than 3 MW, 3 To 6 MW, and Above 6 MW), and Application (Utility-Scale, Commercial and Industrial, and Community Projects). The Market Size and Forecasts are Provided in Terms of Installed Capacity (GW).
United States Wind Energy Market Trends and Insights
IRA Tax Credits and PTC Extensions
The IRA's 10-year extension of production tax credits through 2032, plus a 10-percentage-point domestic-content adder, lifted post-tax project returns from 6.5% to 8.2%. Announcements for 18 GW of new capacity entered development pipelines during 2024 after the legislation was passed. The law mandates that, by 2025, 40% of steel and 55% of manufactured components originate domestically, steering orders toward Iowa and Colorado factories. Internal Revenue Service audits in late 2024 disqualified 1.2 GW for foreign-origin bearings, spotlighting traceability gaps. Developers in ERCOT now opt for the IRA's 30% investment tax credit to monetize value upfront when volatile basis risk deters long-term PPAs.
Falling LCOE from Taller Turbines
National Renewable Energy Laboratory data show the onshore LCOE sliding to USD 26 per MWh in 2024 as rotor diameters hit 170 m and hub heights 110 m. GE Vernova and Vestas platforms above 6 MW are harvesting 52% capacity factors at Class 4 sites in Arkansas and Tennessee, regions once uneconomical for wind. Thermoplastic composite blades reduce weight by 12% and cut balance-of-system spending by USD 80,000 per turbine. Cost compression has pushed eight gigawatts of gas-fired generation into early retirement during 2024, a pivotal inflection for the United States wind energy market.
Transmission and Interconnection Bottlenecks
Regional transmission queues reached 2,600 GW in December 2024, with wind accounting for 950 GW, and average study times stretched to 5.2 years. MISO alone holds 180 GW awaiting USD 48 billion in network upgrades, 60% of which need new 345-kV lines that require seven years to permit. FERC Order 2023 moves to a first-ready, first-served regime, but only CAISO has fully implemented it by mid-2024, so most developers still face serial processing. Disputes over how to share USD 6 billion of transmission costs halted five projects last year.
Other drivers and restraints analyzed in the detailed report include:
- Corporate PPAs Momentum
- Repowering Aging Fleet Unlocks Capacity
- Rising Capex and Supply-Chain Inflation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Onshore assets dominated 99.88% of cumulative capacity in 2025, reflecting decades of incremental build-out across Texas and the Great Plains, where Class 5-7 wind resources deliver 45-50% capacity factors. However, the Bureau of Ocean Energy Management has auctioned eight lease areas since 2022, setting the stage for a 47.69% CAGR in offshore capacity that will reshape the United States wind energy market. Vineyard Wind 1 began commercial operation in May 2024 with 13 MW turbines sustaining 60% capacity factors, demonstrating offshore competitiveness. The onshore build cycle continues in Texas and Oklahoma, which added 5 GW combined in 2024 because ERCOT's merchant model still clears projects within 18 months.
Jones Act constraints limit offshore build-out to about 2 GW per year through 2026, yet project pipelines total 30 GW. Dominion Energy's 2.6 GW Coastal Virginia venture secured the first U.S.-built installation vessel, but day-rates above USD 500,000 lift capex 12% versus European analogs. Repowering older onshore sites provides a parallel growth lever: NextEra's 1.8 GW Iowa campaign tripled site output without new interconnection filings. Floating offshore concepts for California's 25 GW resource remain in pre-commercial testing as mooring systems presently cost USD 1 million per MW, a hurdle unlikely to fall before 2028.
Complete Report Scope:
- By Location
- Onshore
- Offshore
- By Turbine Capacity
- Up to 3 MW
- 3 to 6 MW
- Above 6 MW
- By Application
- Utility-scale
- Commercial and Industrial
- Community Projects
- By Component (Qualitative Analysis)
- Nacelle/Turbine
- Blade
- Tower
- Generator and Gearbox
- Balance-of-System
List of Companies Covered in this Report:
- NextEra Energy Resources LLC
- Berkshire Hathaway Energy (MidAmerican)
- Invenergy LLC
- Avangrid Renewables LLC
- Duke Energy Sustainable Solutions
- Orsted North America
- Dominion Energy Inc.
- Acciona Energia SA
- EDF Renewables North America
- Enel Green Power North America Inc.
- EDP Renewables North America LLC
- General Electric Vernova
- Siemens Gamesa Renewable Energy
- Vestas-American Wind Technology Inc.
- Nordex USA Inc.
- TPI Composites Inc.
- Pattern Energy Group LP
- Clearway Energy Group
- RES Americas Inc.
- Apex Clean Energy Inc.
- Trident Winds Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IRA tax credits & PTC extensions
- 4.2.2 Falling LCOE from taller turbines
- 4.2.3 Corporate PPAs momentum
- 4.2.4 Repowering ageing fleet unlocks capacity
- 4.2.5 Green-hydrogen wind demand nexus
- 4.2.6 Domestic-content bonus under IRA
- 4.3 Market Restraints
- 4.3.1 Transmission & interconnection bottlenecks
- 4.3.2 Rising capex & supply-chain inflation
- 4.3.3 Jones-Act vessel shortage (offshore)
- 4.3.4 Wildlife litigation & local opposition
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Location
- 5.1.1 Onshore
- 5.1.2 Offshore
- 5.2 By Turbine Capacity
- 5.2.1 Up to 3 MW
- 5.2.2 3 to 6 MW
- 5.2.3 Above 6 MW
- 5.3 By Application
- 5.3.1 Utility-scale
- 5.3.2 Commercial and Industrial
- 5.3.3 Community Projects
- 5.4 By Component (Qualitative Analysis)
- 5.4.1 Nacelle/Turbine
- 5.4.2 Blade
- 5.4.3 Tower
- 5.4.4 Generator and Gearbox
- 5.4.5 Balance-of-System
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 NextEra Energy Resources LLC
- 6.4.2 Berkshire Hathaway Energy (MidAmerican)
- 6.4.3 Invenergy LLC
- 6.4.4 Avangrid Renewables LLC
- 6.4.5 Duke Energy Sustainable Solutions
- 6.4.6 Orsted North America
- 6.4.7 Dominion Energy Inc.
- 6.4.8 Acciona Energia SA
- 6.4.9 EDF Renewables North America
- 6.4.10 Enel Green Power North America Inc.
- 6.4.11 EDP Renewables North America LLC
- 6.4.12 General Electric Vernova
- 6.4.13 Siemens Gamesa Renewable Energy
- 6.4.14 Vestas-American Wind Technology Inc.
- 6.4.15 Nordex USA Inc.
- 6.4.16 TPI Composites Inc.
- 6.4.17 Pattern Energy Group LP
- 6.4.18 Clearway Energy Group
- 6.4.19 RES Americas Inc.
- 6.4.20 Apex Clean Energy Inc.
- 6.4.21 Trident Winds Inc.
7 Market Opportunities & Future Outlook
- 7.1 Expansion in the Offshore Sector
- 7.2 Hybrid Wind-Solar-Storage Projects
- 7.3 Green Hydrogen Integration
- 7.4 Repowering Market Potential


