

|
시장보고서
상품코드
2120610
학습 관리 시스템(LMS) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Learning Management System (LMS) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
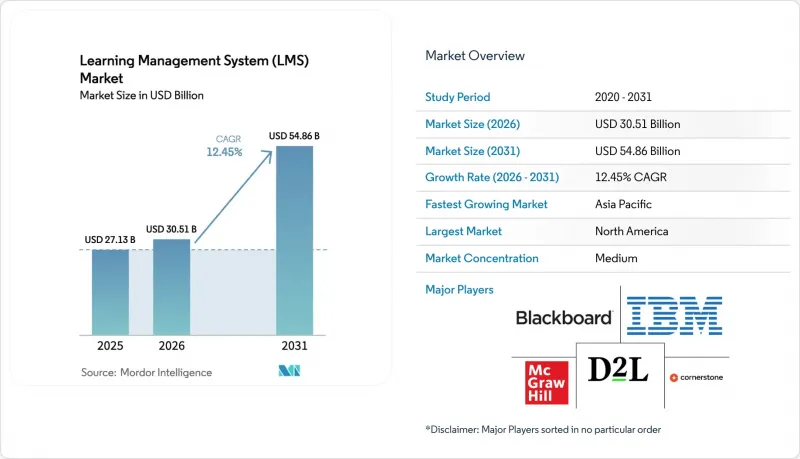
에 의하면, 학습 관리 시스템(LMS) 시장 규모는 2025년 271억 3,000만 달러로 평가되었습니다. 2026년에는 305억 1,000만 달러로 확대되어 2031년까지 548억 6,000만 달러에 이를 것으로 예상되고 2026-2031년에 걸쳐 CAGR 12.45%로 성장할 전망입니다.
본 보고서는 구성 요소별(솔루션, 서비스), 배포 방식별(클라우드, On-Premise), 제공 방식별(원격 교육, 강사 주도형 교육, 기타), 조직 규모별(대기업, 중소기업), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 의료 및 제약, 제조업, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 학습 관리 시스템(LMS) 시장 동향 및 인사이트
원격 근무 및 하이브리드 근무 모델의 가속화에 따른 기업의 LMS 수요 증가
영구적인 하이브리드 근무 방식의 정착으로 인해, 기업의 온보딩 및 규정 준수 교육에 대한 접근 방식이 완전히 바뀌었습니다. 2025년 12월 기준, 포춘 500대 기업의 58%가 유연한 근무지 정책을 유지했으며, 이에 따라 학습 담당 팀은 정적인 포털 사이트에서 Slack이나 Microsoft Teams 내에서 마이크로 레슨을 표시할 수 있는 모바일 지원 플랫폼으로의 전환을 추진했습니다. 개방형 xAPI 텔레메트리를 통해 가상현실(VR) 시뮬레이션, 빠른 참조 동영상, 라이브 웨비나에서의 참여도를 측정할 수 있게 되었으며, 학습 및 개발 담당 관리자는 규정 준수 기한이 만료되기 전에 개입할 수 있게 되었습니다. 2025년 맥킨지의 디지털 역량 강화 조사에 따르면, AI 검색으로 색인화된 동료가 제작한 해설 동영상을 통해 신입 사원의 역량 습득 시간이 23% 단축되었습니다. 기업들은 이러한 소셜 러닝의 성과를 커리큘럼에 통합하여, 고비용의 강사 주도 세션에 대한 의존도를 줄이는 지식 공유 문화를 조성하고 있습니다. 그 결과, 지리적 제약 없이 비동기 및 동기 학습 형태를 통합할 수 있는 플랫폼에 대한 예산 배분이 지속되고 있습니다.
AI를 활용한 적응형 학습 알고리즘 도입을 통한 과정 수료율 향상
생성형 AI는 학습 관리 시스템(LMS) 시장을 단순한 컨텐츠 저장소에서 역동적인 교육 환경으로 변화시키고 있습니다. 2025년, Instructure는 GPT-4를 통합하여 퀴즈 자동 생성 및 토론 요약 기능을 구현했습니다. 이를 통해 학문적 엄격성을 유지하면서도 강사의 채점 시간을 30% 단축했습니다. 적응형 엔진은 퀴즈 점수, 탐색 패턴, 과제 수행 시간을 모니터링하여 중도 탈락 위험을 예측하고, 간소화된 학습 자료 제공이나 동료 멘토링 등의 개입 조치를 취합니다. 적응형 워크플로를 도입한 커뮤니티 칼리지에서는 코호트 기반 교육과 비교해 수료율이 18% 포인트 향상되었습니다. 동일한 알고리즘은 성인 학습자가 숙련도를 입증한 후 다음 단계로 진전할 수 있는 능력 기반 교육 모델의 기반이 되고 있으며, 이러한 접근 방식은 긱 경제가 요구하는 ‘적시 기술 향상’의 필요성과 부합합니다.
학생 1인당 SaaS 라이선스 비용 급등으로 인한 K-12 예산 압박
2025년에는 학습자 1인당 평균 이용료가 11% 급등하여, 미국의 많은 학군에서 교육 기술 예산의 22%를 소모하는 사태가 발생했습니다. 갱신 시 발생하는 고액의 비용에 직면한 관리자들은 프리미엄 LMS 기능과 필수 하드웨어 구입 중 하나를 우선시할 수밖에 없게 되어, 재정이 넉넉한 학교와 자원이 부족한 학교 간의 격차가 확대되고 있습니다. 일부 학군은 컨소시엄 가격으로 협상을 진행하는 반면, 다른 학군은 오픈소스인 무들(Moodle)로의 전환을 추진하고 있습니다. 상업용 벤더가 도입한 프리미엄 모델은 자금 사정에 어려움을 겪는 교육 기관에게 프리미엄 분석 기능이나 적응형 평가를 누릴 수 없는 ‘양극화된 생태계’를 만들어내고 있습니다. 이러한 상황이 개선되지 않으면, 각 학군은 팬데믹 기간 동안 달성한 디지털 문해력 향상을 훼손할 수 있는 구식 학습 방식으로 되돌아갈 위험이 있습니다.
부문별 분석
구성 요소별로 보면, 2025년에는 패키지형 솔루션이 매출 점유율의 71.44%를 차지하며 주류를 이루었으나, 구매자들이 맞춤화 및 관리 업무의 아웃소싱을 늘림에 따라 서비스 부문은 2031년까지 연평균 성장률(CAGR) 14.86%로 성장을 가속화할 것으로 예측됩니다. 2025년에는 솔루션이 매출의 대부분을 차지했지만, 서비스 부문은 두 자릿수 성장을 바탕으로 그 존재감을 확대되고 있습니다. 최고 수준의 학습 제품군을 도입한 기업들은 현재, 역량 프레임워크 매핑부터 서로 다른 인사·급여 시스템 간의 싱글 사인온(SSO) 설정에 이르기까지, 증가하는 통합 작업에 직면해 있습니다. 많은 기업은 99.9%의 가동률을 보장하고, 지역 데이터 거주 규정을 준수하는 세계 컨텐츠 카탈로그를 관리하는 관리형 서비스 제공업체에 의존하고 있습니다.
서비스의 성장은 과정 수료율과 같은 측정 가능한 성과에 보상을 연계하는 성과 연계형 계약을 통해 더욱 가속화되고 있습니다. 이를 통해 공급업체의 인센티브가 학습자의 성공과 연계되며, 위험 회피 성향이 강한 구매 담당자들도 더 대규모의 변혁 예산을 승인하도록 유도되고 있습니다. 교육 기관의 경우, 외부 컨설턴트에 대한 의존도를 낮추고 교직원이 사내에서 디지털 과정을 설계할 수 있도록 지원하는 ‘강사 양성 부트캠프’가 유용합니다. 기업의 아웃소싱과 학술 기관의 역량 강화라는 두 가지 추세가 맞물리면서, 학습 관리 시스템(LMS) 시장에서 서비스가 중요한 수익원으로서의 입지를 공고히 하고 있습니다.
2025년에는 클라우드 도입이 학습 관리 시스템 시장의 88.24%를 차지하며, 변동하는 수강생 수에 적응할 수 있는 탄력적인 인프라의 매력이 부각되었습니다. 다국적 기업들은 개방형 REST API를 통해 플랫폼이 CRM, 전자상거래, 마케팅 자동화 스택에서 학습자 데이터를 가져와 평생에 걸친 참여를 뒷받침하는 통합 프로파일을 생성할 수 있기 때문에 멀티테넌트형 SaaS 모델을 선호합니다. 국방 및 은행업 등 데이터 관리에 관한 엄격한 규제가 적용되는 산업 분야조차도, 기밀성이 높은 기록은 로컬 서버에 보관하면서 분석 대시보드는 퍼블릭 클라우드로 이전하는 하이브리드 아키텍처 도입을 검토하고 있습니다. 제조 공장이나 원격지 캠퍼스 내에 설치된 엣지 컴퓨팅 캐시는 저지연 고해상도 컨텐츠를 제공하는 동시에 숙련도 기록을 중앙 데이터 레이크에 동기화하여 대상 수요를 확대하고, 클라우드의 우위를 더욱 공고히 하고 있습니다.
도입 형태별로 보면, 클라우드 플랫폼은 2025년에 88.24%의 시장 점유율을 차지했을 뿐만 아니라, 2031년까지 연평균 성장률(CAGR) 14.22%로 확대될 것으로 예측됩니다. 반면, On-Premise 및 하이브리드 모델은 한 자릿수 성장에 그치고 있습니다. 특히 전 세계 학습 생태계가 점점 더 분산화되는 가운데, 하드웨어 업데이트 주기에 따른 오버헤드 없이 확장 가능한 서비스를 원하는 조직들에 의해 도입이 더욱 가속화되고 있습니다. 규제가 엄격한 산업에서는 하이브리드형이 제한적으로 계속 지지받고 있지만, 클라우드 도입의 운영 효율성, 통합의 깊이, 분석 기능 덕분에 학습 관리 시스템(LMS) 시장의 주요 기반으로서의 입지가 확고해지고 있습니다.
지역별 분석
2025년, 북미는 36.52%의 점유율을 유지하며 지역별 최대 점유율을 차지했습니다. 미국 기업들은 상세한 기술 격차를 시각화하는 xAPI 준수 분석 기능에 막대한 투자를 하고 있는 반면, 캐나다 정부 기관들은 PIPEDA의 개인정보 보호 요건을 충족하기 위해 이중 언어 제공을 우선시하고 있습니다. 멕시코는 구현 서비스의 니어쇼어 거점으로 부상하고 있으며, 벤더는 실리콘 밸리의 인건비 부담을 지지 않고도 북미에 대한 지원 기간을 연장할 수 있게 되었습니다.
아시아태평양은 인도의 ‘PM eVIDYA 2.0’ 도입과 중국 국영 기업에 대한 스마트 제조 역량 인증 의무화에 힘입어 연평균 성장률(CAGR) 12.88%로 가장 빠르게 성장하고 있는 지역입니다. 일본에서는 노동력 감소를 보완하기 위해 기업의 기술 재교육에 보조금을 지급하고 있으며, LMS 라이선스 비용의 최대 70%를 부담하고 있습니다. 동남아시아의 제조업체들은 높은 이직률에 대응하기 위해 블록체인으로 검증된 자격 정보를 도입하고 있으며, 이 지역은 학습 관리 시스템(LMS) 시장의 성장 동력으로서의 입지를 공고히 하고 있습니다.
유럽에서는 꾸준한 도입이 진행되고 있지만, 데이터 보호 관련 법규가 제각각이기 때문에 벤더들은 여러 데이터 저장 지역을 유지할 수밖에 없습니다. 북유럽 국가들에서는 적응형 평가를 통한 역량 중심 교육을 시범적으로 도입하고 있으며, 독일에서는 견습 제도의 추적을 디지털화하고 있습니다. 또한, 범유럽 컨텐츠 컨소시엄이 코스 라이브러리를 공유하여 개발 비용 절감을 꾀하고 있습니다. 중동의 투자는 오프라인 동기화 기능을 갖춘 모바일 우선 플랫폼에 집중되고 있는 반면, 아프리카의 장벽은 여전히 라스트 마일 연결성입니다. 남미에서는 브라질이 대학 커리큘럼을 디지털화하고, 칠레가 익명화된 분석 데이터를 플랫폼 이용료 할인과 교환하는 민관 라이선싱 모델을 모색하고 있어 그 기세가 점점 더 커지고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the learning management system market size is expected to increase from USD 27.13 billion in 2025 to USD 30.51 billion in 2026 and reach USD 54.86 billion by 2031, growing at a CAGR of 12.45% over 2026-2031.
This report is Segmented by Component (Solutions, and Services), Deployment Mode (Cloud, and On-Premise), Delivery Mode (Distance Learning, Instructor-Led Training, and More), Organization Size (Large Enterprises, Small and Medium Enterprises), End-User Vertical (BFSI, Healthcare and Pharmaceuticals, Manufacturing, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Learning Management System (LMS) Market Trends and Insights
Accelerated Remote and Hybrid Work Models Sustaining Corporate LMS Demand
Permanent hybrid work norms have reshaped enterprise approaches to onboarding and compliance training. As of December 2025, 58% of Fortune 500 employers retained flexible location policies, prompting learning teams to replace static portals with mobile-responsive platforms that surface micro-lessons inside Slack and Microsoft Teams. Open xAPI telemetry now captures engagement across virtual-reality simulations, quick-reference videos, and live webinars, enabling learning-and-development managers to intervene before compliance deadlines lapse. Peer-generated video explainers, indexed by AI search, have shortened time-to-competency for new hires by 23% according to a 2025 McKinsey digital upskilling study. Corporations are inserting these social-learning artifacts into curricula, creating a knowledge-sharing culture that reduces reliance on expensive instructor-led sessions. The upshot is continued budget allocation to platforms that can orchestrate asynchronous and synchronous modalities without geographic constraints.
Integration of AI-Driven Adaptive Learning Algorithms Boosting Course-Completion Rates
Generative AI transforms the learning management system market from a content repository into a dynamic tutoring environment. In 2025, Instructure embedded GPT-4 to auto-generate quizzes and summarize discussions, cutting instructor grading time by 30% while maintaining academic rigor. Adaptive engines monitor quiz scores, navigation patterns, and time-on-task to predict drop-off risk, then trigger interventions such as simplified materials or peer mentoring. Community colleges piloting adaptive workflows posted an 18-percentage-point improvement in completion rates versus cohort-based instruction. The same algorithms underpin competency-based education models that let adult learners progress upon demonstrating mastery, an approach that aligns with the gig economy's demand for just-in-time upskilling.
Rising Per-Learner SaaS-Licensing Inflation Squeezing K-12 Budgets
Average per-learner fees jumped 11% in 2025, consuming 22% of instructional-technology budgets in many U.S. districts. Renewal sticker shock forces administrators to choose between premium LMS features and essential hardware purchases, widening equity gaps between affluent and under-resourced schools. Some districts negotiate consortium pricing, while others migrate to open-source Moodle instances. Freemium tiers introduced by commercial vendors create a two-speed ecosystem in which premium analytics and adaptive assessments remain out of reach for cash-strapped institutions. Without relief, districts risk reverting to outdated learning methods that undercut digital-literacy gains achieved during the pandemic.
Other drivers and restraints analyzed in the detailed report include:
- Government Funding for Digital Education Infrastructure
- Employer Demand for Skills-Verification Micro-Credentials in Asia Pacific Manufacturing Hubs
- Patchy Broadband Coverage Limiting Immersive-Content Delivery in Rural Africa and South Asia
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
By component, packaged solutions dominated with a 71.44% revenue share in 2025, while services are projected to accelerate at a 14.86% CAGR through 2031 as buyers increasingly outsource customization and managed administration. Solutions generated the bulk of revenue in 2025, yet the services segment is widening its footprint on the strength of double-digit growth. Enterprises that deployed best-of-breed learning suites now face mounting integration chores, from mapping competency frameworks to configuring single-sign-on across disparate HR and payroll systems. Many rely on managed-services providers that guarantee 99.9% uptime and manage global content catalogs aligned with regional data-residency rules.
Services growth is further boosted by outcome-based contracts that peg fees to measurable gains such as course-completion rates. This realigns vendor incentives toward learner success and encourages risk-averse buyers to approve larger transformation budgets. Educational institutions also benefit from train-the-trainer bootcamps that reduce dependence on external consultants and enable faculty to design digital courses in-house. The dual dynamic of corporate outsourcing and academic capacity building reinforces services as a pivotal revenue lever in the learning management system (LMS) market.
Cloud deployments commanded 88.24% of the learning management system market in 2025, underscoring the appeal of elastic infrastructure that adapts to fluctuating enrollment. Multinationals favor multi-tenant SaaS models because open REST APIs allow platforms to ingest learner data from CRM, e-commerce, and marketing-automation stacks, creating unified profiles that support lifetime engagement. Even industries with sovereign data mandates, such as defense and banking, are exploring hybrid architectures that keep sensitive records on local servers while shifting analytics dashboards to the public cloud. Edge-computing caches placed inside manufacturing plants and remote campuses serve high-resolution content with low latency while synchronizing mastery records to central data lakes, broadening addressable demand and reinforcing cloud's primacy.
By deployment mode, cloud platforms not only held 88.24% market share in 2025, but are also projected to expand at a 14.22% CAGR through 2031, while on-premise and hybrid models post only single-digit growth. Adoption is further fueled by organizations seeking scalable delivery without the overhead of hardware refresh cycles, particularly as global learning ecosystems grow more distributed. Hybrid blueprints continue to gain selective traction for regulated sectors, yet the operational efficiencies, integration depth, and analytics capabilities of cloud deployments secure their position as the dominant backbone of the learning management system (LMS) market.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Mode
- Cloud
- On-Premise
- By Delivery Mode
- Distance Learning
- Instructor-Led Training
- Blended Learning
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By End-User Vertical
- BFSI
- Healthcare and Pharmaceuticals
- Manufacturing
- Retail and Consumer Goods
- Educational Institutions
- Government Agencies
- Rest of End-User Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Nordics
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- South America
- Brazil
- Mexico
- Rest of South America
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America retained the largest regional share at 36.52% in 2025. United States enterprises invest heavily in xAPI-compliant analytics that surface granular skill gaps, while Canadian government agencies prioritize bilingual delivery to meet PIPEDA privacy mandates. Mexico is emerging as a near-shore hub for implementation services, letting vendors extend North American support windows without incurring Silicon Valley salary costs.
Asia Pacific is the fastest-growing territory with a 12.88% CAGR, propelled by India's PM eVIDYA 2.0 rollout and China's mandate that state-owned enterprises certify smart-manufacturing competencies. Japan subsidizes corporate reskilling to offset workforce shrinkage, covering up to 70% of LMS licensing fees. Southeast Asian manufacturers adopt blockchain-verified credentials to accommodate high labor turnover, cementing the region as a growth engine for the learning management system (LMS) market.
Europe shows steady adoption, but fragmented data-protection statutes force vendors to maintain multiple data-residency zones. Nordic countries pilot competency-based education that relies on adaptive assessments, Germany digitizes apprenticeship tracking, and pan-European content consortia share course libraries to dilute development costs. Middle East investments center on mobile-first platforms with offline-sync, while Africa's barrier remains last-mile connectivity. South America gains momentum as Brazil digitizes university curricula and Chile explores public-private licensing models that exchange anonymized analytics for platform discounts.
- Cornerstone OnDemand Inc.
- Anthology Inc. (Blackboard)
- Instructure Inc.
- D2L Corporation
- SAP SE
- Oracle Corporation
- IBM Corporation
- Docebo SpA
- Adobe Inc.
- Absorb Software Inc.
- TalentLMS (Epignosis LLC)
- McGraw-Hill
- Saba Software
- Infor
- Skillsoft Corporation
- PowerSchool Holdings Inc.
- 360Learning SA
- Thought Industries Inc.
- Meridian Knowledge Solutions
- Google (Classroom)
- Microsoft Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated Remote and Hybrid Work Models Sustaining Corporate LMS Demand
- 4.2.2 Government Funding for Digital Education Infrastructure
- 4.2.3 Integration of AI-Driven Adaptive Learning Algorithms Boosting Course-Completion Rates
- 4.2.4 Employer Demand for Skills-Verification Micro-Credentials in Asia Pacific Manufacturing Hubs
- 4.2.5 Mandatory CPD Regulations in EU Healthcare Catalyzing Specialised LMS Modules
- 4.2.6 BYOD Workforce Mobility Accelerating Mobile-First Cloud LMS Adoption in the Middle East
- 4.3 Market Restraints
- 4.3.1 Rising Per-Learner SaaS-Licensing Inflation Squeezing K-12 Budgets
- 4.3.2 Patchy Broadband Coverage Limiting Immersive-Content Delivery in Rural Africa and South Asia
- 4.3.3 Fragmented Data Standards Hindering HRIS-LMS Integrations in Legacy European Corporates
- 4.3.4 Escalating Cyber-Insurance Premiums Deterring Small Healthcare Providers from Cloud Migration
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers / Learners
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By Delivery Mode
- 5.3.1 Distance Learning
- 5.3.2 Instructor-Led Training
- 5.3.3 Blended Learning
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By End-User Vertical
- 5.5.1 BFSI
- 5.5.2 Healthcare and Pharmaceuticals
- 5.5.3 Manufacturing
- 5.5.4 Retail and Consumer Goods
- 5.5.5 Educational Institutions
- 5.5.6 Government Agencies
- 5.5.7 Rest of End-User Verticals
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 France
- 5.6.2.3 Germany
- 5.6.2.4 Nordics
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Mexico
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East
- 5.6.5.1 Gulf Cooperation Council Countries
- 5.6.5.2 Turkey
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Cornerstone OnDemand Inc.
- 6.4.2 Anthology Inc. (Blackboard)
- 6.4.3 Instructure Inc.
- 6.4.4 D2L Corporation
- 6.4.5 SAP SE
- 6.4.6 Oracle Corporation
- 6.4.7 IBM Corporation
- 6.4.8 Docebo SpA
- 6.4.9 Adobe Inc.
- 6.4.10 Absorb Software Inc.
- 6.4.11 TalentLMS (Epignosis LLC)
- 6.4.12 McGraw-Hill
- 6.4.13 Saba Software
- 6.4.14 Infor
- 6.4.15 Skillsoft Corporation
- 6.4.16 PowerSchool Holdings Inc.
- 6.4.17 360Learning SA
- 6.4.18 Thought Industries Inc.
- 6.4.19 Meridian Knowledge Solutions
- 6.4.20 Google (Classroom)
- 6.4.21 Microsoft Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


