|
시장보고서
상품코드
2120658
독일의 태양에너지 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Germany Solar Energy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
독일의 태양에너지 시장 규모(설치용량 기반)는 2026년 132.25기가와트에서 2031년까지 235.5기가와트로 확대되어 예측 기간(2026-2031년) CAGR은 12.23%가 된다고 전망되고 있습니다.
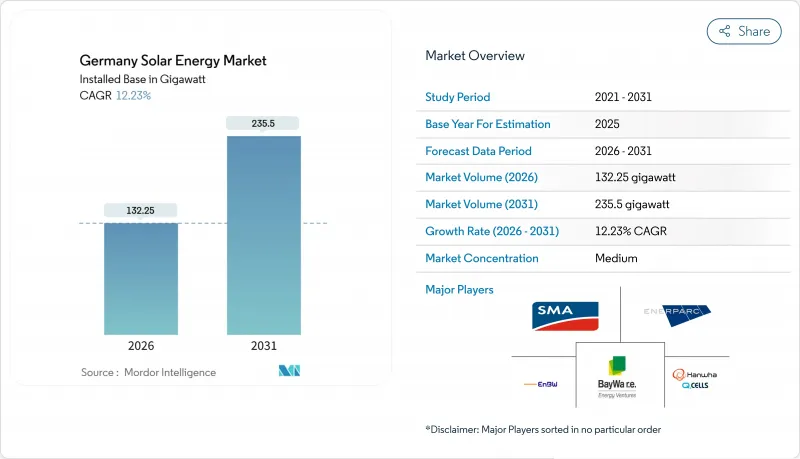
본 보고서는 기술별(태양광 발전 및 집중형 태양광 발전), 계통 연계 형태별(계통 연계형 및 독립형), 최종 사용자별(유틸리티 규모, 상업 및 산업용, 주거용)로 분류되어 있습니다. 시장 규모 및 예측치는 설치 용량(GW) 단위로 표시되어 있습니다.
독일의 태양에너지 시장 동향 및 인사이트
‘솔라 패키지 I’ 및 옥상 설치 의무화로 승인 절차 가속화
2024년 ‘솔라 패키지 I’에 따라 등록 절차가 간소화되고, 발코니용 태양광 발전 인버터의 출력 상한이 800W로 상향 조정됨에 따라 임차인은 집주인의 동의 없이도 직접 시스템을 설치할 수 있게 되었습니다. 2024년 말까지 등록 건수는 약 78만 건에 달했으며, 1년 동안 43만 5,000개의 시스템이 증가했는데, 이는 국내 태양광 발전 신규 도입량의 2.6%에 해당합니다. 현재 바덴뷔르템베르크주와 바이에른주에서는 주 차원의 의무화에 따라 신축 건물 지붕에 태양광 발전 설비 설치가 의무화되었으며, 이로 인해 평균 허가 취득 기간이 18개월에서 6개월 미만으로 단축되어 성장 전망에 약 2.1%의 상승 효과를 가져오고 있습니다. 2025년 10월에는 옥상 태양광 발전 입찰 물량이 소폭 증가하여 281 MW가 9.66센트/kWh에 낙찰되었으며, 초기 단계에서의 성장세가 확인되었습니다. 이러한 움직임은 남부 주에서 가장 두드러지지만, 다른 지역도 개정된 ‘건축물의 에너지 성능에 관한 지침’을 준수함에 따라 보급 범위가 확대될 것으로 예측됩니다.
기업용 PPA 붐이, 보조금에 의존하지 않는 전력 사업 프로젝트를 뒷받침
장기 기업용 PPA가 보조금 지원 입찰을 대체하는 추세가 강해지고 있습니다. Energiekontor사가 2024년에 Currenta사와 체결한 화학 산업단지 전력 공급 계약은 산업용 수요자가 도매 전력 가격의 변동 위험을 헤지하기 위해 고정 가격의 태양광 발전을 확보하고 있음을 보여줍니다. 개발사는 입찰 상한량을 초과하여 발전소 자금 조달이 가능하기 때문에 보조금 없는 프로젝트가 이미 성장을 주도하고 있습니다. 노르트라인-베스트팔렌주와 니더작센주는 대규모 산업용 수요, 출력 억제 위험이 낮다는 점, 그리고 신속한 계통 연계 덕분에 이러한 움직임을 주도하고 있습니다. 모듈 가격 하락으로 인해 개발사는 5센트/kWh 미만의 PPA 요금을 제시할 수 있게 되었으며, 이는 2028년까지의 프로젝트 파이프라인 가속화를 뒷받침하고 있습니다.
배전망 혼잡과 24개월에 달하는 연결 대기 시간
바이에른주와 바덴뷔르템베르크주에서는 접속 대기 기간이 24개월에 육박하여 프로젝트의 현금 흐름을 지연시키고, 기준선 연평균 성장률(CAGR)을 1.9포인트 끌어내리고 있습니다. 2022년 재조정 비용이 40억 유로를 초과했고, 2024년 피크일에는 지상 태양광 발전의 출력 억제율이 13%를 넘은 것은 송전망의 여유 용량이 제한적임을 보여줍니다. 각 개발사는 프로젝트 계획을 니더작센주나 노르트라인-베스트팔렌주로 전환하고 있지만, 이 지역들에서도 변압기 여유 용량이 빠르게 소진되고 있어 입찰 시 수주율 하락을 가격에 반영할 수밖에 없는 상황입니다. 연방 네트워크청(Bundesnetzagentur)은 2024년에도 약 3,800건의 접속 승인을 발급했으나, 승인에서 전력 공급까지의 간격은 분기마다 확대되고 있습니다. 케이블 업그레이드가 가속화되지 않는 한, 독일의 태양에너지 시장은 가까운 시일 내에 신규 설비 도입을 억제하는 단계적 가동 일정에 직면하게 될 것입니다.
부문별 분석
2025년, 태양광 발전(PV)은 독일의 태양에너지 시장 점유율의 100%를 차지했으며, 2031년까지 연평균 12.2%의 성장률을 보일 것으로 예측됩니다. 2024년에 프라운호퍼 ISE와 한화 Q CELLS가 30.8% 효율의 페로브스카이트-실리콘 탠덤 셀을 인증하고, 2028년까지 상용 모듈이 등장할 가능성을 시사한 지금, 실리콘의 총량보다 효율의 비약적인 향상이 중요해지고 있습니다. 출력 밀도의 향상으로 지지대 및 토지 비용을 최대 15% 절감할 수 있으며, 인허가 과정에서 기존 부지(브라운필드)가 우선시되는 상황에서 이는 매우 중요한 요소가 됩니다. 바이에른주에서 진행 중인 아그리볼타이크 시범 사업에서는 고가식 양면 수광 트래커 아래에서 작물과 패널이 공존하고 있어, 토지 이용에 대한 반대 여론을 완화하고 농가의 수입원을 확대되고 있습니다. 집중형 태양광 발전은 확산 일사량으로 인해 열역학적 우위가 약화되기 때문에 여전히 보급되지 않고 있습니다.
페로브스카이트의 내구성은 여전히 과제로 남아 있지만, 2010년부터 2020년에 걸쳐 독일의 연구비는 EU 민간 태양광 발전 연구개발비의 64%를 차지하고 있어, 국내 연구 기관들이 이 과제를 해결할 태세를 갖추고 있습니다. 은행 대출의 타당성이 입증되면, 전력 사업자는 송전선 1킬로미터당 더 많은 메가와트를 배치할 수 있게 되어, 발전 제한을 어느 정도 완화할 수 있습니다. 따라서 독일의 태양에너지 시장에는 설치 면적당 출력을 높임으로써 향후 송전망의 제약을 완화할 수 있는 기술적 상향 여지가 내재되어 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the Germany solar energy market size in terms of installed base is expected to grow from 132.25 gigawatt in 2026 to 235.5 gigawatt by 2031, at a CAGR of 12.23% during the forecast period (2026-2031).
This report is Segmented by Technology (Solar Photovoltaic and Concentrated Solar Power), Grid Type (On-Grid and Off-Grid), and End-User (Utility-Scale, Commercial and Industrial, and Residential). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
Germany Solar Energy Market Trends and Insights
Solar Package I & Rooftop Mandates Accelerating Approvals
The 2024 Solar Package I simplified registrations and raised the balcony-PV inverter limit to 800 W, allowing tenants to self-install systems without landlord consent. Registrations reached about 780,000 units by year-end 2024, adding 435,000 systems in a single year and equaling 2.6% of national solar additions. State-level mandates now require solar on new roofs in Baden-Wurttemberg and Bavaria, cutting average permitting times from 18 months to under six and adding roughly 2.1 percentage points to forecast growth. Rooftop auction volumes ticked up in October 2025, with 281 MW awarded at 9.66 cents/kWh, confirming early traction. The driver is strongest in southern states, but uptake is expected to broaden as other regions align with the revised Energy Performance of Buildings Directive.
Corporate PPA Boom Lifting Unsubsidised Utility Projects
Long-term corporate PPAs are increasingly displacing subsidy auctions. Energiekontor's 2024 deal with Currenta to power a chemical park shows industrial buyers locking in fixed-price solar to hedge wholesale volatility. Unsubsidised projects already propel growth because developers can finance plants outside capped auction volumes. North Rhine-Westphalia and Lower Saxony lead activity thanks to large industrial loads, lower curtailment risk, and quicker grid connections. Falling module prices let developers offer PPA rates below 5 cents/kWh, supporting pipeline acceleration through 2028.
Distribution-Grid Congestion & 24-Month Queue Times
Connection backlogs near 24 months in Bavaria and Baden-Wurttemberg delay project cashflow and shave 1.9 percentage points off the baseline CAGR. Redispatch costs above EUR 4 billion in 2022 and onshore solar curtailment topping 13% on peak 2024 days illustrate the grid's limited headroom. Developers are redirecting pipelines toward Lower Saxony and North Rhine-Westphalia, yet even there, transformer slots fill fast, forcing bids to price in lower capture rates. Bundesnetzagentur still issued around 3,800 connection commitments in 2024, but the gap between commitment and energization widens every quarter. Unless accelerated cable upgrades materialize, the German solar energy market faces staggered commissioning schedules that dampen near-term additions.
Other drivers and restraints analyzed in the detailed report include:
- Rising Grid-Fee Inflation Driving Behind-the-Meter PV + Storage
- Mass Adoption of Balcony-Plug-in PV by Renters
- Skilled-Labour Shortages in Licensed Electricians & Installers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solar PV held 100% of Germany's solar energy market share in 2025 and is forecast to expand at 12.2% annually through 2031. Efficiency leaps matter more than raw silicon volume now that Fraunhofer ISE and Hanwha Q CELLS certified a 30.8% perovskite-silicon tandem cell in 2024, hinting at commercial modules by 2028. Higher power density can cut racking and land costs up to 15%, a vital lever as permitting favors brownfield sites. Agrivoltaic pilots in Bavaria show crops and panels co-existing under elevated bifacial trackers, easing land-use opposition and broadening farmer income. Concentrated solar power remains absent because diffuse irradiation weakens its thermodynamic advantage.
Perovskite durability is the remaining hurdle, but German research spending represented 64% of EU private PV R&D during 2010-2020, positioning domestic labs to solve it. Once bankability proofs emerge, utility developers can fit more megawatts per kilometer of feeder line, alleviating some curtailment. The German solar energy market, therefore, embeds a technology upside optionality that could temper future grid constraints by delivering more output per site footprint.
Complete Report Scope:
- By Technology
- Solar Photovoltaic (PV)
- Concentrated Solar Power (CSP)
- By Grid Type
- On-Grid
- Off-Grid
- By End-User
- Utility-Scale
- Commercial and Industrial (C&I)
- Residential
- By Component (Qualitative Analysis)
- Solar Modules/Panels
- Inverters (String, Central, Micro)
- Mounting and Tracking Systems
- Balance-of-System and Electricals
- Energy Storage and Hybrid Integration
List of Companies Covered in this Report:
- BayWa r.e. AG
- SMA Solar Technology AG
- EnBW Energie Baden-Wurttemberg AG
- Hanwha Q CELLS GmbH
- IBC Solar AG
- Enerparc AG
- RWE Renewables GmbH
- Encavis AG
- juwi GmbH
- ABO Wind AG
- Vattenfall GmbH
- BayWa r.e. Power Solutions GmbH
- Next2Sun GmbH
- Solnet Green Energy OY
- Axitec Energy GmbH & Co. KG
- Solarwatt GmbH
- Meyer Burger Technology AG (Freiberg)
- Tesla Germany GmbH (Powerwall & Roof)
- 1KOMMA5° GmbH
- Centrotherm International AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Solar Package I & Rooftop Mandates Accelerating Approvals
- 4.2.2 Corporate PPA Boom Lifting Unsubsidised Utility Projects
- 4.2.3 Rising Grid-Fee Inflation Driving Behind-the-Meter PV + Storage
- 4.2.4 Mass Adoption of Balcony-Plug-in PV by Renters
- 4.2.5 87 % Module-Price Collapse Enables Cost-Parity vs. Wholesale
- 4.2.6 Integrated BIPV Requirements in New-Build Codes (from 2026)
- 4.3 Market Restraints
- 4.3.1 Distribution-Grid Congestion & 24-Month Queue Times
- 4.3.2 Skilled-Labour Shortages in Licensed Electricians & Installers
- 4.3.3 60 % Cost Gap on EU-vs-China Modules Creating Supply-Risk
- 4.3.4 Declining FiTs & Sudden Subsidy Tweaks Eroding Residential ROI
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook (EEG 2023, Solar-Paket I, State Rooftop Mandates)
- 4.6 Technological Outlook (Perovskite Tandems, Agrivoltaics, Vehicle-Integrated PV)
- 4.7 Porter's Five Forces
- 4.7.1 Competitive Rivalry
- 4.7.2 Threat of New Entrants
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Bargaining Power of Suppliers
- 4.7.5 Threat of Substitutes (Wind, Heat-Pumps, Demand Response)
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Solar Photovoltaic (PV)
- 5.1.2 Concentrated Solar Power (CSP)
- 5.2 By Grid Type
- 5.2.1 On-Grid
- 5.2.2 Off-Grid
- 5.3 By End-User
- 5.3.1 Utility-Scale
- 5.3.2 Commercial and Industrial (C&I)
- 5.3.3 Residential
- 5.4 By Component (Qualitative Analysis)
- 5.4.1 Solar Modules/Panels
- 5.4.2 Inverters (String, Central, Micro)
- 5.4.3 Mounting and Tracking Systems
- 5.4.4 Balance-of-System and Electricals
- 5.4.5 Energy Storage and Hybrid Integration
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 BayWa r.e. AG
- 6.4.2 SMA Solar Technology AG
- 6.4.3 EnBW Energie Baden-Wurttemberg AG
- 6.4.4 Hanwha Q CELLS GmbH
- 6.4.5 IBC Solar AG
- 6.4.6 Enerparc AG
- 6.4.7 RWE Renewables GmbH
- 6.4.8 Encavis AG
- 6.4.9 juwi GmbH
- 6.4.10 ABO Wind AG
- 6.4.11 Vattenfall GmbH
- 6.4.12 BayWa r.e. Power Solutions GmbH
- 6.4.13 Next2Sun GmbH
- 6.4.14 Solnet Green Energy OY
- 6.4.15 Axitec Energy GmbH & Co. KG
- 6.4.16 Solarwatt GmbH
- 6.4.17 Meyer Burger Technology AG (Freiberg)
- 6.4.18 Tesla Germany GmbH (Powerwall & Roof)
- 6.4.19 1KOMMA5° GmbH
- 6.4.20 Centrotherm International AG
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment (e.g., Vehicle-to-Grid PV, Industrial Heat-via-PV-Electrolysis)