

|
시장보고서
상품코드
2120713
마케팅 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Marketing Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
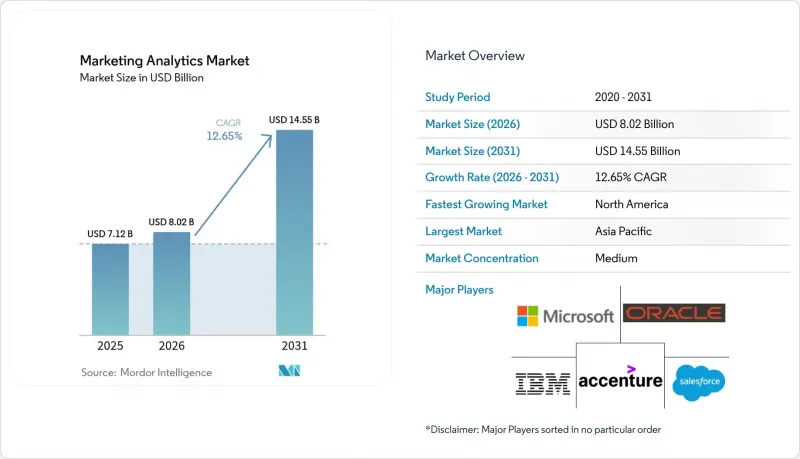
마케팅 분석 시장 규모는 2025년 71억 2,000만 달러로 평가되었고, 2026년에는 80억 2,000만 달러로 추정되고, 2026-2031년 CAGR 12.65%로 성장을 지속할 전망이며, 2031년에는 145억 5,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 도입 형태별(클라우드 및 온프레미스), 용도별(온라인 마케팅, 이메일 마케팅, 컨텐츠 마케팅, 소셜 미디어 마케팅 등), 최종 사용자별(소매, 은행 및 금융 서비스, 교육, 의료, 제조, 여행·호텔업 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 마케팅 분석 시장 동향 및 인사이트
AI를 활용한 예측 인사이트가 마케팅 ROI 향상
현재, 머신러닝 알고리즘은 구매 경향, 생애 가치 및 해지 확률을 밀리초 단위로 평가하고 있으며, 통제된 테스트에서 85% 이상의 정확도를 달성하고 있습니다. 2024년 7월 Google Analytics 4가 자율형 인사이트 카드를 출시한 것은 내장된 AI가 수동 세분화를 배제하고 수익성이 높은 코호트에 예산을 재분배함으로써 도입 기업의 ROI를 15-25% 향상시키고 있음을 보여줍니다. 한때 디지털 네이티브 기업으로만 국한되었던 예측 기능은 이제 필수 요건이 되어가고 있으며, 기존 벤더들은 동등한 모델을 도입하거나 시장에서 도태될 위험에 직면해야 한다는 압박이 커지고 있습니다.
클라우드 네이티브 분석 플랫폼의 가속화
기업들은 쿼리 워크로드를 탄력적으로 확장하고, 프로비저닝 주기를 몇 주에서 몇 분으로 단축하는 서버리스 스택으로의 전환을 추진하고 있습니다. 2025년 1월, 마이크로소프트가 Clarity의 행동 로그와 Google Ads 데이터 세트를 연동한 것은 온프레미스 환경에서는 지금까지 실현하기 어려웠던 크로스 플랫폼 통합을 입증한 사례입니다. 그 결과, 마케팅 분석 시장에서는 로우코드 API를 제공하는 벤더가 지지를 얻고 있으며, 기술적 지식이 없는 마케터라도 IT 부서의 지원을 기다리지 않고 실험을 시작할 수 있게 되었습니다.
높은 총소유비용(TCO)과 통합의 복잡성
데이터 통합, 스키마 조화, 품질 보증 비용을 합산하면 플랫폼 이용료는 프로그램 전체 비용의 극히 일부에 불과합니다. 레거시 스택을 보유한 기업에서는 통합에 6-12개월이 소요되며, 3년 동안의 지속적인 유지보수 비용이 당초 예산의 2배에 달하는 경우도 드물지 않습니다. 따라서 전담 데이터 엔지니어를 보유하지 않은 중견 기업은 보다 가벼운 SaaS 제품군을 선호하는 경향이 있으며, 그 결과 이용 가능한 기능이 제한될 수밖에 없습니다.
부문 분석
클라우드 모델은 2025년에 마케팅 분석 시장의 61.58% 점유율을 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 12.96%로 성장할 것으로 전망됩니다. 따라서 클라우드 도입에 따른 마케팅 분석 시장 규모는 예측 기간 동안 약 2배로 증가할 것으로 보입니다. 기업들은 GPU 가속 AI 서비스에 대한 접근성과 자본 지출을 피할 수 있는 종량제 요금제를 활용하기 위해 클라우드를 선택하고 있습니다. 금융 및 의료 분야에서는 데이터 주권 규정에 따라 로컬 처리가 요구되기 때문에 온프레미스 도입이 여전히 주류를 이루고 있지만, 이러한 업계에서도 모델링을 위해 익명화된 데이터를 클라우드로 전송하는 하이브리드 모델을 시범적으로 도입하고 있습니다.
‘클라우드 퍼스트’ 지출 패턴은 셀프 서비스형 분석으로의 문화적 전환을 반영합니다. 현재 마케팅 팀은 IT 부서의 업무 적체를 기다릴 필요 없이 SQL이 필요 없는 대시보드를 구축하고, 업리프트 테스트를 실행하며, 미디어 플랫폼에서 부문을 활성화할 수 있게 되었습니다. Adobe와 Snowflake 및 Google BigQuery와의 제휴를 통해 고객은 분석 워크스페이스 내에서 직접 페타바이트 규모의 데이터셋에 대해 쿼리를 실행할 수 있습니다. 이러한 ‘조합성’은 실시간 광고 입찰에서 생성형 AI를 활용한 카피 최적화에 이르기까지, 미래 혁신의 기반이 될 것입니다.
지역별 분석
2025년, 북미는 마케팅 분석 시장 매출 점유율의 41.12%를 차지했습니다. 디지털 광고의 높은 성숙도, 풍부한 벤처 자금, 그리고 탄탄한 인재 풀이 정교한 도입을 뒷받침하고 있지만, 쿠키 폐지로 인해 기업들은 퍼스트파티 데이터 수집과 개인정보를 보호하는 어트리뷰션 도입을 가속화할 수밖에 없게 되었습니다. CCPA(캘리포니아주 소비자 개인정보 보호법)에 부응하는 주 차원의 법안으로 인해 규정 준수 범위가 확대되고, 도입까지의 리드타임이 길어지고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 13.31%라는 가장 높은 성장률을 주도하고 있습니다. 2025년에는 슈퍼앱을 통해 컨텐츠를 열람하거나 구매하는 18억 명의 모바일 인터넷 사용자에 힘입어, 이 지역의 디지털 광고비는 2,000억 달러를 넘어설 전망입니다. 중국과 인도가 규모의 기반을 형성하는 한편, 동남아시아 시장에서는 다국어 인사이트와 국경을 초월한 결제가 보급되고 있습니다. 개인정보 보호 관련 법규의 불균일성으로 인해 벤더들은 세심한 현지화와 데이터 수출 제로 설계를 제공할 수밖에 없는 상황입니다.
유럽에서는 GDPR(EU 개인정보보호규정)을 계기로 한 시급성으로 인해 퍼스트파티 데이터베이스 구축 및 페더레이티드 애널리틱스에 대한 투자가 진행되고 있습니다. 독일, 프랑스, 영국은 ‘프라이버시 바이 디자인’을 추진하고 있지만, 언어의 다양성과 규제상의 미묘한 차이로 인해 지역에 특화된 컨설팅 지원이 필요합니다. 중동 및 아프리카 및 남미에서는 시험적인 파일럿 단계에서 대규모 전개로 전환되고 있으며, 대역폭 제약에 적합한 모바일 소셜 커머스 지표와 저지연 대시보드를 우선시하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the marketing analytics market size is expected to grow from USD 7.12 billion in 2025 to USD 8.02 billion in 2026 and is forecast to reach USD 14.55 billion by 2031 at 12.65% CAGR over 2026-2031.
This report is Segmented by Deployment (Cloud, and On-Premise), Application (Online Marketing, Email Marketing, Content Marketing, Social Media Marketing, and More), End User (Retail, Banking and Financial Service, Education, Healthcare, Manufacturing, Travel and Hospitality, and More), and Geography (North America, Europe, Asia Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Marketing Analytics Market Trends and Insights
AI-Powered Predictive Insights Improving Marketing ROI
Machine-learning algorithms now assess purchase propensity, lifetime value, and churn probability in milliseconds, with accuracy above 85% in controlled tests. Google Analytics 4's release of autonomous insight cards in July 2024 shows how embedded AI eliminates manual segmentation and reallocates spend toward high-yield cohorts, lifting ROI by 15-25% for adopters. Predictive capabilities once limited to digital-native firms are therefore becoming table stakes, intensifying pressure on legacy vendors to infuse comparable models or risk displacement.
Acceleration of Cloud-Native Analytics Platforms
Enterprises are migrating to serverless stacks that elastically scale query workloads and cut provisioning cycles from weeks to minutes. Microsoft's January 2025 linkage of Clarity behavioral logs to Google Ads datasets demonstrates cross-platform synthesis that was previously impractical on-premise. The marketing analytics market consequently favors vendors that expose low-code APIs, enabling non-technical marketers to pin up experiments without IT queues.
High Total Cost of Ownership and Integration Complexity
Platform fees represent a fraction of full program costs once data unification, schema harmonization, and quality assurance are tallied. Integration timelines stretch six to twelve months for firms saddled with legacy stacks, and ongoing maintenance often doubles original budgets over a three-year horizon. Mid-market companies without dedicated data engineers therefore gravitate toward lighter SaaS suites, narrowing accessible functionality.
Other drivers and restraints analyzed in the detailed report include:
- Widespread Adoption of Omnichannel Campaign Tracking
- Demand for Real-Time Analytics to Optimize Customer Journeys
- Stringent Data Governance and Privacy Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud models captured 61.58% marketing analytics market share in 2025 and are projected to grow at 12.96% CAGR through 2031. The marketing analytics market size for cloud deployment is therefore on track to almost double during the forecast window. Enterprises choose cloud to access GPU-accelerated AI services and pay-as-you-use pricing that sidesteps capital outlays. On-premise installations persist in finance and healthcare where sovereignty rules demand local processing, but even these industries experiment with hybrid models that pipe de-identified data to the cloud for modeling.
Cloud-first spending patterns mirror a cultural pivot toward self-service analytics. Marketing teams now launch SQL-less dashboards, run uplift tests, and activate segments in media platforms without waiting for IT backlogs. Adobe's partnership with Snowflake and Google BigQuery lets clients query petabyte-scale datasets directly inside analytics workspaces. This composability anchors future innovation, from real-time ad bidding to generative-AI copy optimization.
Complete Report Scope:
- By Deployment
- Cloud
- On-Premise
- By Application
- Online Marketing
- Email Marketing
- Content Marketing
- Social Media Marketing
- Other Applications
- By End User
- Retail
- Banking and Financial Services
- Education
- Healthcare
- Manufacturing
- Travel and Hospitality
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America held 41.12% revenue share of the marketing analytics market in 2025. Deep digital-advertising maturity, ample venture funding, and dense talent pools sustain sophisticated deployments, yet cookie deprecation pushes firms to accelerate first-party data capture and privacy-preserving attribution. State-level bills echoing CCPA broaden compliance scope, extending implementation lead times.
Asia Pacific drives the highest expansion at 13.31% CAGR through 2031. Regional digital-ad spend surpasses USD 200 billion in 2025, underwritten by 1.8 billion mobile internet users who browse and buy via super-apps. China and India anchor scale, while Southeast Asian markets embrace multi-language insights and cross-border payments. Variability in privacy statutes compels vendors to deliver granular localization and zero-data-export designs.
Europe benefits from GDPR-sparked urgency to cultivate first-party databases and invest in federated analytics. Germany, France, and the United Kingdom champion privacy-by-design, but fragmented language and regulatory nuances necessitate region-specific consultative support. Middle East and Africa and South America progress from exploratory pilots to scaled rollouts, prioritizing mobile social commerce metrics and low-latency dashboards that fit bandwidth constraints.
- Adobe Inc.
- Salesforce Inc.
- Oracle Corporation
- SAS Institute Inc.
- IBM Corporation
- Microsoft Corporation
- Teradata Corporation
- HubSpot Inc.
- Google LLC
- SAP SE
- Neustar Inc.
- Pegasystems Inc.
- Tableau Software LLC
- Alteryx Inc.
- Mixpanel Inc.
- Amplitude Inc.
- Sprinklr Inc.
- Hootsuite Inc.
- Marketo Inc.
- Experian plc
- Clarabridge Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Widespread adoption of omnichannel campaign tracking
- 4.2.2 Demand for real-time analytics to optimize customer journeys
- 4.2.3 Acceleration of cloud-native analytics platforms
- 4.2.4 AI-powered predictive insights improving marketing ROI
- 4.2.5 Privacy sandbox forcing first-party data analytics investments
- 4.2.6 Proliferation of composable CDPs enabling modular analytics
- 4.3 Market Restraints
- 4.3.1 High total cost of ownership and integration complexity
- 4.3.2 Abundance of free and freemium analytics tools
- 4.3.3 Stringent data governance and privacy regulations (GDPR, CCPA)
- 4.3.4 Shortage of marketing data-science talent
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 Cloud
- 5.1.2 On-Premise
- 5.2 By Application
- 5.2.1 Online Marketing
- 5.2.2 Email Marketing
- 5.2.3 Content Marketing
- 5.2.4 Social Media Marketing
- 5.2.5 Other Applications
- 5.3 By End User
- 5.3.1 Retail
- 5.3.2 Banking and Financial Services
- 5.3.3 Education
- 5.3.4 Healthcare
- 5.3.5 Manufacturing
- 5.3.6 Travel and Hospitality
- 5.3.7 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia and New Zealand
- 5.4.4.6 Southeast Asia
- 5.4.4.7 Rest of Asia Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Egypt
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Salesforce Inc.
- 6.4.3 Oracle Corporation
- 6.4.4 SAS Institute Inc.
- 6.4.5 IBM Corporation
- 6.4.6 Microsoft Corporation
- 6.4.7 Teradata Corporation
- 6.4.8 HubSpot Inc.
- 6.4.9 Google LLC
- 6.4.10 SAP SE
- 6.4.11 Neustar Inc.
- 6.4.12 Pegasystems Inc.
- 6.4.13 Tableau Software LLC
- 6.4.14 Alteryx Inc.
- 6.4.15 Mixpanel Inc.
- 6.4.16 Amplitude Inc.
- 6.4.17 Sprinklr Inc.
- 6.4.18 Hootsuite Inc.
- 6.4.19 Marketo Inc.
- 6.4.20 Experian plc
- 6.4.21 Clarabridge Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and unmet-need assessment


