|
시장보고서
상품코드
2120771
병원 물품 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hospital Supplies - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
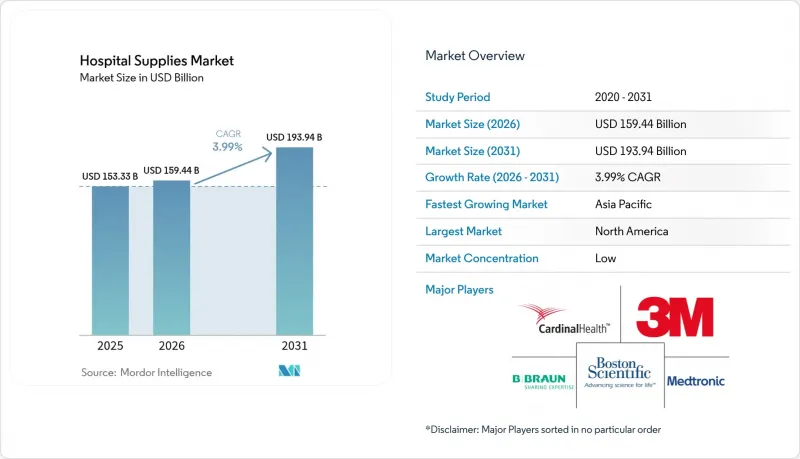
에 의하면, 병원 물품 시장 규모는 2025년 1,533억 3,000만 달러에서 2026년에는 1,594억 4,000만 달러에 이르고, 2026-2031년 CAGR 3.99%로 성장을 지속하여 2031년에는 1,939억 4,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 제품별(환자 검사 기기, 수술실용 기기, 이동 보조 기구 및 이송 기기 등), 최종 사용자별(공립 병원, 사립 병원 및 체인 병원 등), 멸균 상태별(멸균 처리된 의료용품, 비멸균 의료용품), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 병원용 소모품 시장 동향 및 인사이트
전염병 및 만성 질환 발생률 증가
당뇨병, 심혈관 질환, 호흡기 질환 환자 수가 증가함에 따라, 병원들은 상처 관리용 드레싱, 모니터링 키트, 인공호흡 회로의 지속적인 공급을 확보하기 위해 재고 계획을 재검토할 수밖에 없습니다. 당뇨병만 해도 5억 3,700만 명의 성인이 앓고 있으며, 2045년까지 7억 8,300만 명에 달할 것으로 예측됩니다. 이에 따라 2024년 이후 특수 드레싱 사용량이 30% 증가할 것으로 예측됩니다. 현재 의료 시스템에서는 전자 의료 기록 데이터와 예측 재고 관리 알고리즘을 결합하여 예상 환자 수와 보충 주기의 일관성을 더욱 엄격하게 맞추고 있습니다. 이러한 환자 중심의 접근 방식에 따라 다용도 멸균 의료용품에 대한 자본 배분이 확대되고 있으며, 이는 성숙한 경제권과 신흥 경제권 모두에서 병원 물품 시장을 견인하고 있습니다.
병원 내 감염에 대한 대중의 인식 제고
소비자들은 감염 대책의 실적을 어떻게 평가하느냐에 따라 시설을 선택하는 경향이 점점 더 강해지고 있습니다. 병원 내 감염(HAI)이 1건 발생할 때마다 28,400-33,800달러의 치료비가 추가로 발생하기 때문에 병원 관리자들은 접촉 빈도가 높은 표면에 항균 소재를 채택하거나 규정 준수 지표를 공개하는 등 조치를 취하고 있습니다. 미국 질병통제예방센터(CDC)에 따르면, 입원 환자 31명 중 1명이 특정 날에 병원 내 감염(HAI)에 걸리고 있으며, 이는 병원 물품 시장에서 일회용 드레이프, 배리어 가운 및 자가 소독식 의료기기용 커버에 대한 투자를 촉진하고 있습니다. 검증 가능한 무균성 보증과 제품의 추적성을 제공하는 공급업체는 경쟁 우위를 확보하고 있습니다.
엄격한 규제 체계
에틸렌옥사이드 배출 억제를 위한 노력은 연간 약 200억 개의 의료기기 멸균 공정을 위협하고 있습니다. FDA는 멸균 시설의 갑작스러운 폐쇄가 의료 서비스의 연속성을 저해할 우려가 있다고 경고하며, 환경 정책이 병원 물품 시장의 물류에 어떤 파급 효과를 가져올지 보여주고 있습니다. 각 기업은 현재 대체 멸균제 검토 및 예비 생산 능력에 대한 투자를 추진하고 있으며, 이는 이미 촉박한 생산 일정에 추가적인 비용과 복잡성을 더하고 있습니다.
부문 분석
2025년, 일회용품은 병원 물품 시장에서 46.83%의 점유율을 유지하며 교차 오염 방지에 있어 그 역할을 부각시켰습니다. 세트화된 수술 팩과 일회용 가운은 수술실 교체 과정을 효율화하고 세탁에 드는 노력을 줄여줍니다. 그러나 지속가능성 관련 정책을 배경으로, 선별 재처리 및 재활용 가능한 폴리머를 활용한 시범 프로젝트가 시작되고 있으며, 공급업체에게는 수명 주기 배출량 공개가 요구되고 있습니다. 멸균·소독 장비는 중규모 부문에 불과하지만, 2031년까지 연평균 성장률(CAGR) 10.42%로 가장 빠르게 성장하고 있습니다. 멸균 장비의 병원 물품 시장 규모는 장비 사용 허가를 문서화된 미생물 살균 매개변수와 연계하는 디지털 기록 관리 의무화에 따라 확대될 것으로 예측됩니다. 저온 멸균기에 클라우드 기반 검증 소프트웨어를 번들로 제공하는 공급업체는 일류 병원 시스템에서 지지를 얻고 있습니다.
환자 검사 기기 및 수술실용 기기에는 센서 어레이와 IoT 게이트웨이가 내장되어 있습니다. 스마트 청진기, 컴퓨터 지원 내비게이션, AI 기반 수술 중 영상 진단은 고가 시장을 주도하고 있으며, 상호 운용성 평가가 조달 결정에 점점 더 큰 영향을 미치고 있습니다. 이동 보조 기구 및 이송 장비는 고령화 사회가 진행됨에 따라 체압 분산 매트리스, 전동 리프트, 비만 환자용 휠체어에 대한 수요가 증가하고 있다는 인구 통계학적 추세를 반영하고 있습니다. 입찰 평가 과정에서 초기 비용 외에도 지속가능성 노력, 예비 부품의 확보 가능성, 클라우드 기반 진단 기능 등이 중요한 평가 기준으로 고려되고 있습니다.
지역별 분석
북미는 선진적인 인프라와 엄격한 감염 관리 요건으로 인해 2025년 세계 매출의 33.92%를 차지했습니다. RFID 지원 스마트 캐비닛과 AI를 활용한 수요 계획 시스템의 대규모 도입은 풍부한 분석 기능을 갖춘 가치 제안을 하는 공급업체에게 기회를 제공합니다. 관세 불확실성이 가격 안정성을 위협하고 있어, 카디널 헬스(Cardinal Health)와 같은 유통업체들은 2026년 병원 물품 시장의 탄력성에 영향을 미칠 수 있는 비용 전가 메커니즘 도입을 검토하고 있습니다.
아시아태평양은 중국, 인도, 동남아시아의 의료 인프라 확충에 힘입어 연평균 성장률(CAGR) 8.18%라는 가장 강력한 성장세를 보이고 있습니다. 3차 의료 기관에 대한 급속한 투자와 현지 생산을 촉진하는 정부의 인센티브가 맞물리면서, 부품 조달처가 최종 시장과 가까운 곳으로 이동하고 있습니다. 인증 기관들이 유럽과 미국의 감염 관리 기준을 채택함에 따라, 병원용 소모품 시장 중 멸균용 소모품 시장 규모는 급속히 확대되고 있습니다. 태국과 말레이시아의 의료 관광 성장은 고품질이면서도 비용 경쟁력이 있는 일회용 제품의 조달 파이프라인을 더욱 확대시키고 있습니다.
유럽에서는 지속가능성에 관한 규제로 인해 공급업체들이 탄소 발자국 검증 및 재생 폴리머 도입을 촉진하는 등 기술 지향적인 태도가 유지되고 있습니다. 판매량 면에서는 독일이 선두를 차지하는 반면, 스위스의 첨단 니치 제조업체들이 해당 부문의 혁신을 주도하고 있습니다. 의료기기 규정(MDR)에 대한 규제가 명확해짐에 따라, 이를 조기에 도입한 병원들은 스마트 라벨링 및 위변조 방지 포장의 시범 도입을 추진하고 있으며, 성숙한 병원 물품 시장에서 프리미엄 가격대가 유지되고 있습니다.
중동 및 아프리카에서는 현저한 차이가 나타납니다. 걸프협력회의(GCC) 회원국들은 최첨단 멸균실과 자동 재고 관리 시스템이 필요한 플래그십 병원에 대한 투자를 추진하고 있습니다. 한편, 국제금융공사(IFC)의 ‘아프리카 의료기기 시설’은 소규모 의료 서비스 제공업체에게 자금을 지원하여 동아프리카 및 서아프리카 전역에서 필수 의료기기에 대한 분산된 수요를 창출하고 있습니다. 교육, 유지보수, 마이크로리스 제도를 패키지로 제공하는 공급업체들은 가격에 민감하면서도 거래량이 많은 이러한 틈새 시장에서 지지를 얻고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the hospital supplies market size is expected to grow from USD 153.33 billion in 2025 to USD 159.44 billion in 2026 and is forecast to reach USD 193.94 billion by 2031 at 3.99% CAGR over 2026-2031.

This report is Segmented by Product (Patient Examination Devices, Operating Room Equipment, Mobility Aids and Transportation Equipment, and More), End User (Public Hospitals, Private & Chain Hospitals, and More), Sterility (Sterile Supplies, Non-Sterile Supplies), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hospital Supplies Market Trends and Insights
Increasing Incidences of Communicable and Chronic Diseases
Rising diabetes, cardiovascular, and respiratory case loads are forcing hospitals to re-think inventory plans to assure continuous availability of wound-care dressings, monitoring kits, and ventilation circuits. Diabetes alone affects 537 million adults and is projected to reach 783 million by 2045, pushing up specialized dressing use by 30% since 2024. Health systems now pair electronic health-record data with predictive stocking algorithms, enabling tighter alignment between anticipated caseloads and replenishment cycles. This patient-centric approach is steering capital allocations toward versatile sterile supplies, driving the hospital supplies market forward in both mature and emerging economies.
Growing Public Awareness about Hospital-Acquired Infections
Consumers increasingly select facilities based on perceived infection-control performance. Each HAI adds USD 28,400-33,800 in treatment costs, prompting administrators to adopt antimicrobial materials for high-touch surfaces and to publicize compliance metrics. The Centers for Disease Control and Prevention notes that 1 in 31 hospitalized patients contracts an HAI on any given day, spurring hospital supplies market investment into single-use drapes, barrier gowns, and self-disinfecting device casings. Suppliers offering verifiable sterility assurance and product traceability gain a competitive advantage.
Stringent Regulatory Framework
Efforts to curb ethylene-oxide emissions threaten the sterility pathways for roughly 20 billion medical devices annually. The FDA warned that abrupt closures of sterilization plants could disrupt care continuity, illustrating how environmental policy can ripple through hospital supplies market logistics. Firms now investigate alternative sterilants and invest in redundant capacity, adding cost and complexity to already tight production schedules.
Other drivers and restraints analyzed in the detailed report include:
- High Demand for Hospital Supplies in Developing Countries
- Hospital-Acquired Infection Penalties Catalyzing Investment in Sterilization Equipment
- Emergence of Home Care Services
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Disposable supplies retained a 46.83% hospital supplies market share in 2025, underscoring their role in combating cross-contamination. Bundled procedure packs and single-use gowns streamline operating-room turnover and reduce labor spent on laundering. However, sustainability policies have sparked pilot projects in selective re-processing and recyclable polymers, pressuring vendors to declare lifecycle emissions. Sterilization and disinfectant equipment, while only a mid-sized segment, is growing fastest at a 10.42% CAGR to 2031. The hospital supplies market size for sterilization equipment is forecast to climb in tandem with digital record-keeping mandates that tie device release to documented microbial kill parameters. Suppliers that bundle cloud-based validation software with low-temperature sterilizers see traction in tier-1 hospital systems.
Patient examination devices and operating-room equipment are integrating sensor arrays and IoT gateways. Smart stethoscopes, computer-assisted navigation, and AI-driven intraoperative imaging drive premium pricing tiers, with procurement decisions increasingly influenced by interoperability scores. Mobility aids and transportation equipment ride demographic trends as aging populations demand pressure-reducing mattresses, electric hoists, and bariatric wheelchairs. Sustainability credentials, spare-parts availability, and cloud-ready diagnostics are now weighted alongside upfront price when frameworks evaluate bids.
Complete Report Scope:
- By Product
- Patient Examination Devices
- Operating Room Equipment
- Mobility Aids & Transportation Equipment
- Sterilization & Disinfectant Equipment
- Disposable Hospital Supplies
- Syringes & Needles
- Smart RFID-Enabled Consumables
- Other Products
- By End User
- Public Hospitals
- Private & Chain Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics & Trauma Centers
- By Sterility
- Sterile Supplies
- Non-Sterile Supplies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's advanced infrastructure and strict infection-control mandates secured 33.92% share of global revenue in 2025. Large-scale adoption of RFID-enabled smart cabinets and AI-assisted demand-planning systems underpins supplier opportunities for analytics-rich value propositions. Tariff uncertainties threatened price stability, prompting distributors like Cardinal Health to consider pass-through mechanisms that could influence hospital supplies market elasticity in 2026.
Asia-Pacific delivers the strongest growth at an 8.18% CAGR, driven by healthcare capacity expansion in China, India, and Southeast Asia. Rapid investment in tertiary hospitals, coupled with government incentives for local manufacturing, shifts component sourcing closer to end-markets. The hospital supplies market size for sterilization consumables is rising briskly as accreditation bodies adopt Western infection-control benchmarks. Medical tourism growth in Thailand and Malaysia further widens procurement pipelines for high-quality but cost-competitive disposables.
Europe maintains a technology-oriented stance, with sustainability mandates encouraging suppliers to validate carbon footprints and integrate recycled polymers. Germany leads by volume, while Switzerland's high-tech niche manufactures propel segment innovation. Regulatory clarity around the Medical Device Regulation (MDR) encourages early-adopter hospitals to pilot smart labeling and tamper-evident packaging, sustaining premium price points in a mature hospital supplies market.
The Middle East and Africa witness marked divergence. Gulf Cooperation Council nations invest in flagship hospitals that demand state-of-the-art sterilization suites and automated inventory systems. Meanwhile, the International Finance Corporation's Africa Medical Equipment Facility funds small providers, creating distributed demand for essential devices across East and West Africa. Suppliers that bundle training, maintenance, and micro-leasing schemes gain traction in these price-sensitive yet volume-rich niches.
- 3M
- B. Braun
- Baxter
- Beckton Dickinson
- Boston Scientific
- Cardinal Health
- Medtronic
- GE HealthCare Technologies Inc.
- Johnson & Johnson
- Thermo Fisher Scientific
- Danaher
- Eurofins
- STERIS
- Getinge
- Smith+Nephew Plc
- Stryker
- Terumo
- Ecolab
- HARTMANN Group
- Nipro
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Incidences of Communicable and Chronic Diseases
- 4.2.2 Growing Public Awareness about Hospital Acquired Infections
- 4.2.3 High Demand for Hospital Supplies in Developing Countries
- 4.2.4 Hospital-Acquired Infection Penalties Catalyzing Investment in Sterilization Equipment
- 4.2.5 Surge in Surgical Volume Post-Pandemic in Developed Countries
- 4.2.6 Government Initiatives and Healthcare Spending
- 4.3 Market Restraints
- 4.3.1 Stringent Regulatory Framework
- 4.3.2 Emergence of Home Care Services
- 4.3.3 High Costs of Advanced Equipment
- 4.3.4 Supply Chain Disruptions
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers/Consumers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitute Products
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product
- 5.1.1 Patient Examination Devices
- 5.1.2 Operating Room Equipment
- 5.1.3 Mobility Aids & Transportation Equipment
- 5.1.4 Sterilization & Disinfectant Equipment
- 5.1.5 Disposable Hospital Supplies
- 5.1.6 Syringes & Needles
- 5.1.7 Smart RFID-Enabled Consumables
- 5.1.8 Other Products
- 5.2 By End User
- 5.2.1 Public Hospitals
- 5.2.2 Private & Chain Hospitals
- 5.2.3 Ambulatory Surgical Centers
- 5.2.4 Specialty Clinics & Trauma Centers
- 5.3 By Sterility
- 5.3.1 Sterile Supplies
- 5.3.2 Non-Sterile Supplies
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 3M
- 6.3.2 B. Braun Melsungen AG
- 6.3.3 Baxter International Inc.
- 6.3.4 Becton, Dickinson and Company
- 6.3.5 Boston Scientific Corporation
- 6.3.6 Cardinal Health Inc.
- 6.3.7 Medtronic
- 6.3.8 GE HealthCare Technologies Inc.
- 6.3.9 Johnson & Johnson
- 6.3.10 Thermo Fisher Scientific Inc.
- 6.3.11 Danaher Corporation
- 6.3.12 Eurofins Scientific
- 6.3.13 STERIS plc
- 6.3.14 Getinge AB
- 6.3.15 Smith+Nephew Plc
- 6.3.16 Stryker Corporation
- 6.3.17 Terumo Corporation
- 6.3.18 Ecolab Inc.
- 6.3.19 HARTMANN Group
- 6.3.20 Nipro Corporation