|
시장보고서
상품코드
2121452
미국의 온도 센서 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)US Temperature Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
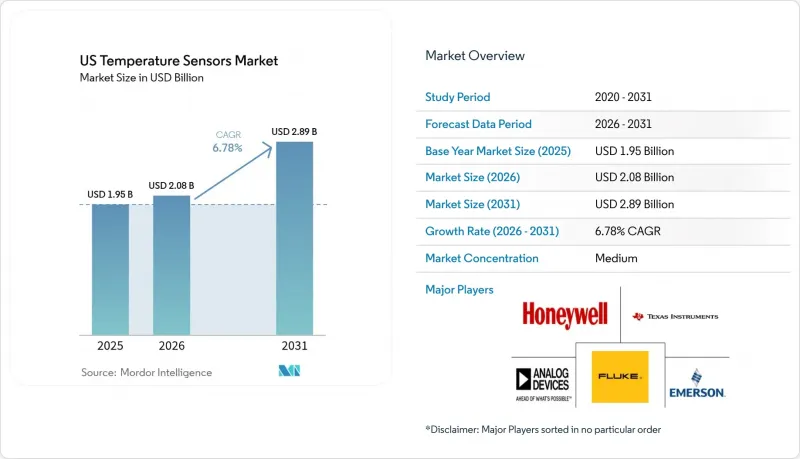
에 의하면, 미국의 온도 센서 시장 규모는 2025년 19억 5,000만 달러에서 2026년에는 20억 8,000만 달러에 이르고, 2026-2031년 CAGR 6.78%로 성장을 지속하여 2031년에는 28억 9,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 유형별(유선, 무선), 기술별(적외선, 열전대, RTD, 서미스터 등), 최종 사용자 산업별(화학제품 및 석유화학제품, 석유 및 가스, 금속 및 광업 등), 연결 방식별(접촉식, 비접촉식), 적용 환경별(산업 공정 모니터링, HVAC 및 빌딩 자동화 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국의 온도 센서 시장 동향 및 인사이트
인더스트리 4.0의 확대와 스마트 팩토리 도입
산업의 디지털화는 AI, 로봇 공학 및 연결된 계측 기기를 융합하여 공장 현장을 혁신하고 있으며, 온도 감지는 이러한 융합의 핵심을 이루고 있습니다. 과거에는 몇 개의 주요 자산만 샘플링하던 예측 유지보수 프로그램은 현재 생산 라인 전체를 아우르는 수백 개의 노드를 갖추고, 기계적 고장이 발생하기 몇 시간 전에 온도 이상을 감지할 수 있게 되었습니다. 텍사스 기기(Texas Instruments)의 신형 센서에 내장된 엣지 AI 칩셋은 로컬 데이터 스트림을 처리하여 클라우드 지연 없이 밀리초 단위의 경보를 통해 자동 대응을 촉발합니다. FOUNDATION Fieldbus 및 PROFINET과 같은 상호 운용 가능한 프로토콜을 통해 시스템 통합이 간소화되었습니다. 또한 견고한 하우징과 광범위한 온도 대응 능력 덕분에 먼지가 많고 진동이 심한 환경에서도 신뢰성 높은 작동을 보장합니다. 그 결과, 미국의 온도 센서 시장은 기존 PLC 네트워크를 대체하는 수요에 더해, 새로 건설되는 스마트 팩토리에서 발생하는 새로운 수요도 계속해서 누리고 있습니다.
웨어러블 소비자용 전자기기에서 온도 감지 수요 증가
소형화 및 저전력 소비 칩을 통해 임상 수준의 온도 정확도가 일상적인 기기에 탑재됨에 따라, 소비자는 ±0.1°C의 정확도로 심부 체온을 추적하여 질병을 조기에 발견할 수 있게 되었습니다. 신축성 있는 기판은 피부에 자극을 주지 않고 며칠 동안 피부에 밀착되며, 듀얼 센서 방식의 외이도형 디자인은 원격 의료 워크플로우에 적합한 연속적인 측정값을 제공합니다. 5세대 셀룰러 통신 및 엣지 컴퓨팅용 칩을 통해 암호화된 데이터 스트림이 의료용 대시보드로 전송되므로, 임상의는 원격으로 개입할 수 있습니다. 이 기능은 재택 간호 프로그램에서 높은 평가를 받고 있습니다. 센서 제조업체에게 이러한 설계 채택은 대량 생산이 가능한 소비자용 채널은 물론, 전력 예산이 마찬가지로 까다로운 산업용 IoT 분야에서 기술적 우위를 가져다줍니다. 그 결과 발생하는 수요로 인해 미국의 온도 센서 시장은 급격한 혁신의 물결을 타고 있습니다.
반도체 및 백금군 금속 가격 변동
갈륨, 게르마늄, 백금의 가격 변동은 RTD(저항 온도 검출기) 및 고정밀 칩 기반 프로브의 비용 구조를 교란시키고 있습니다. 중국이 갈륨과 게르마늄 정제를 장악하고 있어, 미국 구매자들은 수출 규제의 영향을 받기 쉬운 상황에 놓여 있습니다. 한편, 연료전지 및 촉매 변환기에 대한 수요가 급증하는 가운데, 백금 박막공급은 부족해지고 있습니다. 예산의 불확실성으로 인해 업그레이드 프로젝트가 지연될 가능성이 있어, 미국의 온도 센서 시장의 단기 판매량이 감소할 우려가 있습니다.
부문 분석
유선 장치는 안전성이 극히 중요한 루프나 기존 DCS 배선에서의 유선 연결 신뢰성 덕분에 2025년 매출의 68.62%를 차지했으나, 무선 노드는 개조 용이성과 낮은 설치 비용 덕분에 연평균 성장률(CAGR) 10.22%로 확대되고 있습니다. 미국의 온도 센서 시장에서 무선 제품 시장 규모는 데이터센터 및 식품 공장에서의 꾸준한 도입을 반영하여 2031년까지 10억 9,000만 달러에 달할 것으로 예측됩니다. MIT에서 개발된 자가 발전형 하베스터는 배터리 유지보수라는 장벽을 제거하여 펌프, 가마,회전 장비 등에서의 활용 사례를 넓혀가고 있습니다. 광활한 공장에서는 LoRaWAN이나 5G NB-IoT를 통해 밀리와트급 전력 소비로 킬로미터 단위의 통신 범위를 실현함으로써, 플랜트 관리자는 케이블을 매설하지 않고도 세밀한 히트맵을 확보할 수 있게 되었습니다.
주파수 호핑 및 AES-128 암호화가 표준화됨에 따라, 과거 무선 기술을 둘러싸고 있던 신뢰성 우려는 점차 사라지고 있습니다. 엣지 마이크로컨트롤러는 현재 측정값을 전처리하여 패킷의 페이로드를 대폭 줄이고, 공장 백본 회선의 혼잡을 완화하고 있습니다. 한편, 원자력, 제약, 항공우주 분야에서는 거버넌스 프로토콜에 따라 고정 배선 및 아날로그 출력이 의무화되어 있어 유선 기술의 우위는 여전히 지속되고 있습니다. 4-20mA 루프와 Wi-Fi 또는 서브GHz 무선을 연결하는 혼합 모드 게이트웨이를 번들로 제공하는 공급업체들은 하이브리드 도입의 물결을 타고 미국의 온도 센서 시장에서 점유율을 확대되고 있습니다.
열전대는 최대 2,300°C에 이르는 극한 고온을 감지할 수 있어 2025년 매출의 31.95%를 차지했으나, 산업 분야에서 점 측정보다 공간 분해능이 요구됨에 따라 분산형 광섬유 시스템 시장은 연평균 성장률(CAGR) 11.10%로 급성장하고 있습니다. DTS(분산형 온도 감지) 분야의 미국의 온도 센서 시장 규모는 2031년까지 5억 2,540만 달러를 넘어설 것으로 예측됩니다. EMI의 영향을 받지 않는 광섬유 회선은 전자 기기가 작동하지 않는 고전압 베이나 유도 용광로 내부에서도 사용할 수 있습니다. Luna Innovations사의 고해상도 장치는 서브mm 단위의 분해능을 실현하여, 배터리 모듈이나 극저온 파이프라인 매핑에 활용되고 있습니다.
저항식 온도 검출기(RTD)는 ±0.1°C의 정밀도가 요구되는 제약 업계의 클린룸이나 계측 실험실에서 여전히 주류를 차지하고 있습니다. 서미스터는 비용 효율을 중시하는 기기에 채택되고 있는 반면, 적외선 어레이는 예측 유지보수를 위한 열화상 기술을 구현하고 있습니다. HART, Modbus 또는 이더넷 프로토콜을 지원하는 하이브리드형 트랜스미터는 디지털 트윈과의 통합을 간소화합니다. 감지 소자, 헤드 마운트형 트랜스미터, 분석용 펌웨어를 풀스택으로 제공하는 벤더는 지속적인 수익을 강화하고, 미국의 온도 센서 시장에서의 입지를 공고히 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the US temperature sensors market size is expected to grow from USD 1.95 billion in 2025 to USD 2.08 billion in 2026 and is forecast to reach USD 2.89 billion by 2031 at 6.78% CAGR over 2026-2031.
This report is Segmented by Type (Wired, Wireless), Technology (Infrared, Thermocouple, RTD, Thermistor and More), End-User Industry (Chemical and Petrochemical, Oil and Gas, Metal and Mining and More), Connectivity (Contact, Non-Contact), Application Environment (Industrial Process Monitoring, HVAC and Building Automation and More). The Market Forecasts are Provided in Terms of Value (USD).
US Temperature Sensors Market Trends and Insights
Expansion of Industry 4.0 and smart-factory adoption
Industrial digitalization reshapes factory floors by fusing AI, robotics, and connected instrumentation, and temperature sensing sits at the heart of that convergence. Predictive maintenance programs that once sampled a few key assets now blanket entire production lines with hundreds of nodes that flag thermal deviations hours before mechanical breakdowns. Edge AI chipsets embedded in new sensors from Texas Instruments crunch local data streams so millisecond-level alerts can trigger automated responses without cloud latency. Interoperable protocols such as FOUNDATION Fieldbus and PROFINET simplify system integration, while ruggedized housings and extended temperature ranges ensure reliable service in dusty, high-vibration zones. As a result, the US temperature sensors market keeps enjoying replacement sales into heritage PLC networks and fresh demand from green-field smart factories.
Growing demand for temperature sensing in wearable consumer electronics
Miniaturized, low-power die have brought clinical-grade temperature accuracy into everyday devices, letting consumers track core body temperature within +-0.1 °C for early illness detection. Stretchable substrates now conform to skin for days without irritation, and dual-sensor ear-canal designs deliver continuous readings that fit into telehealth workflows. Fifth-generation cellular links and edge computing chips send encrypted streams to healthcare dashboards so clinicians can intervene remotely, a capability valued by aging-in-place programs. For sensor makers, these design wins offer high-volume consumer channels plus technology leverage across industrial IoT where power budgets are equally tight. The resulting pull keeps the US temperature sensors market on a steep innovation curve.
Volatility in semiconductor and platinum-group metal prices
Price swings in gallium, germanium, and platinum upset cost structures for RTDs and high-precision chip-based probes. China's command of gallium and germanium refining keeps US buyers vulnerable to export restrictions, while platinum thin films face supply tightness amid intensified fuel-cell and catalytic-converter demand. Budget uncertainty can delay upgrade projects, trimming near-term volumes inside the US temperature sensors market.
Other drivers and restraints analyzed in the detailed report include:
- Rising automotive electronics and EV thermal-management requirements
- Adoption of cold-chain IoT sensors for mRNA-vaccine logistics
- Cyber-security concerns over wireless sensors in critical infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wired devices retained 68.62% of 2025 revenue thanks to hard-wired reliability in safety-critical loops and existing DCS cabling, yet wireless nodes are scaling 10.22% CAGR on retrofit ease and lower installation costs. The US temperature sensors market size for wireless products is forecast to reach USD 1.09 billion by 2031, reflecting robust adoption in data centers and food plants. Self-powered harvesters developed at MIT remove battery maintenance barriers and widen use cases in pumps, kilns, and rotating equipment. In sprawling factories, LoRaWAN and 5G NB-IoT enable kilometer-scale reach with milliwatt power budgets, giving plant managers granular heat maps without trenching cable.
Reliability fears that once shadowed wireless have faded as frequency-hopping and AES-128 encryption become standard. Edge microcontrollers now pre-process readings to slash packet payloads, reducing congestion on factory backbones. Meanwhile, wired incumbency endures in nuclear, pharma, and aerospace lines where governance protocols require fixed cabling and analog outputs. Suppliers that bundle mixed-mode gateways bridging 4-20 mA loops with Wi-Fi or Sub-GHz radios capitalize on hybrid roll-outs and expand their stake in the US temperature sensors market.
Thermocouples brought in 31.95% of 2025 turnover by covering extreme heat up to 2,300 °C, but distributed fiber-optic systems are rocketing at 11.10% CAGR as industries crave spatial resolution over point checks. The US temperature sensors market size for DTS is projected to exceed USD 525.4 million by 2031. Immune to EMI, fiber lines navigate high-voltage bays and induction furnaces where electronics fail. High-definition units from Luna Innovations achieve sub-millimeter granularity, mapping battery modules and cryogenic pipelines alike.
Resistance Temperature Detectors still dominate pharma cleanrooms and metrology labs that stipulate +-0.1 °C accuracy. Thermistors capture cost-sensitive appliances, while infrared arrays unlock thermal imaging for predictive maintenance. Hybrid transmitters delivering HART, Modbus, or Ethernet protocols simplify integration into digital twins. Vendors that supply full stacks sensing element, head-mount transmitter, and analytics firmware bolster recurring revenue and deepen their position inside the US temperature sensors market.
Complete Report Scope:
- By Type
- Wired
- Wireless
- By Technology
- Infrared
- Thermocouple
- Resistance Temperature Detector (RTD)
- Thermistor
- Temperature Transmitter
- Fiber Optic
- Others
- By End-user Industry
- Chemical and Petrochemical
- Oil and Gas
- Metal and Mining
- Power Generation
- Food and Beverage
- Automotive
- Medical
- Aerospace and Military
- Consumer Electronics
- Other End-user Industries
- By Connectivity
- Contact
- Non-Contact
- By Application Environment
- Industrial Process Monitoring
- HVAC and Building Automation
- Healthcare and Wearables
- Electric-Vehicle Battery Management
- Data Centers and Telecom
List of Companies Covered in this Report:
- Texas Instruments Inc.
- Honeywell International Inc.
- TE Connectivity Ltd
- Analog Devices Inc.
- Siemens AG
- Panasonic Corp.
- ABB Ltd
- Emerson Electric Co.
- STMicroelectronics
- Microchip Technology Inc.
- NXP Semiconductors NV
- Robert Bosch GmbH
- DENSO Corp.
- FLIR Systems (Teledyne)
- Omron Corp.
- Maxim Integrated (ADI)
- Fluke Process Instruments
- Sensirion AG
- Amphenol Advanced Sensors
- Silixa Ltd
- AP Sensing GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Industry 4.0 and smart-factory adoption
- 4.2.2 Growing demand for temperature sensing in wearable consumer electronics
- 4.2.3 Rising automotive electronics and EV thermal-management requirements
- 4.2.4 Adoption of cold-chain IoT sensors for mRNA-vaccine logistics
- 4.2.5 Rapid growth of data-center liquid-cooling needs distributed sensing
- 4.2.6 Federal on-shoring incentives boosting in-fab thermal-process sensors
- 4.3 Market Restraints
- 4.3.1 Volatility in semiconductor and platinum-group metal prices
- 4.3.2 Lengthy design-in cycles slow sensor replacement in regulated sectors
- 4.3.3 Cyber-security concerns over wireless sensors in critical infrastructure
- 4.3.4 Shortage of fiber-optic installers curbs distributed sensing roll-out
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry Intensity
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Wired
- 5.1.2 Wireless
- 5.2 By Technology
- 5.2.1 Infrared
- 5.2.2 Thermocouple
- 5.2.3 Resistance Temperature Detector (RTD)
- 5.2.4 Thermistor
- 5.2.5 Temperature Transmitter
- 5.2.6 Fiber Optic
- 5.2.7 Others
- 5.3 By End-user Industry
- 5.3.1 Chemical and Petrochemical
- 5.3.2 Oil and Gas
- 5.3.3 Metal and Mining
- 5.3.4 Power Generation
- 5.3.5 Food and Beverage
- 5.3.6 Automotive
- 5.3.7 Medical
- 5.3.8 Aerospace and Military
- 5.3.9 Consumer Electronics
- 5.3.10 Other End-user Industries
- 5.4 By Connectivity
- 5.4.1 Contact
- 5.4.2 Non-Contact
- 5.5 By Application Environment
- 5.5.1 Industrial Process Monitoring
- 5.5.2 HVAC and Building Automation
- 5.5.3 Healthcare and Wearables
- 5.5.4 Electric-Vehicle Battery Management
- 5.5.5 Data Centers and Telecom
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Texas Instruments Inc.
- 6.4.2 Honeywell International Inc.
- 6.4.3 TE Connectivity Ltd
- 6.4.4 Analog Devices Inc.
- 6.4.5 Siemens AG
- 6.4.6 Panasonic Corp.
- 6.4.7 ABB Ltd
- 6.4.8 Emerson Electric Co.
- 6.4.9 STMicroelectronics
- 6.4.10 Microchip Technology Inc.
- 6.4.11 NXP Semiconductors NV
- 6.4.12 Robert Bosch GmbH
- 6.4.13 DENSO Corp.
- 6.4.14 FLIR Systems (Teledyne)
- 6.4.15 Omron Corp.
- 6.4.16 Maxim Integrated (ADI)
- 6.4.17 Fluke Process Instruments
- 6.4.18 Sensirion AG
- 6.4.19 Amphenol Advanced Sensors
- 6.4.20 Silixa Ltd
- 6.4.21 AP Sensing GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment