

|
시장보고서
상품코드
2121567
실리콘 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Silicone - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
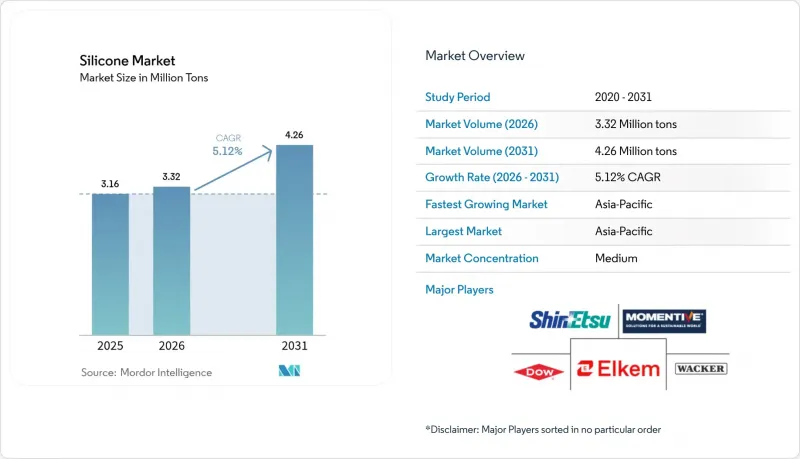
에 의하면, 2026년 실리콘 시장 규모는 332만 톤으로 추정되며, 2025년 316만 톤에서 2031년에는 426만 톤에 이를 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 5.12%를 기록할 전망입니다.
본 보고서는 형태별(유체, 엘라스토머, 수지, 기타), 용도별(운송, 건축자재, 전자, 헬스케어, 산업 공정, 퍼스널케어 및 소비재, 기타 용도), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 수량(톤) 기준으로 제시되어 있습니다.
세계 실리콘 시장 동향 및 인사이트
자동차 및 e-모빌리티 분야의 용도 확대
전기차(EV)의 보급으로 인해 기존 엘라스토머와의 성능 격차가 확대되면서 실리콘 사용량이 비약적으로 증가하고 있습니다. 배터리 팩의 씰, 열 간극 패드, 고전압 케이블의 절연재를 합치면 테슬라 ‘모델 Y’ 1대당 약 15kg의 실리콘이 사용되고 있으며, 이는 내연기관이 탑재된 세단의 약 3배에 해당합니다. 유럽의 각 OEM 업체들은 현재 150°C의 새로운 글리콜 프리 냉각수를 견뎌야 하는 보닛 내부 부품에 액상 실리콘 고무(LSR)를 채택하는 것을 선호하고 있습니다. 중국의 전기차 제조업체들은 금속 실리콘의 가격 변동을 완화하기 위해 고점도 고무와 부가 경화형 LSR의 이중 조달을 시작했으며, 이로 인해 통합 공급업체들은 장기 계약 체결을 촉진하고 있습니다. 엄격한 제로 배출 목표가 단계적으로 도입됨에 따라, 모든 주요 자동차 제조업체들이 개스킷, 포팅 및 인터페이스 소재의 재설계를 진행하고 있으며, 실리콘 업계 전반에 걸쳐 고급 제품에 대한 지속적인 수요가 발생하고 있습니다.
헬스케어 및 의료기기 분야에서의 활용 확대
의료용 실리콘은 USP 클래스 VI 및 ISO 10993 시험을 통과해야 합니다. 이 시험 프로토콜로 인해 신제품 로드맵이 최대 24개월까지 연장될 가능성이 있으며, 그 결과 기존 공급업체들은 단기적인 가격 변동으로 인한 압박으로부터 보호받고 있습니다. 웨어러블 혈당 모니터, 심장용 리드선, 신경 조절용 임플란트는 모두 LSR의 낮은 알레르기 유발성과 체온 하에서 안정적인 탄성 계수에 의존하고 있습니다. 병원에서는 감마선, 증기, 전자선 멸균법과의 적합성이 중시되고 있으며, 이는 저침습 기기에서 효율적인 재사용 전략을 뒷받침하고 있습니다. 의료의 디지털화, 특히 원격 모니터링의 보급으로 인해, 굴곡 수명을 저해하지 않으면서 광학 센서를 통합할 수 있는 반투명하고 광학적으로 투명한 실리콘 필름에 대한 OEM 수요가 증가하고 있습니다. 이러한 요인들이 결합되어, 헬스케어 분야는 실리콘 산업 내에서 수익성을 높이는 중요한 축으로서의 입지를 공고히 하고 있습니다.
실리콘 금속 가격 변동과 공급 병목 현상
2024년, 에너지 가격의 급등락과 무역 조치의 영향으로 실리콘 금속 현물 가격은 톤당 1,800-3,200달러 사이에서 변동하며, 통합형 제조업체와 무역사 계열 제조업체를 불문하고 각사의 이익률을 압박했습니다. 중국은 세계 생산량의 약 68%를 공급하고 있기 때문에 각 성에서 시행되는 전력 배급 제한은 하류 실리콘의 생산량과 가격에 즉각적인 파급 효과를 미칩니다. 장기 공급 계약은 어느 정도 보호 효과를 가져오지만, 대부분이 매년 갱신되기 때문에 구매자는 구조적인 에너지 비용 상승 위험에 계속 노출되어 있습니다. 반도체 절삭 부스러기 재활용 시험은 화학 등급 수요의 5% 미만을 충당할 뿐이어서, 미미한 완화 효과만 기대할 수 있습니다. 다각화된 저탄소 제련이 규모를 확대하기 전까지는 원자재 가격 변동이 실리콘 산업의 단기 전망에 어두운 그림자를 드리울 것입니다.
부문 분석
2025년 현재, 엘라스토머는 실리콘 시장 점유율의 49.35%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 5.33%를 나타낼 것으로 예측됩니다. 이 그룹 내에서 전기차용 커넥터 및 의료용 카테터용 액상 실리콘 고무(LSR)가 증가 톤수의 대부분을 차지하는 반면, 고점도 고무는 산업용 개스킷 분야에서 반복 주문을 확보하고 있습니다. LSR(액상 실리콘 고무)의 백금 경화 화학 반응은 사이클 타임을 단축하고, 대량 생산 부품에 대해 효율적으로 규모를 확대할 수 있는 다중 캐비티 금형의 사용을 가능하게 합니다. 한편, 실온 가황(RTV) 등급은 건설 및 리모델링 분야의 실란트 사업 기반을 강화하고 있으며, 거시적 사이클의 변동과 관계없이 안정적인 수요를 창출하고 있습니다. 이러한 특성을 종합해 볼 때, 엘라스토머는 실리콘 산업에서 매우 중요한 혁신의 거점이 되고 있습니다.
유체 제품은 공정 보조제, 윤활제, 퍼스널케어용 보습제로서의 역할을 바탕으로 생산량에서 2위를 차지하고 있습니다. 다가오는 실록산 규제가 범용 제품의 주기적인 변동에 과제를 안겨주고 있지만, 휘발성이 낮은 직쇄형 유체가 주목을 받으며 손실을 상쇄하는 데 기여하고 있습니다. 수지는 파워 일렉트로닉스 및 태양전지 패널의 보호용 캡슐 소재로서 틈새 시장을 중심으로 성장을 이어가고 있습니다. 이러한 분야에서는 열 안정성이 에폭시계 제품을 능가하고 있습니다. 젤, 폼, 분말과 같은 특수 형태의 제품이 포트폴리오를 풍부하게 하여, 첨단 섬유, 3D 프린팅용 수지 및 적층 성형용 바인더를 공급하고 있습니다. 각 분야의 경계가 모호해지고 있는 상황에서도, 이러한 누적적인 발전이 실리콘 시장 규모에 균형 잡힌 기여를 유지하고 있습니다.
지역별 분석
아시아태평양은 통합된 공급망과 활발한 하류 제조의 뒷받침을 받아 2025년에는 전 세계 실리콘 시장 점유율의 65.10%를 차지했습니다. 중국에는 현지 금속 실리콘 용광로와 엘라스토머 마감 공장을 결합한 완전한 후방 통합형 기업이 존재하여, 비용 경쟁력과 신속한 규모 확대를 실현하고 있습니다.
북미는 여전히 기술 최첨단을 달리고 있으며, 항공우주, 첨단 자동차 및 생의학 기기 제조업체들이 엄격한 재료 사양을 요구하고 있습니다. ‘CHIPS 법’은 국내 반도체 생산을 촉진하여 초저이온 오염 실리콘 봉지재에 대한 신규 수주를 유도하고 있습니다. 중서부 지역의 풍력 터빈 리파워링과 남서부 지역의 태양광 발전소 확장이 고내구성 실런트에 대한 수요를 뒷받침하고 있는 반면, 미국 식품의약국(FDA)의 LSR(연질 실리콘) 부품에 대한 예측 가능한 승인 절차가 의료 분야 수요를 견인하고 있습니다. 이러한 동향에 더해, 바이오 유래 실록산 전구체에 대한 활발한 연구가 더해지면서, 이 지역은 실리콘 산업의 혁신을 주도하는 역할을 확고히 하고 있습니다.
유럽은 특수 용도 및 규제 측면에서의 리더십을 통해 그 역할을 확고히 하고 있습니다. 각 제조업체는 사용 후 엘라스토머 잔여물을 환상 모노머로 변환하는 폐쇄형 탈중합 장치에 투자하고 있으며, 이는 EU의 순환 경제 비전에 부합하는 것입니다. 자동차 전동화 규제로 인해 고온·저블리드성 열전도 패드에 대한 수요가 활성화되고 있는 한편, 북해의 해상 풍력 발전소 건설 확대에 따라 나셀 밀봉용 견고한 수지가 요구되고 있습니다. REACH 규정 준수 의무로 인해 컴플라이언스 비용은 상승하지만, 동시에 직접적인 경쟁을 억제하는 장벽도 형성되어 유럽 실리콘 산업 전체의 부가가치 유지에 기여하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, silicone market size in 2026 is estimated at 3.32 million tons, growing from 2025 value of 3.16 million tons with 2031 projections showing 4.26 million tons, growing at 5.12% CAGR over 2026-2031.
This report is Segmented by Form (Fluids, Elastomers, Resins, and Others), Application (Transportation, Construction Materials, Electronics, Healthcare, Industrial Processes, Personal Care and Consumer Products, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Silicone Market Trends and Insights
Rising Applications in Automotive and E-mobility
Electric-vehicle (EV) adoption is multiplying the use of silicone by widening the performance gap versus traditional elastomers. Battery-pack sealing, thermal gap-pads, and high-voltage cable insulation collectively add close to 15 kg of silicone per Tesla Model Y, roughly triple that of an internal-combustion sedan. European OEMs now favor liquid-silicone rubber (LSR) for under-hood parts that must withstand new glycol-free coolants at 150 °C. Chinese EV makers have begun dual-sourcing high-consistency rubber and addition-cure LSR to buffer silicon-metal price swings, encouraging integrated suppliers to lock in long-term contracts. As stringent zero-emission targets phase in, every major automaker is redesigning gasketing, potting, and interface materials, creating an enduring pull for advanced grades across the silicone industry.
Increasing Usage in Healthcare and Medical Devices
Medical-grade silicones must clear USP Class VI and ISO 10993 testing, a protocol that can extend new-product roadmaps by up to 24 months, thereby shielding incumbent suppliers from short-cycle pricing pressure. Wearable glucose monitors, cardiac leads, and neuromodulation implants all hinge on LSR's hypoallergenic profile and stable modulus at body temperature. Hospitals value the polymer's sterilization compatibility with gamma, steam, and e-beam methods, which supports lean re-use strategies in minimally invasive tools. Digitization of care-particularly remote monitoring-has sparked OEM demand for translucent, optically clear silicone films that integrate optical sensors without compromising flex-life. Collectively, these factors cement healthcare as a margin-accretive pillar of the silicone industry.
Volatile Silicon-metal Prices and Supply Bottlenecks
Spot silicon-metal swung between USD 1,800-3,200/ton in 2024 on energy-price gyrations and trade measures, squeezing margin profiles across integrated and merchant producers alike. China supplies nearly 68% of global output, so provincial power rationing immediately reverberates through downstream silicone volumes and pricing. While long-term offtake contracts provide partial insulation, most renew annually, leaving buyers exposed to structural energy-cost inflation. Pilot recycling of semiconductor kerf scrap yields less than 5% of chemical-grade demand, offering only modest relief. Until diversified, low-carbon smelting gains scale, raw-material turbulence will shadow short-term forecasts for the silicone industry.
Other drivers and restraints analyzed in the detailed report include:
- Demand from Power Transmission and Distribution Grids
- 5G Base-station Thermal Interface Materials
- Stringent Siloxane Emission Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Elastomers controlled 49.35% of the silicone market share in 2025 and are forecast to grow at a 5.33% CAGR through 2031. Within this group, liquid-silicone rubber for EV connectors and medical catheters captures the lion's share of incremental tonnage, while high-consistency rubber secures repeat orders in industrial gasketing. LSR's platinum-cure chemistry shortens cycle times, allowing multi-cavity molds that scale efficiently for high-volume parts. Meanwhile, room-temperature-vulcanizing (RTV) grades strength-en sealant franchises in construction rehabilitation, feeding consistent demand regardless of macro-cycles. Collectively, these attributes make elastomers the pivotal innovation hub in the silicone industry.
Fluids rank second in volume, anchored by their role as process aids, lubricants, and personal-care emollients. Although impending siloxane limits challenge commodity cyclics, linear-chain fluids with lower volatility are gaining traction and help offset losses. Resins continue to deliver niche growth as protective encapsulants in power electronics and solar panels, where their thermal stability outperforms epoxy analogs. Specialty formats-gels, foams, and powders-round out the portfolio, supplying advanced textiles, 3-D printing resins, and additive-manufacturing binders. Even as boundaries blur, the cumulative developments sustain a balanced contribution to the silicone market size.
Complete Report Scope:
- By Form
- Fluids
- Elastomers
- Resins
- Others
- By Application
- Transportation
- Construction Materials
- Electronics
- Healthcare
- Industrial Processes
- Personal Care and Consumer Products
- Other Applications
- Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Thailand
- Malaysia
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Turkey
- Nordics
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Nigeria
- Egypt
- Qatar
- United Arab Emirates
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific wielded 65.10% of the global silicone market share in 2025, propelled by integrated supply chains and prolific downstream manufacturing. China features fully backward-integrated players that couple local silicon-metal furnaces to elastomer finishing plants, enabling cost competitiveness and rapid scale-up.
North America remains a technology vanguard, where aerospace, advanced automotive, and biomedical device makers impose stringent material specifications. The CHIPS Act catalyzes domestic semiconductor production, triggering new orders for ultra-low-ionic contamination silicone encapsulants. Wind-turbine repowering in the Midwest and solar-farm expansions in the Southwest anchor demand for high-durability sealants, while the U.S. Food and Drug Administration's predictable pathway for LSR components bolsters healthcare volumes. These trends, paired with active research into bio-based siloxane precursors, position the region as an innovation driver in the silicone industry.
Europe secures its role through specialty applications and regulatory leadership. Producers invest in closed-loop depolymerization units that convert spent elastomer scrap into cyclic monomers, aligning with the bloc's circular-economy vision. Automotive electrification mandates energize demand for high-temperature, low-bleed thermal pads, while offshore-wind build-outs in the North Sea necessitate robust resins for nacelle encapsulation. Although REACH obligations elevate compliance costs, they also create barriers that temper direct price competition, sustaining value density across the European silicone industry.
- BRB International (PETRONAS)
- CHT Germany GmbH
- DIC Corporation
- Dongyue Group
- Dow
- DyStar Singapore Pte Ltd
- Elkem ASA
- Evonik Industries AG
- Hoshine Silicon Industry Co., Ltd
- KANEKA Corporation
- KCC SILICONE CORPORATION
- Momentive
- Shin-Etsu Chemical Co. Ltd
- Siltech Corporation
- Wacker Chemie AG
- Wynca Tinyo Silicone Co., Ltd.
- Zhejiang Hengyecheng Organic Silicone Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising applications in automotive and e-mobility
- 4.2.2 Increasing usage in healthcare and medical devices
- 4.2.3 Demand from power transmission and distribution grids
- 4.2.4 5G base-station thermal interface materials
- 4.2.5 LSR adoption in wearable medical sensors
- 4.3 Market Restraints
- 4.3.1 Volatile silicon-metal prices and supply bottlenecks
- 4.3.2 Stringent siloxane emission regulations
- 4.3.3 Competition from fluoropolymers and thermoplastics
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Form
- 5.1.1 Fluids
- 5.1.2 Elastomers
- 5.1.3 Resins
- 5.1.4 Others
- 5.2 By Application
- 5.2.1 Transportation
- 5.2.2 Construction Materials
- 5.2.3 Electronics
- 5.2.4 Healthcare
- 5.2.5 Industrial Processes
- 5.2.6 Personal Care and Consumer Products
- 5.2.7 Other Applications
- 5.3 Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Thailand
- 5.3.1.6 Malaysia
- 5.3.1.7 Indonesia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Turkey
- 5.3.3.8 Nordics
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Nigeria
- 5.3.5.4 Egypt
- 5.3.5.5 Qatar
- 5.3.5.6 United Arab Emirates
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 BRB International (PETRONAS)
- 6.4.2 CHT Germany GmbH
- 6.4.3 DIC Corporation
- 6.4.4 Dongyue Group
- 6.4.5 Dow
- 6.4.6 DyStar Singapore Pte Ltd
- 6.4.7 Elkem ASA
- 6.4.8 Evonik Industries AG
- 6.4.9 Hoshine Silicon Industry Co., Ltd
- 6.4.10 KANEKA Corporation
- 6.4.11 KCC SILICONE CORPORATION
- 6.4.12 Momentive
- 6.4.13 Shin-Etsu Chemical Co. Ltd
- 6.4.14 Siltech Corporation
- 6.4.15 Wacker Chemie AG
- 6.4.16 Wynca Tinyo Silicone Co., Ltd.
- 6.4.17 Zhejiang Hengyecheng Organic Silicone Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet Need Assessment


