

|
시장보고서
상품코드
2121778
인도의 농업기계 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)India Agricultural Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
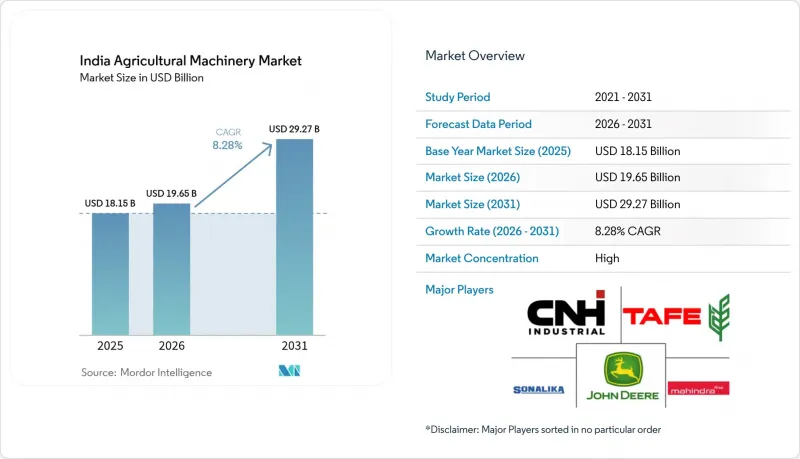
에 따르면 2026년 인도의 농업기계 시장 규모는 196억 5,000만 달러로 추정되고 있으며, 2025년 181억 5,000만 달러에서 확대하며, 2031년에는 292억 7,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지 연평균 성장률(CAGR) 8.28%로 성장할 것으로 전망됩니다.
이 보고서는 유형별(트랙터, 농업용 장비, 관개 기계, 수확 기계 등) 및 최종사용자 농장 규모별(소규모 농장, 중규모 농장 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도 농업기계 시장의 동향 및 인사이트
기계화 도입을 촉진하는 정부의 시책
SMAM(농업기계화 지원 계획)에 따른 정책 조치에 따라 개별 농업기계 구매시 40%-50%의 보조금이, 농업기계 대여 센터에는 최대 80%의 보조금이 지급되고 있습니다. 우타르 프라데시 주만 해도,SMAM은 2014-2024년 사이에 656억 6,000만 인도 루피(7억 9,000만 달러)를 지출하고, 17만 6,000대의 기계를 배포하며, 1만 769곳의 농기계 대여 센터를 설립했습니다. 이를 통해 소규모 농가 공동체 전체에서 고성능 농업기계에 대한 접근성이 확대되고 있습니다. ‘키산 드론’ 보조금이나 국가 식량안보 미션(National Food Security Mission) 하에서 시행되는 작물별 지원과 같은 보완적 조치들도 고정밀 농기계에 대한 수요를 더욱 높이고 있습니다. 이러한 프로그램들은 초기 비용을 최소화할 뿐만 아니라, 사후 서비스 체계를 강화함으로써 다양한 농업 기후대에 걸친 지속가능한 기계화를 촉진하고 있습니다.
도시로의 지속적인 인구 유출로 인한 농촌 지역의 노동력 부족
가구 조사 데이터에 따르면 주요 소득원인 사람들 중 농업에 계속 종사하고 있는 비율은 불과 9%에 불과하며, 이는 과거 50% 이상이던 수준에서 하락한 것입니다. 계절적인 인구 유출은 파종기와 수확기에 정점을 이루며 노동력 부족을 심화시키고 있지만, 기계화를 통해 적시에 경작, 파종, 수확이 가능해짐으로써 이러한 부족을 보완할 수 있습니다. 콤바인은 필요한 노동력을 최대 30% 절감하고 수확 후 손실을 2-4퍼센트 포인트 줄여주므로, 벼와 밀의 윤작에서 없어서는 안 될 존재가 되었습니다. 도급 센터를 통한 기계 공유를 통해 희소한 기계를 더욱 효율적으로 활용함으로써, 노동력 부족 지역에서도 재배 밀도를 유지할 수 있게 됩니다.
높은 장비 비용과 제한된 대출 접근성
넉넉한 보조금이 있음에도 불구하고 중형 트랙터를 구입하려면 여전히 60만 인도 루피(7,200달러)가 넘는 비용이 필요하며, 이 금액은 많은 소규모 농가에게는 감당하기 어려운 수준입니다. 정규 대출 기관은 담보를 요구하는 경우가 많으며, 금리 스프레드는 기준 금리보다 200-300 베이시스 포인트 높은 수준을 유지하고 있으며, 고액 투자를 가로막고 있습니다. 농기계 대여 센터는 비용 측면의 장벽을 완화해 주지만, 그 분포는 고르지 않습니다. 인도 동부에서는 지역당 12곳 미만인 반면, 북부 일부 지역에서는 45곳 이상으로, 지역 간 격차가 고착화되어 있습니다.
부문 분석
트랙터는 2025년에도 매출 점유율 40.12%를 유지하고 있으며, 다양한 작물 재배 체계에서 경작 및 운반에 있으며, 트랙터가 수행하는 기초적인 역할을 여실히 보여주고 있습니다. 관개 기계는 가장 빠르게 성장하는 부문이며, 미세 관개용 펌프와 점적 관개 시스템은 가뭄 대책 프로그램과 정밀한 관수에 유리한 전기 요금 인상의 지원을 받아 연평균 성장률(CAGR) 10.18%로 확대되고 있습니다. 쟁기, 해로우, 로토베이터 등의 농기구 부문은 소규모 농가에서의 기계화 추진의 혜택을 받고 있습니다. 이러한 농기구는 트랙터보다 적은 설비 투자로 도입할 수 있는 입문 수준의 기계화 솔루션을 제공합니다. 수확기는 성수기 노동력 부족이 심화되는 가운데 꾸준한 성장을 달성하고 있으며, 콤바인과 사료용 수확기는 상업 농업에서 작물을 적시에 수확하기 위해 필수적인 장비로 자리 잡았습니다.
세계의 위성항법시스템(GNSS)과 기존 농기계를 융합하는 어댑터를 통해 기존 트랙터는 ±2.5cm의 정밀도로 직선 경작 및 파종을 수행할 수 있는 스마트 기계로 변모하고 있으며, 투입 자재의 낭비를 6%-8% 줄이고 있습니다. 전동 보조식 로터베이터와 배터리 구동식 과수원용 분무기는 저소음과 무공해가 중시되는 과수 재배자들 사이에서 지지를 얻고 있습니다. 인도의 농업기계 시장은 밭태우기를 억제하기 위한 잔여물 관리 대책에서 베일러, 잔디 깎기 기계, 멀칭 기계의 중요성이 커짐에 따라 계속해서 다양화되고 있습니다. 시장을 선도하는 기업은 모듈식 부착물 생태계로 이에 대응하고 있으며, 트랙터 섀시 한 대로 20종 이상의 작업 특화형 농기구를 사용할 수 있으며, 소유 비용을 여러 수입원으로 분산시킬 수 있게 되었습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, India agricultural machinery market size market size in 2026 is estimated at USD 19.65 billion, growing from 2025 value of USD 18.15 billion with 2031 projections showing USD 29.27 billion, growing at 8.28% CAGR over 2026-2031.
This report is Segmented by Type (Tractors, Equipment, Irrigation Machinery, Harvesting Machinery, and More) and by End-User Farm Size (Smallholdings, Medium Farms, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Agricultural Machinery Market Trends and Insights
Government schemes boosting mechanization adoption
Policy interventions under SMAM provide 40%-50% subsidies on individual machinery purchases and up to 80% on custom-hiring centers. In Uttar Pradesh alone, SMAM disbursed INR 65.66 billion (USD 790 million) between 2014 and 2024, distributing 176,000 machines and establishing 10,769 custom-hiring centers, which collectively expand access to high-capacity equipment across smallholder communities. Complementary initiatives such as the Kisan Drone subsidy and crop-specific support under the National Food Security Mission channel further demand high-precision implements. These programs not only minimize upfront costs but also strengthen after-sales networks, thereby fostering sustained mechanization across diverse agro-climatic zones.
Rural labor shortage caused by sustained migration to urban centers
Household survey data indicate that only 9% of main income earners remain in farming, down from historic norms above 50%. Seasonal out-migration peaks during planting and harvesting, intensifying labor deficits that mechanization can bridge through timely tillage, sowing, and harvesting. Combine harvesters cut labor requirements by up to 30% and reduce post-harvest losses by 2-4 percentage points, making them indispensable in rice-wheat rotations. Equipment sharing through custom-hiring centers further leverages scarce machinery to maintain cropping intensities in labor-scarce districts.
High equipment cost and limited credit access
Despite generous subsidies, a mid-horsepower tractor still requires an outlay exceeding INR 600,000 (USD 7,200), a sum beyond the reach of many marginal growers. Formal lenders often demand collateral, and interest spreads remain 200-300 basis points above prime lending, deterring big-ticket investments. Custom-hiring centers cushion the cost hurdle but are unevenly distributed, eastern India hosts fewer than 12 centers per district versus 45-plus in parts of the north, perpetuating regional disparities.
Other drivers and restraints analyzed in the detailed report include:
- FPOs and contract farming aggregation
- Digital credit platforms enabling financing
- Fragmented landholdings limit scale efficiency
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tractors retained a 40.12% revenue share in 2025, underscoring their foundational role in tillage and haulage across diverse cropping systems. Irrigation Machinery is the fastest growing segment with micro-irrigation pumps and drip systems advancing at a 10.18% CAGR, propelled by drought-mitigation programs and rising electricity tariffs that favor precision watering. Equipment segments, including plows, harrows, and rotovators, benefit from the mechanization push in smallholder farming, where these implements provide entry-level mechanization solutions that require lower capital investment than tractors. Harvesting machinery experiences steady growth as labor shortages intensify during peak seasons, with combine harvesters and forage harvesters becoming essential for timely crop collection in commercial farming operations.
Adapters that merge global navigation satellite systems with traditional implements are converting conventional tractors into smart machines that execute straight-line plowing and seed placement within +-2.5 cm precision, reducing input waste by 6%-8%. Electric-assist rotovators and battery-powered orchard sprayers are gaining traction among fruit growers, where low noise and zero emissions are prized. The India agricultural machinery market continues to diversify as balers, mowers, and mulchers gain relevance in residue-management schemes aimed at curbing open-field burning. Market leaders respond with modular attachment ecosystems, allowing a single tractor chassis to support over 20 task-oriented implements, thereby spreading ownership cost over multiple revenue streams.
Complete Report Scope:
- By Type
- Tractors
- Less than 50 HP
- 50 to 75 HP
- 76 to 100 HP
- 101 to 150 HP
- Greater than 150 HP
- Equipment
- Plows
- Harrows
- Rotovators and Cultivators
- Seed and Fertilizer Drills
- Other Equipment (Post-Hole Diggers, Power Weeders, etc.)
- Irrigation Machinery
- Sprinkler Irrigation
- Drip Irrigation
- Other Irrigation Machinery (Center-Pivot Systems, Micro-Sprinklers, etc.)
- Harvesting Machinery
- Combine Harvesters
- Forage Harvesters
- Other Harvesting Machinery (Sugarcane Harvesters, Potato Harvesters, etc.)
- Haying and Forage Machinery
- Mowers and Conditioners
- Balers
- Other Haying and Forage Machinery (Tedders, Rakes, etc.)
- Tractors
- By End-User Farm Size
- Smallholdings (Less than 5 ha)
- Medium Farms (5 to 20 ha)
- Large Farms (Greater than 20 ha)
List of Companies Covered in this Report:
- Mahindra & Mahindra Ltd
- TAFE Motors and Tractors Limited
- Deere & Company
- CNH Industrial N.V.
- International Tractors Limited (Sonalika)
- Escorts Kubota Limited
- VST Tillers Tractors Ltd.
- AGCO Corporation
- CLAAS KGaA mbH
- Yanmar Holdings Co., Ltd.
- SDF Group S.p.A.
- Tirth Agro Technology Private Limited
- Kirloskar Group
- Jain Irrigation Systems Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Schemes Boosting Mechanization Adoption
- 4.2.2 Rural labor shortage caused by sustained migration to urban centers
- 4.2.3 FPOs and Contract Farming Aggregation
- 4.2.4 Digital Credit Platforms Enabling Financing
- 4.2.5 Electric Equipment Incentives Accelerating Adoption
- 4.2.6 Climate Insurance Favoring Mechanized Cultivation
- 4.3 Market Restraints
- 4.3.1 High Equipment Cost and Limited Credit Access
- 4.3.2 Fragmented Landholdings Limit Scale Efficiency
- 4.3.3 Emission Norms Vary Across States
- 4.3.4 Lack of Skilled Telematics Technicians
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Tractors
- 5.1.1.1 Less than 50 HP
- 5.1.1.2 50 to 75 HP
- 5.1.1.3 76 to 100 HP
- 5.1.1.4 101 to 150 HP
- 5.1.1.5 Greater than 150 HP
- 5.1.2 Equipment
- 5.1.2.1 Plows
- 5.1.2.2 Harrows
- 5.1.2.3 Rotovators and Cultivators
- 5.1.2.4 Seed and Fertilizer Drills
- 5.1.2.5 Other Equipment (Post-Hole Diggers, Power Weeders, etc.)
- 5.1.3 Irrigation Machinery
- 5.1.3.1 Sprinkler Irrigation
- 5.1.3.2 Drip Irrigation
- 5.1.3.3 Other Irrigation Machinery (Center-Pivot Systems, Micro-Sprinklers, etc.)
- 5.1.4 Harvesting Machinery
- 5.1.4.1 Combine Harvesters
- 5.1.4.2 Forage Harvesters
- 5.1.4.3 Other Harvesting Machinery (Sugarcane Harvesters, Potato Harvesters, etc.)
- 5.1.5 Haying and Forage Machinery
- 5.1.5.1 Mowers and Conditioners
- 5.1.5.2 Balers
- 5.1.5.3 Other Haying and Forage Machinery (Tedders, Rakes, etc.)
- 5.1.1 Tractors
- 5.2 By End-User Farm Size
- 5.2.1 Smallholdings (Less than 5 ha)
- 5.2.2 Medium Farms (5 to 20 ha)
- 5.2.3 Large Farms (Greater than 20 ha)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Mahindra & Mahindra Ltd
- 6.4.2 TAFE Motors and Tractors Limited
- 6.4.3 Deere & Company
- 6.4.4 CNH Industrial N.V.
- 6.4.5 International Tractors Limited (Sonalika)
- 6.4.6 Escorts Kubota Limited
- 6.4.7 VST Tillers Tractors Ltd.
- 6.4.8 AGCO Corporation
- 6.4.9 CLAAS KGaA mbH
- 6.4.10 Yanmar Holdings Co., Ltd.
- 6.4.11 SDF Group S.p.A.
- 6.4.12 Tirth Agro Technology Private Limited
- 6.4.13 Kirloskar Group
- 6.4.14 Jain Irrigation Systems Ltd.


