|
시장보고서
상품코드
2122756
베트남의 농업기계 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vietnam Agricultural Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 베트남의 농업기계 시장 규모는 2025년에 5억 6,461만 달러로 평가되었고, 2026년 6억 121만 달러에서 2031년까지 8억 4,234만 달러로 확대될 전망이며, 예측 기간(2026-2031년) CAGR은 6.98%로 성장할 것으로 추정되고 있습니다.
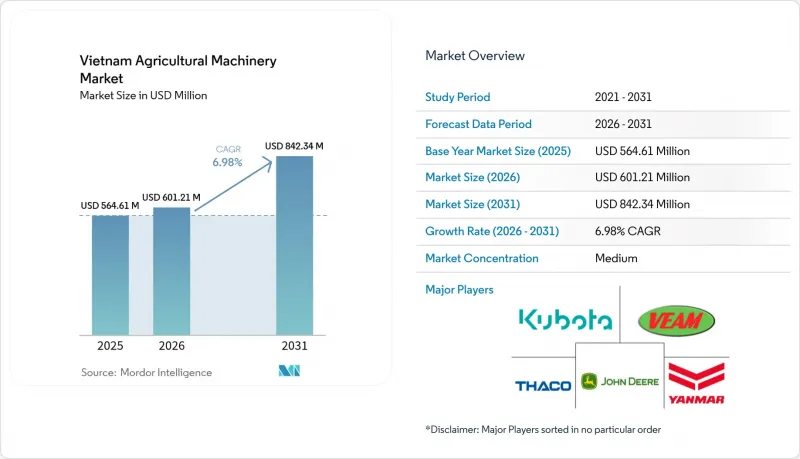
본 보고서는 제품 유형별(트랙터, 식재·파종 기계, 수확 기계, 살포·드론, 건초·사료용 기계, 기타 제품 유형) 및 서비스 모델별(소유자 운영, 도급·렌탈 서비스)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 제시되어 있습니다.
베트남의 농업기계 시장 동향 및 인사이트
농업 노동력 감소
2025년, 베트남의 농업 종사자는 농촌 노동력의 51.94%를 차지했으며, 이는 이전 기준치보다 4.3% 감소한 수치입니다. 메콩 델타 지역에서는 가장 급격한 감소가 나타났습니다. 인구 유출, 기후 변화의 영향, 그리고 농가의 고령화로 인해 생산자들은 수작업을 기계로 대체할 수밖에 없지만, GPS 유도식 콤바인을 조작할 수 있는 숙련된 운전자공급은 점점 부족해지고 있습니다. 수확기에는 현재 도급 서비스가 주류를 이루고 있지만, 성수기에는 조작자 임금이 급등하기 때문에 자율형 및 반자율형 농업기계에 대한 관심이 높아지고 있습니다. 쿠보타가 2025년 1월에 발행한 기술 보고서에서는 몬순 기후에 맞춘 논에서의 자동화에 관한 조사가 확인되었습니다. 인건비 상승이 지속되는 가운데, 기계화는 단순한 선택지가 아니라 생존을 위한 전략이 되어가고 있습니다.
정부 보조금이 포함된 기계화 대출 한도 확대
2024년 7월 은행 통지에 따라 농업기계용 금융 리스가 허용되었으며, 이는 2024년 말 기준 730조 베트남 동(약 295억 달러)에 달한 그린 크레딧 포트폴리오를 보완하는 형태가 되었습니다. 그 후, 칸토, 안잔, 동탑 각 성에서는 모내기 기계나 정밀 파종기 비용의 최대 절반을 지원하는 보조금이 도입되었습니다. 세계은행의 역량 개발 프로젝트는 밸류체인 내의 민관 파트너십을 정착시킴으로써 대출 기관의 위험을 더욱 낮추고 있습니다. 카마우성의 빈 콴과 같은 협동조합 모델의 경우, 융자 한도를 통해 농업기계 도입 규모를 신속하게 확대할 수 있어 헥타르당 비용을 6-8달러 절감할 수 있었습니다고 보고되고 있습니다. 수입품보다 10%-20% 저렴한 가격을 책정하고 있는 국내 조립 제조업체들은 보조금 덕분에 그 저렴한 가격이 소규모 농가에게 더욱 매력적으로 다가오게 되어 현저히 큰 혜택을 보고 있습니다.
극도로 세분화된 농지 규모
베트남에는 수많은 구획으로 분산된 농장이 많으며, 평균 농장 면적은 1헥타르 미만입니다. 그중에서도 대다수는 소규모 구획으로 운영되고 있습니다. 이러한 현저한 세분화는 규모의 경제를 제한하고 있으며, 콤바인 등의 농기계를 소규모 구획까지 운반해야 하기 때문에 효율성 향상이 저해됩니다. 게다가 불규칙한 모양의 밭과 좁은 통로는 대형 농업기계의 사용을 방해하고 있습니다. 토지법은 토지 통합에 제한을 두고 있어, 메콩 델타 및 기타 지역의 농지 소유를 제한하고 있습니다. 초소형 농업기계가 개발되거나 토지 소유권에 관한 규제가 개정되지 않는 한, 이러한 구조적 제약이 베트남 농업기계 시장의 성장을 계속해서 저해할 것으로 예측됩니다.
부문 분석
2025년, 트랙터는 베트남 농업기계 시장 점유율의 42.3%를 차지했으며, 이는 770만 헥타르에 달하는 논에서 경운 작업에 트랙터가 중심적인 역할을 하고 있음을 반영합니다. 35마력 미만의 사륜구동 모델이 주류를 이루는 이유는 좁은 제방이나 논을 주행할 수 있기 때문입니다. 베트남 트랙터 시장은 초기 비용을 절감하는 대출 한도 확대와 가격을 낮추는 현지 생산의 진전에 따라 성장이 예상됩니다. 쿠보타 주식회사와 얀마 홀딩스는 노동력 부족을 보완하기 위해 자율 주행 기능을 갖춘 20-40마력 모델의 개량을 추진하고 있는 반면, 국내 조립 제조업체들은 1만 달러 미만의 가격대 제품에 주력하고 있습니다. 이륜 트랙터에서 갈아타는 농가들은 운송 수단으로도 겸용할 수 있는 컴팩트한 사륜 모델을 선호하는 경향이 있어, 이에 따라 대상 고객층이 확대되고 있습니다.
살포기나 드론은 현재 매출에서 차지하는 비중이 한 자릿수 중반에 그치고 있지만, 2031년까지 연평균 성장률(CAGR) 7.8%로 가장 빠른 성장을 이룰 것으로 전망됩니다. 수작업 살포와 동등한 단가와 최대 75%의 인력 감축이 이러한 성장의 원동력이 되고 있습니다. 베트남 농업기계 시장에서 드론 시장 규모는 면허 제도를 통해 안전 기준이 표준화되고 보험 적용이 가능해지면 더욱 가속화될 가능성이 있습니다. 등록 대수는 이미 2,800대를 넘어섰으며, Real-time Robotics사는 수입품보다 20%-30% 저렴한 가격을 책정하고 있습니다. 드론은 작물의 실시간 이미지를 촬영할 수 있어 탄소 크레딧 검증에도 활용될 수 있으며, 도입 기업에 새로운 수익원을 제공합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the Vietnam agricultural machinery market size was valued at USD 564.61 million in 2025 and is estimated to grow from USD 601.21 million in 2026 to USD 842.34 million by 2031, at a CAGR of 6.98% during the forecast period (2026-2031).
This report is Segmented by Product Type (Tractors, Planting and Seeding Machinery, Harvesting Machinery, Spraying and Drones, Haying and Forage Machinery, and Other Product Types), and by Service Model (Owner-Operated Machines and Custom-Hiring and Rental Services). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Agricultural Machinery Market Trends and Insights
Shrinking Agricultural Labor Pool
In 2025, the agricultural workforce in Vietnam accounted for 51.94% of the rural labor force, a 4.3% decrease from earlier benchmarks. The Mekong Delta witnessed the sharpest decline. Out-migration, climate shocks, and an aging farmer base are forcing growers to replace manual labor with machinery, yet the pool of skilled operators able to handle Global Positioning System-guided combines is tightening. Custom-hiring services now dominate harvest windows, but operator wages spike during peak periods, pushing interest in autonomous and semi-autonomous equipment. Kubota's January 2025 technical bulletin confirms research on wet-field automation tailored for monsoon conditions. As labor costs keep rising, mechanization becomes less an option and more a survival strategy.
Expansion of Government-Subsidized Mechanization Credit Lines
The July 2024 banking circular opened financial leasing for agricultural machinery, complementing a green credit portfolio that reached 730 trillion Vietnamese dong (approximately USD 29.5 billion) by late 2024. Provincial programs in Can Tho, An Giang, and Dong Thap then layered subsidies covering up to half the cost of transplanters and precision seeders. World Bank capacity-building projects further reduce lenders' risk by anchoring public-private partnerships in value chains. Cooperative models, such as Vinh Cuong in Ca Mau, report per-hectare cost savings of USD 6 to USD 8 because the credit pipeline lets them scale fleets quickly. Domestic assemblers, pricing 10% to 20% below imports, benefit disproportionately because subsidies make their lower ticket prices even more attractive to smallholders.
Highly Fragmented Farm Sizes
Vietnam has many farms spread across numerous parcels, with an average farm size of less than one hectare. Among these, the majority operate on small plots. This significant fragmentation limits economies of scale, as transporting machinery like combine harvesters to small plots diminishes efficiency gains. Additionally, irregularly shaped fields and narrow paths hinder the use of larger agricultural implements. Land laws impose restrictions on consolidation, limiting holdings in the Mekong Delta and other regions. Unless ultra-compact machinery is developed or land tenure regulations are revised, this structural limitation is projected to continue hindering the growth of the Vietnam agricultural machinery market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Rice-Export Cashflows Funding Machine Upgrades
- On-Farm Data Monetization Platforms Boosting Telematics Demand
- Rising Cyber-Security Threats to Connected Machinery
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tractors held 42.3% of the Vietnam agricultural machinery market share in 2025, reflecting their central role in tillage across 7.7 million hectares of paddy. Sub-35-horsepower four-wheel-drive units dominate because they navigate narrow bunds and wet fields. The Vietnam agricultural machinery market for tractors is projected to grow in step with credit lines that cut upfront costs and localization that trims prices. Kubota Corporation and Yanmar Holdings Co., Ltd. are refining 20-40 horsepower models with autonomous features to bridge the labor gap, while domestic assemblers are chasing the sub-USD 10,000 tier. Farmers replacing two-wheel units favor compact four-wheel models that can double as transport, widening the addressable base.
Spraying and drones, though only a mid-single-digit slice of revenue today, will post the fastest growth at a 7.8% CAGR to 2031. Unit cost parity with manual spraying and up to 75% labor savings underpin that expansion. The Vietnam agricultural machinery market size for drones could accelerate further if pilot-licensing rules standardize safety and unlock insurance coverage. Registrations already top 2,800 units, and Real-time Robotics undercuts imports by 20%-30%. Because drones capture real-time crop imagery, they dovetail with carbon-credit verification, giving adopters a second revenue stream.
Complete Report Scope:
- By Product Type
- Tractors
- By Engine Power
- Less than 15 HP
- 15 to 30 HP
- 31 to 45 HP
- 46-75 HP
- More than 75 HP
- By Drive Type
- Two-Wheel Drive
- Four-Wheel Drive
- By Engine Power
- Harvesting Machinery
- Planting and Seeding Machinery
- Spraying and Drones
- Haying and Forage Machinery
- Other Product Types
- Tractors
- By Service Model
- Owner-Operated Machines
- Custom-Hiring and Rental Services
List of Companies Covered in this Report:
- Kubota Corporation
- Yanmar Holdings Co., Ltd.
- Vietnam Engine and Agricultural Machinery Corp (VEAM)
- Truong Hai Group Corporation (THACO)
- Deere & Company (TTC Bien Hoa)
- Mahindra & Mahindra Ltd.
- Yamabiko Corporation
- LS Mtron Co., Ltd. (LS Group)
- Zetor Tractors a.s. (HTC Investments)
- Zoomlion Heavy Industry Science and Technology Co., Ltd.
- Netafim Ltd. (Orbia Group)
- Vermeer Manufacturing Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shrinking agricultural labor pool
- 4.2.2 Expansion of government-subsidized mechanization credit lines
- 4.2.3 Surge in rice-export cashflows funding machine upgrades
- 4.2.4 Rapid drop in drone-spraying service costs
- 4.2.5 Domestic original equipment manufacturer localization drive
- 4.2.6 On-farm data monetization platforms boosting telematics demand
- 4.3 Market Restraints
- 4.3.1 Highly fragmented farm sizes
- 4.3.2 Low rural electrification hindering electric tractors
- 4.3.3 Rising cyber-security threats to connected machinery
- 4.3.4 Skilled-operator shortage inflating service costs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Tractors
- 5.1.1.1 By Engine Power
- 5.1.1.1.1 Less than 15 HP
- 5.1.1.1.2 15 to 30 HP
- 5.1.1.1.3 31 to 45 HP
- 5.1.1.1.4 46-75 HP
- 5.1.1.1.5 More than 75 HP
- 5.1.1.2 By Drive Type
- 5.1.1.2.1 Two-Wheel Drive
- 5.1.1.2.2 Four-Wheel Drive
- 5.1.1.1 By Engine Power
- 5.1.2 Harvesting Machinery
- 5.1.3 Planting and Seeding Machinery
- 5.1.4 Spraying and Drones
- 5.1.5 Haying and Forage Machinery
- 5.1.6 Other Product Types
- 5.1.1 Tractors
- 5.2 By Service Model
- 5.2.1 Owner-Operated Machines
- 5.2.2 Custom-Hiring and Rental Services
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Kubota Corporation
- 6.4.2 Yanmar Holdings Co., Ltd.
- 6.4.3 Vietnam Engine and Agricultural Machinery Corp (VEAM)
- 6.4.4 Truong Hai Group Corporation (THACO)
- 6.4.5 Deere & Company (TTC Bien Hoa)
- 6.4.6 Mahindra & Mahindra Ltd.
- 6.4.7 Yamabiko Corporation
- 6.4.8 LS Mtron Co., Ltd. (LS Group)
- 6.4.9 Zetor Tractors a.s. (HTC Investments)
- 6.4.10 Zoomlion Heavy Industry Science and Technology Co., Ltd.
- 6.4.11 Netafim Ltd. (Orbia Group)
- 6.4.12 Vermeer Manufacturing Co.