|
시장보고서
상품코드
2121941
아프리카의 자동차 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Africa Automotive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
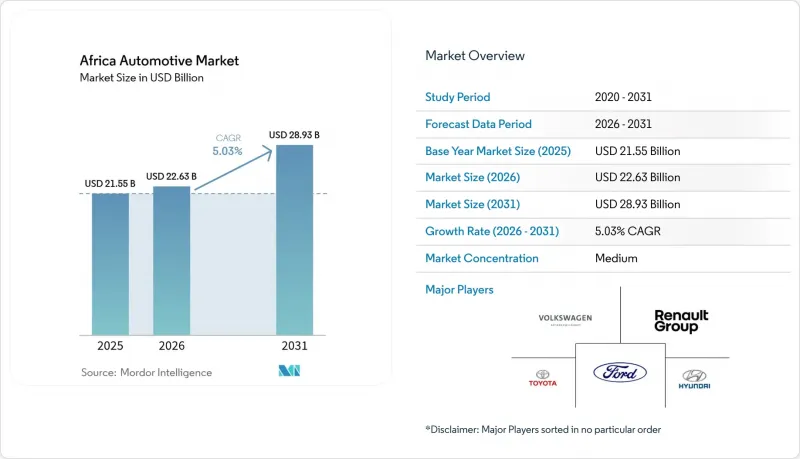
에 따르면 2026년 아프리카의 자동차 시장의 규모는 226억 3,000만 달러로 추정되고 있으며, 2025년 215억 5,000만 달러에서 확대하며, 2031년에는 289억 3,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지 연평균 성장률(CAGR) 5.03%로 성장할 것으로 전망됩니다.
이 보고서는 차종(승용차, 상용차), 구동 방식(내연기관(ICE) 등), 용도(개인, 플릿 및 리스 등), 판매 채널(CBU, SKD/CKD 등),국가(남아프리카, 모로코, 알제리, 이집트, 나이지리아, 가나, 케냐, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
아프리카 자동차 시장의 동향 및 인사이트
아프리카 도시 중산층의 승용차 보유 대수 증가
자동차 보유율은 소득 증가와 밀접한 관련이 있으며, 아프리카 중산층은 2060년까지 11억 명에 달할 것으로 예측됩니다. 이에 따라 개인 이동 수단에 대한 수요가 점차 증가하고 있습니다. 구매 의향이 높은 계층은 합리적인 가격과 도시 지역에서의 실용성을 모두 갖춘 엔트리 레벨 및 소형 승용차 모델에 매력을 느끼고 있습니다. 장기 자동차 대출이나 구독 모델과 같은 금융 분야의 혁신으로 인해 구매 편의성이 향상되었으며, 이는 아프리카 자동차 시장 전체의 수요 상승 사이클을 더욱 강화하고 있습니다.
AfCFTA의 관세 인하가 역내 무역을 활성화
아프리카 대륙 자유무역지대(AfCFTA)에서는 상품의 90%에 대한 관세가 단계적으로 철폐되며, 최빈개도국(LDC)을 제외한 대부분의 국가는 5년 이내에 달할 준수해야 합니다. 자동차 제조사들은 지역내 부품 조달을 통해 투입 비용을 절감할 수 있을 것으로 예상되는 한편, 명확한 원산지 규정에 따라 특혜 관세 적용이 가능한 현지 부가가치 창출이 촉진될 것입니다. 이미 46개국이 양허표를 제출했으며, 무역 자유화가 CKD 사업에서의 구체적인 비용 절감으로 이어지고 있습니다. 비관세 장벽 개혁(세관 업무의 디지털화, 규격 조화, 국경 절차 간소화)을 통해 추가로 200억 달러 규모의 무역 가치가 창출될 것으로 예상되며, 이는 아프리카 자동차 시장에 직접적인 혜택이 될 것입니다.
만성적인 항만 혼잡과 내륙 물류의 병목 현상
더반항과 라고스항은 자동차 처리량 측면에서 세계에서 가장 처리 속도가 느린 항만으로 꼽히며, 체류 시간과 체선료의 증가를 초래하고 있습니다. 철도 이용률이 낮고 차량 노후화가 진행되고 있으며, 운송이 도로로 전환되고 있지만, 고액의 통행료와 보안 위험으로 인해 차량의 도착 비용이 상승하고 있습니다. CKD(완전 분해 키트) 조립업체의 경우, 부품 도착이 불안정하여 적시 생산(JIT)에 차질이 생기고, 수출업체의 경우 출하 시기를 놓침으로써 공급업체에 대한 신뢰도가 떨어지고 있습니다. 현재 진행 중인 회랑 정비나 원스톱 통관 시스템이 눈에 띄는 효율성을 가져오지 않는 한, 물류상의 마찰은 아프리카 자동차 시장에 계속해서 걸림돌이 될 것입니다.
부문 분석
2025년, 아프리카 자동차 시장은 승용차가 66.58%의 점유율을 차지하며 주도하고 있으며, 이는 광대한 도시권에서 개인 이동 수단의 매력이 반영된 결과입니다. 그러나 아프리카 대륙 자유무역협정(AfCFTA)에 따른 화물 운송의 성장과 E-Commerce의 급속한 확대로 인해 관심은 밴, 픽업트럭, 대형 트럭으로 옮겨가고 있으며, 이러한 차종은 연평균 성장률(CAGR) 8.36%를 기록하며 승용차 모델을 앞지를 것으로 예측됩니다. 소형 상용차는 라스트 마일 화물 운송량 증가의 혜택을 누리고 있는 반면, 중형 및 대형 트럭은 조화로운 통관 회랑을 통해 지역 간 거래되는 화물을 운송하고 있습니다. 광업 기업은 배터리식 전기 덤프트럭을 신속하게 시범 도입하고 있으며, 이는 대형 차량 플리트에서 향후 대체 기회가 있을 것임을 시사합니다.
상용차 조립 제조사들은 섀시 및 구동계 수입 관세를 면제해 주는 정부의 우대 조치를 활용하여, 그레이 마켓의 중고 수입차와의 가격 격차를 좁히고 있습니다. 전 세계 생산 거점의 재배치도 중요한 요소입니다. 모로코는 2024년에 61만 4,000대를 생산하며 남아프리카공화국을 추월했습니다. 이를 통해 화물 운송 플랫폼으로 전환 가능한 견고한 공급업체 기반이 형성되고 있습니다. 물류 사업자들이 사업을 정식화함에 따라 차량 교체 주기가 단축되고 있으며, 아프리카 자동차 시장의 이 부문에서 성장세가 유지되고 있습니다.
2025년에도 내연기관 차량은 90.68%의 점유율을 유지하고 있으며, 이는 저렴한 연료 가격과 정비 체계가 잘 갖춰져 있음을 지원합니다. 그러나 중국 제조사의 신차 출시와 르완다, 케냐, 이집트의 재정적 인센티브를 배경으로 배터리식 전기자동차는 연평균 성장률(CAGR) 10.12%를 기록할 것으로 예측됩니다. 일본에서 수입되는 하이브리드 중고차는 소비자들이 전기 구동 시스템에 조기에 익숙해질 수 있는 계기가 되고 있는 반면, 전기자동차 부품에 대한 관세 면제는 상용차 차량군의 총 소유 비용을 절감시키고 있습니다.
송전망의 안정성에 대한 제약으로 인해 주요 대도시권 이외 지역에서의 보급은 둔화되고 있지만, 구리 벨트 지역의 광산에서는 전기 픽업 트럭에 전력을 공급하기 위해 오프그리드 태양광·배터리 허브가 도입되고 있습니다. 앞으로 배터리 비용의 하락과 충전 인프라 확충에 힘입어 도입 곡선이 더욱 가팔라지면서, 아프리카 자동차 시장에서 내연기관(ICE)의 우위가 점차 약화될 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모, 성장 예측 및 거래액(2019-2030년)
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, Africa automotive market size in 2026 is estimated at USD 22.63 billion, growing from 2025 value of USD 21.55 billion with 2031 projections showing USD 28.93 billion, growing at 5.03% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Passenger Cars and Commercial Vehicles), Propulsion Type (ICE, and More), End-Use (Personal, Fleet and Leasing, and More), Sales Channel (CBU, SKD/CKD, and More), and by Country (South Africa, Morocco, Algeria, Egypt, Nigeria, Ghana, Kenya, Rest of Africa). Market Forecasts are Provided in Terms of Value (USD) and Volume in (Units).
Africa Automotive Market Trends and Insights
Rising Passenger-Car Ownership Among Africa's Urban Middle Class
Vehicle ownership closely tracks income gains, and Africa's middle class is projected to swell toward 1.1 billion people by 2060. Driving incremental demand for personal mobility. Aspirational buyers gravitate toward entry-level and compact passenger models that balance affordability with urban practicality. Financing innovations such as longer-tenor auto loans and subscription models improve affordability, reinforcing the upward demand cycle across the Africa automotive market.
AfCFTA Tariff Reductions Stimulating Intra-Regional Trade
The African Continental Free Trade Area (AfCFTA) will phase out tariffs on 90% of goods, with most non-LDC nations obliged to comply within five years. Automotive OEMs stand to gain lower input costs on regional parts procurement, while clear rules of origin encourage local value addition that unlocks preferential tariffs. Forty-six countries have already submitted concession schedules, translating trade liberalization into tangible cost relief for CKD operations. Non-tariff barrier reforms-customs digitization, harmonized standards, and streamlined border procedures-are expected to release an extra USD 20 billion in trade value, a direct boon for the Africa automotive market.
Chronic Port Congestion and Inland Logistics Bottlenecks
Durban and Lagos ports rank among the world's slowest for automotive throughput, inflating dwell times and demurrage fees. Rail under-utilization and aging rolling stock shift traffic onto roads where high tolls and security risks push up landed vehicle costs. For CKD assemblers, inconsistent component arrivals disrupt just-in-time production, while exporters face missed sailing windows that erode supplier credibility. Unless ongoing corridor upgrades and single-window customs systems deliver measurable efficiencies, logistics friction will remain a drag on the Africa automotive market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Ride-Hailing and Last-Mile Delivery Fleets
- Mining-Sector EV Pilot Programs in Copper-Belt Nations
- Currency Volatility Elevating Import Costs for CKD Kits
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars dominated the Africa automotive market with a 66.58% share in 2025, reflecting personal mobility's appeal across sprawling urban centers. However, freight growth under AfCFTA and booming e-commerce pivot attention toward vans, pickups, and heavy trucks that are forecast to outpace passenger models at an 8.36% CAGR. Light commercial vehicles benefit from last-mile parcel volumes, whereas medium and heavy trucks haul regionally traded goods under harmonized customs corridors. Mining firms quickly test battery-electric dumpers, signaling future substitution opportunities in heavy-duty fleets.
Commercial vehicle assemblers leverage government incentives that waive import duties on chassis and drivetrains, narrowing price gaps versus grey-market used imports. Global production reallocations also matter: Morocco surpassed South Africa in 2024 with 614,000 units, creating a deep supplier base that can pivot toward freight platforms. As logistics players formalize operations, fleet replenishment cycles shorten, sustaining momentum in this segment of the Africa automotive market.
Internal combustion engines retained a 90.68% share in 2025, underscoring affordable fuel and servicing ecosystems. Nevertheless, battery electrics are projected to post a 10.12% CAGR on the back of Chinese OEM launches and fiscal incentives in Rwanda, Kenya, and Egypt. Pre-owned hybrid imports from Japan seed early consumer familiarity with electrified drivetrains, while duty exemptions on EV components lower the total cost of ownership for commercial fleets.
Grid stability constraints slow rollout outside major metros, yet copper-belt mining sites deploy off-grid solar-battery hubs to power electric pickups. Over time, diminishing battery costs and wider charging corridors could unlock a steeper adoption curve, gradually trimming ICE dominance in the African automotive market.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Hatchback
- Sedan
- SUV & Crossover
- MPV & Others
- Commercial Vehicles
- Light Commercial Vehicles (LCV)
- Medium & Heavy Trucks
- Buses & Coaches
- Passenger Cars
- By Propulsion Type
- Internal Combustion Engine (ICE)
- Hybrid Electric Vehicle (HEV)
- Battery Electric Vehicle (BEV)
- Alternative Fuels (CNG/LPG, Flex-fuel, FCEV)
- By End-Use
- Personal Ownership
- Fleet & Leasing
- Ride-hailing / Mobility Service Providers
- Government & Institutional
- By Sales Channel
- Completely Built-up Imports (CBU)
- Semi/Completely Knocked-down Assembly (SKD/CKD)
- Used-Vehicle Imports
- By Country
- South Africa
- Morocco
- Algeria
- Egypt
- Nigeria
- Ghana
- Kenya
- Rest of Africa
List of Companies Covered in this Report:
- Toyota Motor Corporation
- Volkswagen AG
- Groupe Renault
- Hyundai Motor Company
- Ford Motor Company
- Daimler Truck AG
- Volvo Group
- Isuzu Motors Ltd
- Tata Motors Ltd
- Ashok Leyland
- Innoson Vehicle Manufacturing Co.
- Stellantis (Peugeot, Opel)
- Nissan Motor Co.
- Kia Corporation
- BAIC Group
- Chery Automobile Co.
- BYD Auto
- Geely Automobile Holdings
- Great Wall Motor (Haval)
- Guangzhou Automobile Group (GAC)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Passenger-Car Ownership Among Africa's Urban Middle Class
- 4.2.2 Growing Chinese OEM CKD/SKD Investments (E.G., BYD, Chery)
- 4.2.3 AFCFTA Tariff Reductions Stimulating Intra-Regional Trade
- 4.2.4 Expansion of Ride-Hailing and Last-Mile Delivery Fleets
- 4.2.5 Surge in Diaspora-Financed Vehicle Purchases Via Fintech Remittance Platforms
- 4.2.6 Mining-Sector EV Pilot Programs in Copper-Belt Nations Driving Demand for Electric Pickups
- 4.3 Market Restraints
- 4.3.1 Chronic Port Congestion and Inland Logistics Bottlenecks
- 4.3.2 Currency Volatility Elevating Import Costs for CKD Kits
- 4.3.3 Grey-Market Used-Vehicle Influx Curbing New-Car Demand
- 4.3.4 Shortage Of ISO-Certified Auto-Grade Steel Rolling Capacity in West Africa
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (ICE, Hybrid, BEV, FCEV)
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value in (USD) and Volume in (Units), 2019-2030)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.1.1 Hatchback
- 5.1.1.2 Sedan
- 5.1.1.3 SUV & Crossover
- 5.1.1.4 MPV & Others
- 5.1.2 Commercial Vehicles
- 5.1.2.1 Light Commercial Vehicles (LCV)
- 5.1.2.2 Medium & Heavy Trucks
- 5.1.2.3 Buses & Coaches
- 5.1.1 Passenger Cars
- 5.2 By Propulsion Type
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Hybrid Electric Vehicle (HEV)
- 5.2.3 Battery Electric Vehicle (BEV)
- 5.2.4 Alternative Fuels (CNG/LPG, Flex-fuel, FCEV)
- 5.3 By End-Use
- 5.3.1 Personal Ownership
- 5.3.2 Fleet & Leasing
- 5.3.3 Ride-hailing / Mobility Service Providers
- 5.3.4 Government & Institutional
- 5.4 By Sales Channel
- 5.4.1 Completely Built-up Imports (CBU)
- 5.4.2 Semi/Completely Knocked-down Assembly (SKD/CKD)
- 5.4.3 Used-Vehicle Imports
- 5.5 By Country
- 5.5.1 South Africa
- 5.5.2 Morocco
- 5.5.3 Algeria
- 5.5.4 Egypt
- 5.5.5 Nigeria
- 5.5.6 Ghana
- 5.5.7 Kenya
- 5.5.8 Rest of Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Toyota Motor Corporation
- 6.4.2 Volkswagen AG
- 6.4.3 Groupe Renault
- 6.4.4 Hyundai Motor Company
- 6.4.5 Ford Motor Company
- 6.4.6 Daimler Truck AG
- 6.4.7 Volvo Group
- 6.4.8 Isuzu Motors Ltd
- 6.4.9 Tata Motors Ltd
- 6.4.10 Ashok Leyland
- 6.4.11 Innoson Vehicle Manufacturing Co.
- 6.4.12 Stellantis (Peugeot, Opel)
- 6.4.13 Nissan Motor Co.
- 6.4.14 Kia Corporation
- 6.4.15 BAIC Group
- 6.4.16 Chery Automobile Co.
- 6.4.17 BYD Auto
- 6.4.18 Geely Automobile Holdings
- 6.4.19 Great Wall Motor (Haval)
- 6.4.20 Guangzhou Automobile Group (GAC)