

|
시장보고서
상품코드
2121955
유럽의 스마트 제조 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Smart Manufacturing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
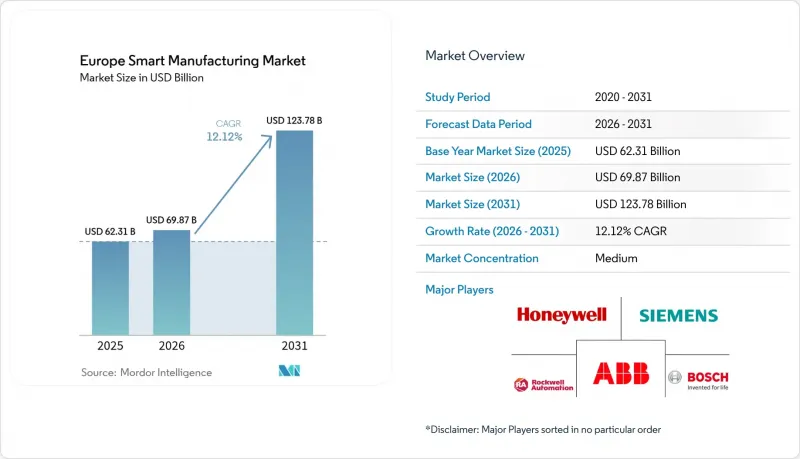
에 의하면, 2026년 유럽의 스마트 제조 시장 규모는 698억 7,000만 달러로 추정되며, 2025년 623억 1,000만 달러에서 2031년에는 1,237억 8,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 12.12%를 기록할 전망입니다.
본 보고서는 기술별(자동화 제어 시스템, 산업용 로봇 등), 구성 요소별(하드웨어, 소프트웨어, 서비스), 최종 사용자 산업별(자동차, 항공우주 및 방위, 화학제품 및 석유화학제품 등), 그리고 국가별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러)으로 제시되어 있습니다.
유럽의 스마트 제조 시장 동향 및 인사이트
EU의 인더스트리 4.0 자금 조달 방안
유럽의 견실한 자금 조달로 인해 디지털 전환을 위한 전례 없는 규모의 자금이 동원되고 있습니다. 독일의 ‘Manufacturing-X’ 프로그램은 상호 운용 가능한 산업용 데이터 공간 구축을 위해 1억 5,000만 유로(1억 6,000만 달러)를 지원하고 있는 반면,보다 광범위한 ‘InvestAI’ 아키텍처는 AI 인프라 전반에 걸쳐 2,000억 유로(2,130억 달러)를 동원하고 있습니다. 중소기업이 매칭 보조금을 활용할 수 있게 됨에 따라 진입 장벽이 낮아지고 있습니다. 영국의 ‘Made Smarter’ 시범 사업에서는 이미 2,200만 파운드(2,800만 달러)가 350건의 기술 프로젝트에 투입되어 1,600명의 신규 일자리를 창출했습니다. 공공 지출에 이어 벤처 기업의 기세도 높아지고 있습니다. 그 일례로, 독일에서는 AI를 활용한 제조 스타트업이 67% 급증했으며, AWS, 마이크로소프트, 애플과 같은 하이퍼스케일러 기업들도 투자를 약속하고 있습니다. 이러한 자본 유입으로 인해 유럽의 스마트 제조 시장은 아시아의 수탁 제조를 대체할 신뢰할 수 있는 대안으로서의 입지를 확립해 나가면서, 지역의 기술 주권도 지켜가고 있습니다.
인건비 상승 압력이 높아지면서 공장 자동화를 추진
2024년, EU의 평균 시간당 인건비는 전년 대비 5% 상승해 33.5유로(35.7달러)에 달했으며, 서유럽과 저임금 지역 간의 격차가 확대되었습니다. 룩셈부르크는 시간당 55.2유로(58.8달러)로 EU 내 1위를 기록하고 있어, 명품 제조업체들 사이에서 자동화에 대한 경쟁적 시급성이 한층 더 높아지고 있습니다. 또한, 고용주들은 심각한 인력 부족에도 직면해 있습니다. 조사 대상 21개국 기업의 75%가 숙련된 인력 확보에 어려움을 겪고 있다고 보고했습니다. 이러한 상호 연관된 압박으로 인해 자동화는 단순한 효율화를 위한 수단에서 기업의 생존과 직결된 필수 요건으로 변화하고 있으며, 유럽의 스마트 제조 시장 전반에서 반복적인 작업을 로봇이나 컴퓨터 비전 시스템으로 대체하는 움직임이 가속화되고 있습니다.
사이버 보안 및 데이터 주권에 대한 우려
'사이버 복원력법'은 위험 수준에 따른 적합성 평가를 의무화하고 있으며, 최대 1,500만 유로(1,600만 달러) 또는 전 세계 매출의 2.5%에 해당하는 벌금이 부과될 수 있습니다. GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정)과 NIS 2(네트워크 및 정보 보안 지침 제2판) 규정이 중복됨에 따라, 특히 사이버 보안 인력이 제한적인 중소기업의 경우 문서화 업무 부담이 증가하고 있습니다. 역외 데이터 전송에 대한 우려로 인해 EU 역외에 호스팅된 하이퍼스케일 플랫폼으로의 전환이 주춤하고 있으며, 공급업체들은 소버린 클라우드 및 엣지 분석 어플라이언스를 제공해야 하는 상황에 처해 있습니다. 이러한 규정 준수 비용은 도입 주기를 길게 만들어 유럽의 스마트 제조 시장의 단기적인 성장 속도를 둔화시키고 있습니다.
부문 분석
2025년, 산업용 로봇은 자동차 최종 조립의 자동화 및 표준화된 용접 셀에 힘입어 유럽의 스마트 제조 시장에서 27.35%의 점유율을 차지했습니다. FANUC의 스페인 사업 확장은 그동안 서비스가 충분히 미치지 못했던 남유럽 클러스터로의 진출을 의미하며, 이 회사의 방폭형 협업 도장 로봇은 위험 환경에서의 용도를 개척하고 있습니다. 디지털 트윈 및 시뮬레이션 플랫폼은 연평균 성장률(CAGR) 16.2%로 확대되고 있으며, 물리 기반 모델과 AI를 결합하여 자산의 거동을 예측하고 시운전 주기를 단축하고 있습니다. 시뮬레이션과 MES(제조 실행 시스템)의 융합을 통해 폐쇄 루프 최적화가 가능해졌으며, 디지털 트윈은 유럽의 스마트 제조 시장에서 가장 빠른 성장을 이끄는 요인으로 자리매김하고 있습니다.
공장이 이더넷 기반 필드버스로 전환됨에 따라 자동화 제어 시스템(PLC, SCADA, DCS)의 업데이트 수요가 증가하고 있습니다. 하네웰의 ‘Experion Operations Assistant’와 같은 AI 강화형 HMI 레이어는 상황에 맞는 권장 사항을 표시하여 경보 피로를 줄여줍니다. Valmet-FactoryPal과 같은 인수를 통해 MES의 보급이 가속화되고 있으며, OEE 대시보드에 처방적 인사이트력이 더해지고 있습니다. 적층 가공는 형상의 복잡성이 생산량의 경제성을 상회하는 예비 부품 공급 분야에서 틈새 시장 지위를 유지하고 있습니다. 이 툴셋의 확장은 유럽의 전체 스마트 제조 시장에서 다양한 수익원을 공고히 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, Europe smart manufacturing market size in 2026 is estimated at USD 69.87 billion, growing from 2025 value of USD 62.31 billion with 2031 projections showing USD 123.78 billion, growing at 12.12% CAGR over 2026-2031.
This report is Segmented by Technology (Automation Control Systems, Industrial Robotics, and More), Component (Hardware, Software, Services), End-User Industry (Automotive, Aerospace and Defense, Chemicals and Petrochemicals, and More), and Country. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Europe Smart Manufacturing Market Trends and Insights
EU Industry-4.0 Funding Schemes
Robust European funding unlocks unprecedented capital for digital transformation. Germany's Manufacturing-X program supplies EUR 150 million (USD 160 million) to create interoperable industrial data spaces, while the broader InvestAI architecture mobilizes EUR 200 billion (USD 213 billion) across AI infrastructure. SME access to matching grants lowers entry barriers; the UK's Made Smarter pilot has already funnelled GBP 22 million (USD 28 million) into 350 technical projects that generated 1,600 new jobs. Venture momentum follows public outlays, illustrated by Germany's 67% jump in AI-enabled manufacturing start-ups and hyperscaler commitments from AWS, Microsoft, and Apple. These capital flows position the Europe smart manufacturing market as a credible alternative to Asian contract manufacturing while defending regional technology sovereignty.
Rising Labor-Cost Pressure Driving Factory Automation
Average EU hourly labor costs climbed 5% year over year to EUR 33.5 (USD 35.7) in 2024, widening the delta between Western Europe and lower-wage regions. Luxembourg tops the bloc at EUR 55.2 (USD 58.8) per hour, sharpening competitive urgency for automation among premium producers. Employers also confront an acute talent gap: 75% of firms surveyed across 21 countries report difficulty filling skilled roles. These intertwined pressures convert automation from a discretionary efficiency lever into an existential requirement, accelerating replacement of repetitive tasks with robotics and computer-vision systems across the Europe smart manufacturing market.
Cyber-Security and Data-Sovereignty Concerns
The Cyber Resilience Act enforces risk-tiered conformity assessments and may levy penalties up to EUR 15 million (USD 16 million) or 2.5% of global turnover. Overlapping GDPR and NIS 2 rules escalate documentation workloads, especially for SMEs with limited cyber teams. Fear of extraterritorial data transfer slows migration to hyperscale platforms hosted outside the EU, compelling suppliers to offer sovereign clouds or edge-analytics appliances. These compliance costs elongate deployment cycles and temper the near-term growth pace of the Europe smart manufacturing market
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of IIoT Connectivity
- Net-Zero Mandates Accelerating Energy-Optimization Solutions
- High Brown-Field Integration CAPEX
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial robotics held 27.35% of Europe smart manufacturing market share in 2025, supported by automotive final-assembly automation and standardized welding cells. FANUC's expansion in Spain signals pursuit of underserved Southern European clusters, while its explosion-proof collaborative paint robot opens hazardous-environment applications. Digital twin & simulation platforms are scaling at a 16.2% CAGR, embedding physics-based models alongside AI to forecast asset behaviour and shrink commissioning intervals. Simulation convergence with MES unlocks closed-loop optimisation, positioning digital twins as the fastest lever inside the Europe smart manufacturing market.
Automation control systems (PLC, SCADA, DCS) experience replacement demand as plants migrate to Ethernet-based fieldbuses. AI-augmented HMI layers such as Honeywell's Experion Operations Assistant surface contextual recommendations that cut alarm fatigue. MES penetration quickens through acquisitions like Valmet-FactoryPal, enriching OEE dashboards with prescriptive insights. Additive manufacturing maintains a niche foothold in spare-parts fulfillment, where geometry complexity outweighs volume economics. This broadening toolset cements diversified revenue streams across the Europe smart manufacturing market.
Complete Report Scope:
- By Technology
- Automation Control Systems (PLC, SCADA, DCS)
- Industrial Robotics
- Industrial IoT Platforms
- Human-Machine Interface (HMI)
- Manufacturing Execution System (MES)
- Product Lifecycle Management (PLM)
- Digital Twin and Simulation
- Additive Manufacturing / 3-D Printing
- By Component
- Hardware
- Sensors
- Controllers / IPC
- Edge-Computing Devices
- Machine-Vision Systems
- Robotics
- Software
- SCADA and HMI Software
- Analytics and AI Software
- ERP and PLM Software
- Services
- Integration and Consulting
- Maintenance and Support
- Managed Services
- Hardware
- By End-user Industry
- Automotive
- Aerospace and Defense
- Chemicals and Petrochemicals
- Food and Beverage
- Pharmaceuticals and Biotechnology
- Metals and Mining
- Electronics and Semiconductors
- Oil and Gas
- Utilities and Energy
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Netherlands
- Sweden
- Poland
- Belgium
- Austria
- Switzerland
- Norway
- Finland
List of Companies Covered in this Report:
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Rockwell Automation Inc.
- Honeywell International Inc.
- Emerson Electric Co.
- General Electric Co.
- Robert Bosch GmbH
- FANUC Corporation
- IBM Corporation
- Dassault Systems SE
- SAP SE
- Mitsubishi Electric Corp.
- KUKA AG
- Yokogawa Electric Corp.
- PTC Inc.
- Hexagon AB
- Omron Corp.
- Beckhoff Automation GmbH
- Endress+Hauser AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Industry-4.0 funding schemes
- 4.2.2 Rising labor-cost pressure driving factory automation
- 4.2.3 Rapid adoption of IIoT connectivity
- 4.2.4 Net-zero mandates accelerating energy-optimisation solutions
- 4.2.5 Edge-AI quality-inspection deployment in European SMEs
- 4.2.6 Industrial-grade 5G private-network roll-outs
- 4.3 Market Restraints
- 4.3.1 Cyber-security and data-sovereignty concerns
- 4.3.2 High brown-field integration CAPEX
- 4.3.3 Fragmented legacy machine protocols in CEE plants
- 4.3.4 Scarcity of digital-twin engineering talent
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape (EU Digital Decade, Gaia-X)
- 4.6 Technological Outlook (IIoT, Digital Twin, 5G, Edge-AI)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Automation Control Systems (PLC, SCADA, DCS)
- 5.1.2 Industrial Robotics
- 5.1.3 Industrial IoT Platforms
- 5.1.4 Human-Machine Interface (HMI)
- 5.1.5 Manufacturing Execution System (MES)
- 5.1.6 Product Lifecycle Management (PLM)
- 5.1.7 Digital Twin and Simulation
- 5.1.8 Additive Manufacturing / 3-D Printing
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.1.1 Sensors
- 5.2.1.2 Controllers / IPC
- 5.2.1.3 Edge-Computing Devices
- 5.2.1.4 Machine-Vision Systems
- 5.2.1.5 Robotics
- 5.2.2 Software
- 5.2.2.1 SCADA and HMI Software
- 5.2.2.2 Analytics and AI Software
- 5.2.2.3 ERP and PLM Software
- 5.2.3 Services
- 5.2.3.1 Integration and Consulting
- 5.2.3.2 Maintenance and Support
- 5.2.3.3 Managed Services
- 5.2.1 Hardware
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Aerospace and Defense
- 5.3.3 Chemicals and Petrochemicals
- 5.3.4 Food and Beverage
- 5.3.5 Pharmaceuticals and Biotechnology
- 5.3.6 Metals and Mining
- 5.3.7 Electronics and Semiconductors
- 5.3.8 Oil and Gas
- 5.3.9 Utilities and Energy
- 5.4 By Country
- 5.4.1 Germany
- 5.4.2 United Kingdom
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Russia
- 5.4.7 Netherlands
- 5.4.8 Sweden
- 5.4.9 Poland
- 5.4.10 Belgium
- 5.4.11 Austria
- 5.4.12 Switzerland
- 5.4.13 Norway
- 5.4.14 Finland
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market-share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Schneider Electric SE
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Honeywell International Inc.
- 6.4.6 Emerson Electric Co.
- 6.4.7 General Electric Co.
- 6.4.8 Robert Bosch GmbH
- 6.4.9 FANUC Corporation
- 6.4.10 IBM Corporation
- 6.4.11 Dassault Systems SE
- 6.4.12 SAP SE
- 6.4.13 Mitsubishi Electric Corp.
- 6.4.14 KUKA AG
- 6.4.15 Yokogawa Electric Corp.
- 6.4.16 PTC Inc.
- 6.4.17 Hexagon AB
- 6.4.18 Omron Corp.
- 6.4.19 Beckhoff Automation GmbH
- 6.4.20 Endress+Hauser AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


