

|
시장보고서
상품코드
2122014
유럽의 혈당 모니터링 시장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Blood Glucose Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
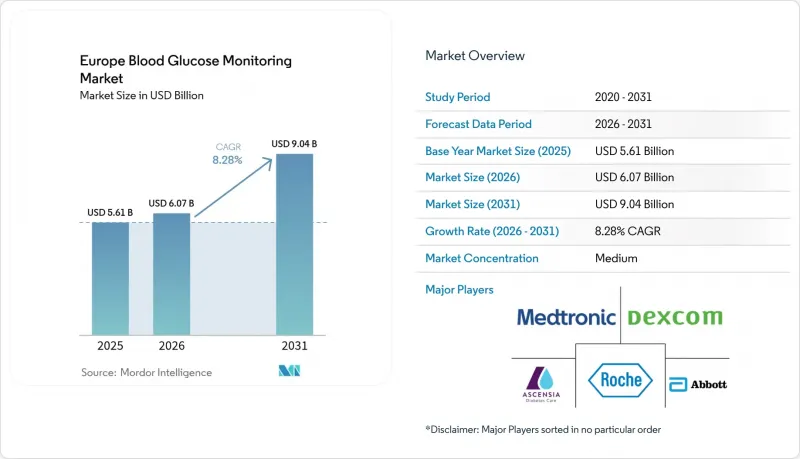
에 의하면, 유럽의 혈당 모니터링 시장 규모는 2025년 56억 1,000만 달러에서 2026년에는 60억 7,000만 달러에 이르고, 2026-2031년 CAGR 8.28%로 성장을 지속하여 2031년까지 90억 4,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 기기 유형(자가 혈당 모니터링기 등), 당뇨병 유형(제1형, 제2형), 연령대(소아, 성인, 고령자), 검사 방법(침습적, 비침습적), 최종 사용자(병원, 재택 간호 등) 및 국가(독일, 프랑스, 영국, 이탈리아 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽 혈당 모니터링 시장 동향 및 인사이트
당뇨병 유병률 증가와 고령화
2025년 현재, 유럽에는 6,100만 명의 당뇨병 환자가 있으며, 국제당뇨병연맹(IDF)은 이 수치가 2030년까지 6,800만 명에 달할 것으로 예측했습니다. 독일에서는 2025년에 850만 건의 진단 사례가 보고되어 2020년 대비 9% 증가했습니다. 한편, 폴란드에서는 지역별 진단 격차를 배경으로 유병률이 7.2%에 달했습니다. 65세 이상 인구층에서는 당뇨병 발병률이 노동 연령층의 3.2배에 달하며, 특히 이탈리아, 스페인, 포르투갈에서 해당 인구 증가 속도가 가장 빠릅니다. 이에 따라 각 제조업체들은 손의 민첩성이나 인지 기능의 제한에 대응할 수 있도록 더 큰 디스플레이와 음성 안내 기능을 갖춘 CGM(연속 혈당 모니터링) 기기 개발을 추진하고 있습니다. 이러한 인구 동향은 센서와 테스트 스트립 모두에 대한 지속적인 수요를 뒷받침하고 있습니다. 그 결과, 환자 1인당 스트립 소비량은 감소하고 있지만, 유럽의 혈당 모니터링 시장에서는 안정적인 기본 판매량이 유지되고 있습니다.
CGM과 SMBG의 정확도 수렴 및 하이브리드 데이터 플랫폼
『The Lancet Diabetes & Endocrinology』지에 게재된 동료 심사 논문에 따르면, 주요 CGM 시스템은 평균 절대 상대 오차(MARD) 값이 9% 미만을 달성하여 실험실 기준에 실질적으로 필적하며, SMBG의 보정 필요성을 없애고 있습니다. 애보트의 ‘FreeStyle Libre 3’와 덱스콤의 ‘G7’은 모두 손가락 채혈을 통한 검증 없이 ISO 15197:2013 인증을 획득했으며, 이에 따라 독일 G-BA는 2025년 7월부터 기저 인슐린을 투여받고 있는 2형 당뇨병 환자에 대한 CGM의 보험 적용을 결정했습니다. 하이브리드 데이터 플랫폼은 현재 CGM 데이터와 인슐린 펌프 알고리즘, 전자 의료 기록을 통합하고 있어, 폐쇄 루프의 정확도를 높이는 동시에 과거 SMBG가 가졌던 1회당 0.45유로라는 가격 우위를 축소시키고 있습니다. 의사 결정권자들이 의료 총비용을 검토하는 상황에서 테스트 스트립의 경제성만으로는 더 이상 SMBG 시장 점유율 하락을 막을 수 없습니다.
CGM 기기 및 소모품의 높은 비용
보험 적용이 불충분하거나 아예 없는 경우, 본인 부담금은 여전히 장벽으로 작용하고 있습니다. 2025년, 이탈리아 사용자들은 Libre 센서에월120-160유로를 지불했는데, 이는 남부 지역의 가처분 소득 중앙값의 12%에 해당합니다. 스페인의 자치주 중 카탈루냐주는 70%의 보험 적용률을 보인 반면, 에스트레마두라주는 고작 18%에 그쳐 환자 단체로부터 법적 제소를 당하고 있습니다. 폴란드에서는 CGM에 대한 공공 자금 지원이 소아 환자로만 제한되어 있어, 28만 명의 성인 인슐린 사용자가월35유로 상당의 SMBG 테스트 스트립에 의존할 수밖에 없어 건강 격차가 더욱 확대되고 있습니다.
부문 분석
2025년에도 SMBG는 유럽 혈당 모니터링 시장 점유율의 60.1%를 차지했습니다. 이는 경구약을 복용하는 2형 당뇨병 환자에 대한 확고한 보험 환급 제도와 1,200만 명의 손가락 채혈식 사용자로 구성된 도입 기반에 힘입은 결과입니다. 로슈의 ‘Accu-Chek Guide’와 라이프스캔의 ‘OneTouch Verio Reflect’는 약국과의 계약에서 핵심을 이루고 있으나, 인슐린 사용자 사이에서 CGM의 보급이 가속화됨에 따라 2025년에는 이러한 테스트 스트립의 판매량이 4-6% 감소했습니다. CGM과 관련된 유럽의 혈당 모니터링 시장 규모는 정확도의 동등성, 교정이 필요 없는 ISO 인증, 그리고 폐쇄 루프 펌프와의 상호 운용성을 원동력으로 연평균 성장률(CAGR) 10.23%로 확대될 것으로 예측됩니다.
신흥 비침습형 웨어러블 제품인 Biolinq사의 마이크로니들 패치와 Nemaura사의 sugarBEAT는 2025년에 제한적인 시범 운영을 시작했으며, 손가락 채혈을 꺼리는 800만 명의 당뇨병 전단계 환자를 대상으로 하고 있습니다. 메드트로닉(Medtronic)사의 Guardian 4 센서는 2025년 3월 출시 후 6개월 이내에 독일 내 신규 CGM 도입의 18%를 차지하며, 완전히 통합된 시스템의 성장세를 입증하고 있습니다. 시장 점유율 하락을 막기 위해 SMBG 벤더 각사는 현재 블루투스 지원 혈당 모니터링기와 분석 포털을 세트로 판매하고 있으며, 1회당 검사 수익이 감소하는 상황에서도 논의의 초점을 ‘기기’에서 ‘데이터’로 전환하려 하고 있습니다.
2025년에는 2형 당뇨병 환자가 매출의 73.21%를 차지하며 환자 수가 많다는 사실이 입증되었으나, 1형 당뇨병 환자가 불균형할 정도로 높은 성장과 기술 구성을 주도하고 있습니다. 소아용 지침에서 CGM이 표준 치료법으로 권장되고, 폐쇄 루프 시스템이 보급됨에 따라 유럽의 혈당 모니터링 시장에서 1형 당뇨병 환자로부터 얻어지는 시장 규모는 연평균 성장률(CAGR) 13.5%로 확대될 것으로 예측됩니다. 독일은 1형 당뇨병 환자 중 CGM 보급률이 78%로 선두를 달리고 있습니다.
또한, 1형 당뇨병 환자는 2형 당뇨병 SMBG(자가 혈당 모니터링) 사용자에 비해 센서 및 펌프 소모품에 대한 1인당 지출이 4.2배 더 많아, 이로 인해 제조업체의 이익률이 집중되고 있습니다. 2형 CGM의 보험 적용 확대는 현재 혈당 평균치뿐만 아니라 저혈당 감소 효과를 임상적으로 입증하는 것이 조건으로 되어 있으며, 각 벤더사는 이 과제에 대해 적극적으로 연구를 진행하고 있습니다. 전당뇨 모니터링이 더 널리 도입된다면, 추가로 1,800만 명의 사용자를 확보할 가능성이 있지만, 이를 위해서는 비용 대비 효과를 입증하는 자료의 제출이 여전히 필수적입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the Europe blood glucose monitoring market size is expected to grow from USD 5.61 billion in 2025 to USD 6.07 billion in 2026 and is forecast to reach USD 9.04 billion by 2031 at 8.28% CAGR over 2026-2031.
This report is Segmented by Device Type (Self-Monitoring Blood Glucose Devices, and More), Diabetes Type (Type-1, Type-2), Age Group (Pediatrics, Adults, Geriatrics), Test Type (Invasive, Non-Invasive), End User (Hospitals, Homecare, and More), and Country (Germany, France, United Kingdom, Italy, and More). Market Forecasts are Provided in Terms of Value (USD).
Europe Blood Glucose Monitoring Market Trends and Insights
Rising Diabetes Prevalence & Ageing Population
Europe counted 61 million adults living with diabetes in 2025, and the International Diabetes Federation projects this figure will reach 68 million by 2030. Germany documented 8.5 million diagnosed cases in 2025, a 9% rise from 2020, while Poland's prevalence hit 7.2% amid rural diagnostic gaps . People aged 65-plus, whose diabetes incidence is 3.2-times higher than the working-age group, are expanding fastest in Italy, Spain, and Portugal, prompting suppliers to design CGMs with larger displays and voice prompts to suit dexterity or cognitive limitations. These demographics underpin sustained unit demand for both sensors and test strips. Consequently, the Europe blood glucose monitoring market continues to see stable baseline volumes even as per-patient strip consumption falls.
CGM-SMBG Accuracy Convergence & Hybrid Data Platforms
Peer-reviewed trials in The Lancet Diabetes & Endocrinology showed leading CGM systems achieving mean absolute relative difference (MARD) values below 9%, effectively matching laboratory standards and removing the calibration rationale for SMBG. Abbott FreeStyle Libre 3 and Dexcom G7 both secured ISO 15197:2013 certification without finger-stick validation, triggering Germany's G-BA to reimburse CGM for basal-insulin Type-2 users from July 2025 . Hybrid data platforms now merge CGM feeds with insulin-pump algorithms and electronic health records, elevating closed-loop accuracy and squeezing the EUR 0.45 per-test price edge that SMBG once held. As decision makers weigh the total cost of care, strip-based economics alone can no longer shield SMBG from share erosion.
High Cost of CGM Devices & Consumables
Out-of-pocket spending remains a hurdle where reimbursement is partial or absent. Italian users paid EUR 120-160 per month for Libre sensors in 2025, 12% of the median disposable income in the south . Spain's autonomous regions showed 70% coverage in Catalonia but only 18% in Extremadura, fuelling legal challenges from patient groups. Poland funds CGM solely for children, leaving 280,000 adult insulin users on SMBG strips that cost EUR 35 monthly, reinforcing health inequities.
Other drivers and restraints analyzed in the detailed report include:
- Expanded Public Reimbursement for CGM Across EU-5
- Digital-Health Integration Enabling Virtual Diabetes Clinics
- Semiconductor-Grade MEMS Supply-Chain Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SMBG still accounted for 60.1% of Europe's blood glucose monitoring market share in 2025, buoyed by entrenched reimbursement for Type-2 patients on oral agents and the 12 million-unit installed base of finger-stick users. Roche Accu-Chek Guide and LifeScan OneTouch Verio Reflect anchor pharmacy contracts, though their test-strip volumes slipped 4-6% in 2025 as CGM accelerated among insulin users. The European blood glucose monitoring market size linked to CGM is forecast to expand at 10.23% CAGR, propelled by accuracy parity, ISO certification without calibration, and interoperability with closed-loop pumps.
Emerging non-invasive wearables-Biolinq's microneedle patch and Nemaura's sugarBEAT-entered limited pilots in 2025, courting the 8 million pre-diabetics who refuse finger pricks. Medtronic's Guardian 4 sensor reached 18% of new CGM starts in Germany within six months of its March 2025 launch, underscoring the momentum behind fully integrated systems. To blunt share loss, SMBG vendors now bundle Bluetooth meters with analytics portals, seeking to shift dialogue from "device" to "data" even as per-test economics erode.
Type-2 cases delivered 73.21% of revenue in 2025, confirming their numeric dominance, yet Type-1 drives disproportionate growth and technology mix. The Europe blood glucose monitoring market size earned from Type-1 users is projected to climb 13.5% CAGR, as pediatric guidelines prescribe CGM as standard of care and closed-loop systems proliferate. Germany leads with 78% CGM penetration among Type-1 patients.
Type-1 patients also spend 4.2-times more per capita on sensors and pump supplies than Type-2 SMBG users, concentrating manufacturer margins. Expanded reimbursement for Type-2 CGM now hinges on clinical demonstration of hypoglycemia reduction rather than glycemic averages alone, a hurdle that vendors are actively studying. Broader inclusion of pre-diabetes monitoring could unlock 18 million additional users, but supportive cost-effectiveness dossiers remain a prerequisite.
Complete Report Scope:
- By Device Type
- Self-Monitoring Blood Glucose (SMBG)
- Continuous Glucose Monitoring (CGM)
- Emerging Non-Invasive Wearables
- By Diabetes Type
- Type-1 Diabetes
- Type-2 Diabetes
- By Age Group
- Pediatrics
- Adults
- Geriatrics
- By Test Type
- Invasive
- Non-Invasive
- By End User
- Hospitals
- Homecare
- Others
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Abbott Laboratories
- Acon Laboratories
- AgaMatrix
- Arkray
- Ascensia
- Biolinq
- Bionime
- Dexcom
- Roche
- Glysens Inc.
- Insulet
- i-Sens Inc.
- Lifescan
- Medisana GmbH
- Medtronic
- Nemaura Medical
- Nipro
- Nova Biomedical
- Rossmax
- Senseonics Inc.
- Terumo
- Trividia Health
- Ypsomed
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diabetes Prevalence & Ageing Population
- 4.2.2 CGM-SMBG Accuracy Convergence & Hybrid Data Platforms
- 4.2.3 Expanded Public Reimbursement For CGM Across EU-5
- 4.2.4 Digital-Health Integration Enabling Virtual Diabetes Clinics
- 4.2.5 Value-Based Procurement & Outcomes-Linked Tenders
- 4.2.6 ESG-Driven Demand For Eco-Designed Reusable Sensors
- 4.3 Market Restraints
- 4.3.1 High cost of CGM devices & consumables
- 4.3.2 Semiconductor-grade MEMS supply-chain constraints
- 4.3.3 GLP-1-driven insulin volume decline dampening sensor demand
- 4.3.4 EU MDR / IVDR bottlenecks & limited Notified-Body capacity
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Device Type
- 5.1.1 Self-Monitoring Blood Glucose (SMBG)
- 5.1.2 Continuous Glucose Monitoring (CGM)
- 5.1.3 Emerging Non-Invasive Wearables
- 5.2 By Diabetes Type
- 5.2.1 Type-1 Diabetes
- 5.2.2 Type-2 Diabetes
- 5.3 By Age Group
- 5.3.1 Pediatrics
- 5.3.2 Adults
- 5.3.3 Geriatrics
- 5.4 By Test Type
- 5.4.1 Invasive
- 5.4.2 Non-Invasive
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Homecare
- 5.5.3 Others
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 France
- 5.6.3 United Kingdom
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 ACON Laboratories
- 6.3.3 AgaMatrix
- 6.3.4 Arkray Inc.
- 6.3.5 Ascensia Diabetes Care
- 6.3.6 Biolinq
- 6.3.7 Bionime Corporation
- 6.3.8 Dexcom Inc.
- 6.3.9 F. Hoffmann-La Roche Ltd
- 6.3.10 Glysens Inc.
- 6.3.11 Insulet Corporation
- 6.3.12 i-Sens Inc.
- 6.3.13 LifeScan Inc.
- 6.3.14 Medisana GmbH
- 6.3.15 Medtronic plc
- 6.3.16 Nemaura Medical
- 6.3.17 Nipro Corporation
- 6.3.18 Nova Biomedical
- 6.3.19 Rossmax International
- 6.3.20 Senseonics Inc.
- 6.3.21 Terumo Corporation
- 6.3.22 Trividia Health
- 6.3.23 Ypsomed AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


