

|
시장보고서
상품코드
2122048
영국의 심혈관 기기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United Kingdom Cardiovascular Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 영국의 심혈관 기기 시장 규모는 2025년에 25억 5,000만 달러로 평가되었고, 2026년 27억 1,000만 달러에서 2031년까지 36억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.06%를 기록할 전망입니다.
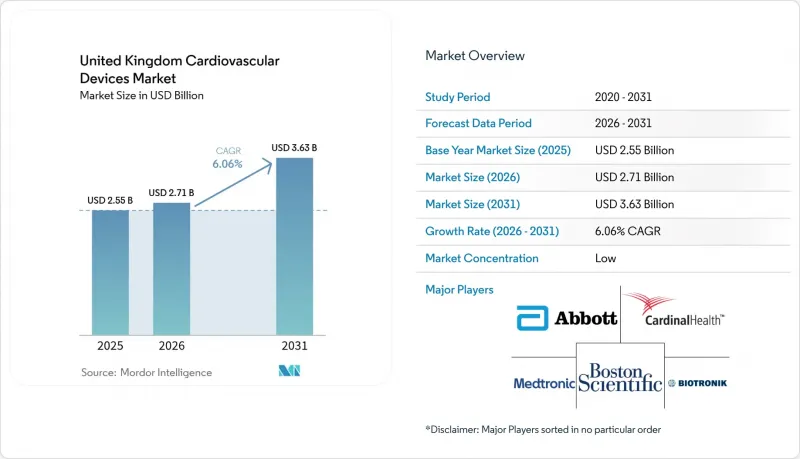
본 보고서는 제품 유형(진단·모니터링 기기, 치료·외과용 기기), 용도(관상동맥 질환, 부정맥·전도 장애, 심부전·심근증, 구조적 및 선천성 심장 질환 등), 최종 사용자(병원·심장 센터, 외래수술센터(ASC) 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
영국 심혈관 의료기기 시장 동향 및 인사이트
NHS의 장기 계획에 따른 심장 네트워크에 대한 자금 증액이 의료기기 도입을 가속화하고 있습니다.
2024년부터 2025년에 걸쳐 NHS에 추가로 배정된 257억 파운드를 통한 목표 지향적인 투자를 통해 심장 네트워크의 현대화가 진행되고 있으며, 기술 갱신 주기가 가속화되고 있습니다. 수술 거점에 15억 파운드, 첨단 방사선 치료실에 7,000만 파운드를 배정함으로써, 각 트러스트는 새로운 의료기기를 도입하는 동시에 미처리 수술 건수를 해소할 수 있는 역량을 확보하고 있습니다. NHS의 10개년 계획에서는 조달을 측정 가능한 성과와 연계하고, 확고한 임상 근거를 갖춘 공급업체를 우선적으로 선정하고 있습니다. 통합 의료 시스템은 트러스트 간의 공동 조달을 촉진하여 발주량을 늘리는 동시에 도입 주기를 최대 2년 단축하고 있습니다. 따라서 이러한 자금 지원은 입증된 가치 제안을 가진 혁신 기업에게 선점자 우위를 강화해 줍니다.
NHS ‘가상 병동’ 프로그램에서의 원격 심장 모니터링의 급속한 확산
NHS 잉글랜드는 2025년까지 5만 개의 가상 병상을 제공하는 것을 목표로 하고 있으며, 이를 통해 심장 치료 경로가 근본적으로 재설계될 것입니다. 노던 케어 얼라이언스(Northern Care Alliance)의 500병상 모델과 같은 초기 시범 사업에서는 급성기 입원이 30% 감소하여 대규모 서비스 설계의 유효성이 입증되었습니다. 심부전으로 인한 입원을 최대 72%까지 줄이는 HeartLogic 및 TriageHF 기술을 권장하는 NICE의 지침은 이 기술의 급속한 보급을 더욱 촉진하고 있습니다. 임페리얼 칼리지 헬스케어(Imperial College Healthcare)의 학술 연구에 따르면, 표준 치료에 원격 모니터링을 병행할 경우 재입원이 76% 감소하는 것으로 나타났습니다. 환자 1인당 1,958파운드의 비용 절감은 비즈니스 사례를 강화하며, NHS의 디지털 아키텍처와 호환되는 의료기기 제조업체에게 새로운 수익원을 개척하고 있습니다.
특정 스텐트 모델의 높은 고장 및 리콜률이 임상의들의 신뢰를 훼손하고 있습니다.
보스턴 사이언티피크(Boston Scientific)의 ‘아콜레이드(Accolade)’ 심박조율기와 애보트(Abbott)의 ‘애슈리티(Assurity)’ 시리즈에 대한 클래스 I 리콜은 신뢰를 흔들고 있으며, 신기술에 대한 더욱 엄격한 심사를 촉구하고 있습니다. 2025년 6월에 시행될 MHRA(영국 의약품 및 의료제품 규제청)의 개혁에 따라 능동적 모니터링과 신속한 사고 보고가 의무화되어, 규정 준수 비용 증가와 제품 출시 지연을 초래하고 있습니다. 악평은 리콜 대상 제품에만 그치지 않고, 관련 제품 카테고리 전체의 채택을 주춤하게 만들고 있습니다. 현재 임상의들은 플랫폼을 전환하기 전에 광범위한 시판 후 데이터를 요구하고 있으며, 이로 인해 판매 주기가 길어지고 중소기업 시장 진입 장벽이 높아지고 있습니다.
부문 분석
치료 및 외과용 플랫폼은 2025년 매출의 57.62%를 차지하며, 고부가가치 중재적 시술을 수행하는 충분한 자원을 갖춘 심장 센터에 의해 뒷받침되고 있습니다. 초박형 약물 방출 스텐트와 TAVR 시스템의 보급은 시술 효율성이 구매 결정에 얼마나 큰 영향을 미치는지를 보여줍니다. 현재 ‘획기적인 의료기기(Breakthrough Device)’로 지정된 애보트(Abbott)사의 리드리스 심박조율기 ‘AVEIR’는 공급업체가 얻을 수 있는 혁신 프리미엄을 여실히 보여주고 있습니다.
진단 및 모니터링 솔루션은 현재 규모가 작지만, 예방 의료와 원격 진료가 중심적인 역할을 맡게 됨에 따라 2031년까지 연평균 성장률(CAGR) 6.63%를 나타낼 것으로 예측됩니다. 병원의 12유도 심전도 장치에 필적하는 AI 탑재 심전도 기기는 이러한 성장세를 여실히 보여주고 있습니다. 가상 병동의 확대로 인해 표준 치료 경로에 원격 텔레메트리가 통합되면서, 클라우드 분석을 통한 지속적인 수익이 확대되고 있습니다. 그 결과, 영국의 심혈관 기기 시장에서 진단 분야 시장 규모는 치료 분야의 성장 속도를 앞지르는 궤도에 올라섰으며, 향후 10년 동안 수익 구성이 재편될 전망입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 규모와 성장 예측
제5장 경쟁 구도
제6장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the UK cardiovascular devices market size was valued at USD 2.55 billion in 2025 and estimated to grow from USD 2.71 billion in 2026 to reach USD 3.63 billion by 2031, at a CAGR of 6.06% during the forecast period (2026-2031).
This report is Segmented by Product Type (Diagnostic & Monitoring Devices, Therapeutic & Surgical Devices), Application (Coronary Artery Disease, Arrhythmia & Conduction Disorders, Heart Failure & Cardiomyopathy, Structural & Congenital Heart Defects, and More), End User (Hospitals & Cardiac Centres, Ambulatory Surgical Centres, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Cardiovascular Devices Market Trends and Insights
NHS Long-Term Plan Funding Boost for Cardiac Networks Accelerating Device Adoption
Targeted investments channelled through the GBP 25.7 billion NHS uplift for 2024-2025 are modernising cardiac networks and enabling faster technology rotation . Allocating GBP 1.5 billion to surgical hubs and GBP 70 million to advanced radiotherapy suites gives trusts the capacity to clear procedure backlogs while integrating novel devices. The NHS 10-Year Plan ties procurement to measurable outcomes, favouring vendors with strong clinical-evidence files. Integrated care systems encourage cross-trust purchasing, increasing order volumes and shortening adoption cycles by up to two years. These funding streams thus reinforce first-mover advantages for innovators with proven value propositions.
Rapid Uptake of Remote Cardiac Monitoring under NHS "Virtual Wards" Programme
NHS England aims to deliver 50,000 virtual-ward beds by 2025, fundamentally redesigning cardiac care pathways. Early pilots such as the Northern Care Alliance's 500-bed model cut acute admissions by 30%, validating the service design at scale. NICE guidance endorsing HeartLogic and TriageHF technologies, which reduce heart-failure hospitalisations by up to 72%, further underpins rapid diffusion. Academic studies at Imperial College Healthcare show 76% fewer readmissions when tele-monitoring complements standard therapy. Savings of GBP 1,958 per patient strengthen the business case, opening new revenue channels for device makers aligned with NHS digital architecture.
High Failure-Recall Rates of Certain Stent Models Eroding Clinician Confidence
Class I recalls involving Boston Scientific's Accolade pacemakers and Abbott's Assurity series have shaken trust, prompting closer scrutiny of new technologies. MHRA reforms effective June 2025 demand active surveillance and faster incident reporting, raising compliance costs and delaying launches. Adverse publicity extends beyond recalled SKUs, dampening uptake across adjacent product categories. Clinicians now seek extensive post-market data before switching platforms, lengthening sales cycles and elevating barriers for SMEs.
Other drivers and restraints analyzed in the detailed report include:
- Growing Backlog of Elective Cardiac Procedures Driving Shift to Minimally Invasive Devices
- Increasing Prevalence of Atrial Fibrillation in Ageing UK Population Raising Demand for Rhythm-Management Devices
- NHS Workforce Shortage Constraining Equipment Replacement Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Therapeutic and surgical platforms generated 57.62% of 2025 revenues, sustained by well-resourced cardiac centres performing high-value interventions. Uptake of ultrathin drug-eluting stents and TAVR systems illustrates how procedural efficiency steers purchasing decisions. Abbott's AVEIR leadless pacemaker, now under breakthrough-device designation, shows the innovation premium vendors can command .
Diagnostic and monitoring solutions, though smaller today, are projected to grow at a 6.63% CAGR through 2031 as prevention and remote care take centre stage. AI-enabled ECG devices that rival 12-lead hospital units underscore this momentum. Virtual-ward expansion embeds remote telemetry in standard care pathways, lifting recurring revenue from cloud analytics. Consequently, the UK cardiovascular devices market size for diagnostics is on path to outstrip therapeutics in growth pace, reshaping revenue mixes over the decade.
Complete Report Scope:
- By Product Type
- Diagnostic & Monitoring Devices
- ECG Systems
- Remote Cardiac Monitor
- Cardiac MRI
- Cardiac CT
- Echocardiography / Ultrasound
- Fractional Flow Reserve (FFR) Systems
- Therapeutic & Surgical Devices
- Coronary Stents
- Drug-Eluting Stents
- Bare-Metal Stents
- Bioresorbable Stents
- Catheters
- PTCA Balloon Catheters
- IVUS/OCT Catheters
- Cardiac Rhythm Management
- Pacemakers
- Implantable Cardioverter Defibrillators
- Cardiac Resynchronization Therapy Devices
- Heart Valves
- TAVR/TAVI
- Mechanical Valves
- Tissue/Bioprosthetic Valves
- Ventricular Assist Devices
- Artificial Hearts
- Grafts & Patches
- Other Cardiovascular Surgical Devices
- Coronary Stents
- Diagnostic & Monitoring Devices
- By Application
- Coronary Artery Disease
- Arrhythmia & Conduction Disorders
- Heart Failure & Cardiomyopathy
- Structural & Congenital Heart Defects
- Peripheral Vascular Disease
- By End User
- Hospitals & Cardiac Centres
- Ambulatory Surgical Centres
- Cardiology/EP Clinics
- Home-care & Remote Monitoring Programs
List of Companies Covered in this Report:
- Medtronic
- Abbott Laboratories
- Boston Scientific
- Edward Lifesciences
- Koninklijke Philips
- Siemens Healthineers
- Johnson & Johnson (Biosense Webster & Cordis)
- GE Healthcare Technologies Inc.
- Terumo
- B. Braun
- BIOTRONIK
- LivaNova
- MicroPort
- Cook Group
- W. L. Gore & Associates
- Getinge AB (Maquet)
- Merit Medical Systems
- Shockwave Medical Inc.
- Penumbra
- SynCardia Systems
- Nipro
- Corin Group PLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
- 3.1 Market Landscape
- 3.2 Market Overview
- 3.3 Market Drivers
- 3.3.1 NHS Long-Term Plan Funding Boost for Cardiac Networks Accelerating Device Adoption
- 3.3.2 Rapid Uptake of Remote Cardiac Monitoring under NHS "Virtual Wards" Programme
- 3.3.3 Growing Backlog of Elective Cardiac Procedures Driving Shift to Minimally Invasive Devices
- 3.3.4 Increasing Prevalence of Atrial Fibrillation in Ageing UK Population Raising Demand for Rhythm Management Devices
- 3.3.5 Government Procurement Frameworks Favouring Environmentally Sustainable Single-Use Catheters
- 3.3.6 Post-Brexit Regulatory Duplication Increasing Approval Costs for SMEs
- 3.4 Market Restraints
- 3.4.1 High Failure-Recall Rates of Certain Stent Models Eroding Clinician Confidence
- 3.4.2 NHS Workforce Shortage Constraining Equipment Replacement Cycles
- 3.4.3 Import-led Inflation Raising ASPs of High-tech Devices Post-Brexit
- 3.4.4 UKCA Certification Uncertainty Deterring SME Product Launches
- 3.5 Value/ Supply-Chain Analysis
- 3.6 Regulatory Landscape
- 3.7 Technological Outlook
- 3.8 Porter's Five Forces
- 3.8.1 Threat of New Entrants
- 3.8.2 Bargaining Power of Suppliers
- 3.8.3 Bargaining Power of Buyers
- 3.8.4 Threat of Substitutes
- 3.8.5 Competitive Rivalry
4 Market Size & Growth Forecasts (Value)
- 4.1 By Product Type
- 4.1.1 Diagnostic & Monitoring Devices
- 4.1.1.1 ECG Systems
- 4.1.1.2 Remote Cardiac Monitor
- 4.1.1.3 Cardiac MRI
- 4.1.1.4 Cardiac CT
- 4.1.1.5 Echocardiography / Ultrasound
- 4.1.1.6 Fractional Flow Reserve (FFR) Systems
- 4.1.2 Therapeutic & Surgical Devices
- 4.1.2.1 Coronary Stents
- 4.1.2.1.1 Drug-Eluting Stents
- 4.1.2.1.2 Bare-Metal Stents
- 4.1.2.1.3 Bioresorbable Stents
- 4.1.2.2 Catheters
- 4.1.2.2.1 PTCA Balloon Catheters
- 4.1.2.2.2 IVUS/OCT Catheters
- 4.1.2.3 Cardiac Rhythm Management
- 4.1.2.3.1 Pacemakers
- 4.1.2.3.2 Implantable Cardioverter Defibrillators
- 4.1.2.3.3 Cardiac Resynchronization Therapy Devices
- 4.1.2.4 Heart Valves
- 4.1.2.4.1 TAVR/TAVI
- 4.1.2.4.2 Mechanical Valves
- 4.1.2.4.3 Tissue/Bioprosthetic Valves
- 4.1.2.5 Ventricular Assist Devices
- 4.1.2.6 Artificial Hearts
- 4.1.2.7 Grafts & Patches
- 4.1.2.8 Other Cardiovascular Surgical Devices
- 4.1.2.1 Coronary Stents
- 4.1.1 Diagnostic & Monitoring Devices
- 4.2 By Application
- 4.2.1 Coronary Artery Disease
- 4.2.2 Arrhythmia & Conduction Disorders
- 4.2.3 Heart Failure & Cardiomyopathy
- 4.2.4 Structural & Congenital Heart Defects
- 4.2.5 Peripheral Vascular Disease
- 4.3 By End User
- 4.3.1 Hospitals & Cardiac Centres
- 4.3.2 Ambulatory Surgical Centres
- 4.3.3 Cardiology/EP Clinics
- 4.3.4 Home-care & Remote Monitoring Programs
5 Competitive Landscape
- 5.1 Market Concentration
- 5.2 Market Share Analysis
- 5.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 5.3.1 Medtronic plc
- 5.3.2 Abbott Laboratories
- 5.3.3 Boston Scientific Corporation
- 5.3.4 Edwards Lifesciences Corporation
- 5.3.5 Koninklijke Philips N.V. (Philips Healthcare)
- 5.3.6 Siemens Healthineers AG
- 5.3.7 Johnson & Johnson (Biosense Webster & Cordis)
- 5.3.8 GE Healthcare Technologies Inc.
- 5.3.9 Terumo Corporation
- 5.3.10 B. Braun Melsungen AG
- 5.3.11 Biotronik SE & Co. KG
- 5.3.12 LivaNova PLC
- 5.3.13 MicroPort Scientific Corporation
- 5.3.14 Cook Medical LLC
- 5.3.15 W. L. Gore & Associates Inc.
- 5.3.16 Getinge AB (Maquet)
- 5.3.17 Merit Medical Systems Inc.
- 5.3.18 Shockwave Medical Inc.
- 5.3.19 Penumbra Inc.
- 5.3.20 SynCardia Systems LLC
- 5.3.21 Nipro Corporation
- 5.3.22 Corin Group PLC
6 Market Opportunities & Future Outlook
- 6.1 White-Space & Unmet-Need Assessment


