|
시장보고서
상품코드
2123105
베트남의 폐기물 관리 시장 : 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Vietnam Waste Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
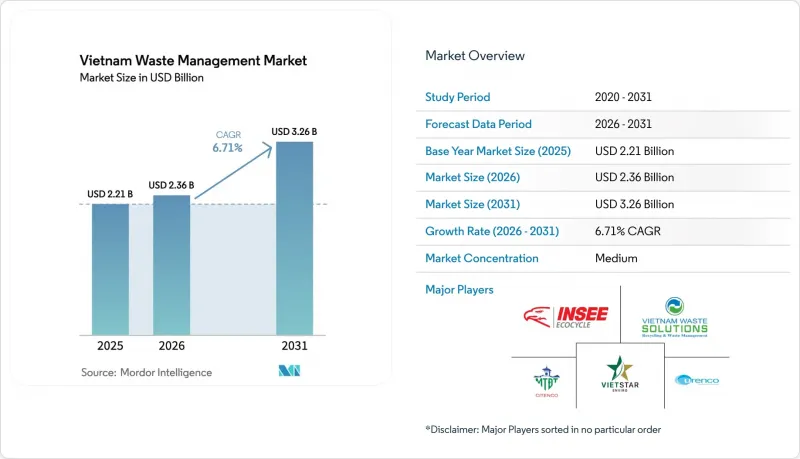
에 의하면, 2026년 베트남 폐기물 관리 시장 규모는 23억 6,000만 달러로 추정되고 있어 2025년 22억 1,000만 달러에서 확대해, 2031년에는 32억 6,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 6.71%로 성장할 것으로 전망됩니다.
본 보고서는 발생원별(주거, 상업, 산업 등), 서비스 유형별(수집·운송·선별 등), 폐기물 유형별(도시 고형 폐기물, 유해 산업 폐기물, 전자 폐기물, 플라스틱 폐기물, 의료 폐기물 등), 지역별(호치민시, 하노이, 다낭, 베트남 기타 지역)으로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
베트남 폐기물 관리 시장 동향 및 인사이트
2030년까지 폐기물 수거율 85%를 목표로 하는 국가 순환형 경제 로드맵
2030년 순환 경제 실행 계획에 따라, 베트남은 도시 지역에서 95%, 농촌 지역에서 80%의 폐기물 회수율을 달성하고, 매립지 이용률을 50% 미만으로 줄이는 것을 목표로 하고 있습니다. 이 전략은 바이오매스 및 도시 폐기물을 재생에너지 목표와 연계하여, 폐기물 발전 사업자에게 정부 공인 수익 기반을 제공합니다. 농업 부문에서는 연간 9,361만 톤의 폐기물이 발생하고 있지만, 재이용되는 비율은 고작 52%에 그치고 있습니다. 현행 규정에 따르면 2025년까지 유기비료 생산량을 25% 늘리고, 2030년까지 등록된 전체 비료의 30%를 유기비료로 채울 것을 요구하고 있습니다. 이러한 목표는 농촌 지역의 소득 증대와 배출 감축 목표를 연계하여 바이오숯 및 퇴비화 사업을 위한 농지 시장을 개척하고 있습니다. 수거 목표가 상향됨에 따라 베트남의 폐기물 관리 시장에서는 원료량의 가시성이 높아지고, 지역 처리 거점의 자금 조달 가능성이 향상되고 있습니다.
환경 법규의 강화 및 집행
베트남의 법적 체계는 현재 정령 제05/2025/ND-CP호, 결정 제611/QD-TTg호,및 결정 제11/2025/QD-TTg호를 중심으로 구성되어 있으며, 이를 통해 각각 더 엄격한 확대 생산자 책임(EPR) 의무, 지역별 처리 구역 목표, 그리고 ‘오염자 부담’ 원칙에 기반한 회수 규정이 도입되었습니다. 새로운 제도에서는 수익 면제 기준액이 상향 조정되었으며, 24개의 인증 재활용 업체가 정식 인가를 받았고, 폐기물 사고를 일으킨 당사자에게는 전액 복구 비용이 부과됩니다. 이러한 규정에 따라 소규모 사업자는 규정 준수를 위한 자금 조달에 어려움을 겪는 반면, 통합형 사업자는 규모의 경제를 활용하여 수익 창출이 가능하기 때문에 시장 재편이 가속화되고 있습니다. 또한, 예측 가능한 집행 체제를 통해 규제 리스크가 감소하고, 대규모 처리 시설에 대한 장기 자금 조달이 가능해집니다. 그 결과, 베트남 폐기물 관리 시장의 중기적 확장을 뒷받침하는 보다 명확하고 투자하기 쉬운 환경이 조성될 것입니다.
매립지 용량 부족과 부지 확보의 장벽
닥논성의 닥 루랍 등의 시설은 설계상의 한계를 넘어 가동되고 있습니다. 이는 다오 기아와 같은 대체 프로젝트가 부지 확보 문제로 정체되어 있어 완공이 2025년 하반기로 미뤄지고 있기 때문입니다. 호치민시에서는 4개의 처리 시설이 이미 1,670헥타르에 달하지만, 이전 협정에서 의무화되었던 완충 지대가 마련되지 않아 확장에 제약을 받고 있습니다. 폐기물 발전 개발 사업자들은 더 넓은 부지와 특별 용도 지역 지정을 필요로 하고 있으며, 이로 인해 승인 절차가 더욱 복잡해지고 공사 기간이 장기화되고 있습니다. 도시 주변부의 토지 부족으로 인해 취득 비용이 급등하고 있어, 사업자들은 초기 투자액이 크고 더 높은 수준의 기술력을 요하는 고밀도형 또는 수직형 기술로 전환할 수밖에 없는 상황입니다.
부문 분석
2025년, 베트남 폐기물 관리 시장 점유율의 55.12%를 가정 쓰레기가 차지했습니다. 이는 예측 가능하고 수거 경로가 밀집된 폐기물량을 발생시키는 도시 인구의 확대에 힘입은 것입니다. 그 결과, 지자체 운영 사업자는 수거 시간을 최적화하고 쓰레기통을 표준화함으로써 가구당 비용을 절감하고, 처리 시설 업그레이드를 위한 자금을 확보하고 있습니다. 베트남 폐기물 관리 시장에서 사업계 폐기물 시장 규모는 현재로서는 훨씬 작지만, 2급 도시 전역에서 쇼핑센터, 물류 허브, 숙박 시설이 증가하고 있어 2031년까지 연평균 성장률(CAGR) 7.92%로 확대될 것으로 예측됩니다. 또한, 사업용 고객들은 주말 수거나 안전한 파쇄 처리 등 수익성이 높은 프리미엄 서비스 패키지도 수용하고 있습니다.
산업 폐기물, 의료 폐기물, 건설 폐기물이 합쳐서 나머지 시장 점유율을 차지하고 있지만, 각 틈새 시장이 전문적인 수익원을 창출하고 있습니다. 유해 폐기물 처리 업체들은 용제 및 슬러지 처리를 위한 인증 취득을 통해 추가 보상을 얻고 있는 반면, 박산성의 병원들은 제33/2025/QD-UBND호 결정에 따른 엄격한 분리 수거 규정을 준수해야 합니다. 고무 제조업체들은 폐수 슬러지를 유기 비료로 전환하는 노력을 시작하고 있으며, 이는 농업 분야에서의 업사이클링 가능성을 시사합니다. 정책적 압력이 강화되는 가운데, 이러한 하위 부문은 확대될 전망이지만, 베트남 폐기물 관리 시장 전체에서 생활폐기물 처리량은 계속해서 차량 가동률의 기반이 될 것입니다.
기타 혜택:
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, Vietnam waste management market size in 2026 is estimated at USD 2.36 billion, growing from 2025 value of USD 2.21 billion with 2031 projections showing USD 3.26 billion, growing at 6.71% CAGR over 2026-2031.
This report is Segmented by Source (Residential, Commercial, Industrial, and More), by Service Type (Collection/Transportation/Sorting, and More), by Waste Type (Municipal Solid Waste, Industrial Hazardous Waste, E-Waste, Plastic Waste, Biomedical Waste, and More), and by Geography (Ho Chi Minh City, Hanoi, Da Nang, Rest of Vietnam). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Waste Management Market Trends and Insights
National Circular-Economy Roadmap Targeting 85% Waste Collection by 2030
Under the 2030 circular-economy action plan, Vietnam aims for 95% urban and 80% rural waste collection, while cutting landfill use below 50%. The strategy also links biomass and municipal waste to renewable-energy targets, giving waste-to-energy developers a government-endorsed revenue story. Agriculture generates 93.61 million tons of waste annually, yet just 52% is reused; regulations now call for a 25% jump in organic-fertilizer output by 2025 and a 30% organic share of all registered fertilizers by 2030. These targets integrate rural income growth with emissions goals, opening farmland markets for biochar and compost initiatives. As collection targets rise, the Vietnam waste management market gains visibility on feedstock volumes, improving bankability for regional treatment hubs.
Tightening Environmental Legislation & Enforcement
Vietnam's legal framework now revolves around Decree 05/2025/ND-CP, Decision 611/QD-TTg, and Decision 11/2025/QD-TTg, each introducing stricter EPR obligations, regional treatment-zone targets, and polluter-pays recovery rules. The new regime lifts revenue-exemption thresholds, formalizes 24 certified recyclers, and assigns full restoration costs to parties causing waste incidents. These rules accelerate market consolidation because smaller operators struggle to finance compliance upgrades, while integrated players monetize economies of scale. Predictable enforcement also reduces regulatory risk, unlocking long-tenor funding for large treatment plants. The net effect is a clearer, more investable backdrop that underpins the Vietnam waste management market's medium-term expansion.
Limited Landfill Capacity & Land-Acquisition Hurdles
Sites such as Dak R'lap in Dak Nong are operating beyond design limits because replacement projects like Dao Nghia remain stalled over land clearance, pushing completion to late 2025. In Ho Chi Minh City, four treatment complexes already span 1,670 ha, yet buffers mandated in earlier agreements are missing, constraining expansion. Waste-to-energy developers need larger footprints and special zoning, adding another layer of approvals that extends timelines. Scarcity of peri-urban land raises acquisition costs, forcing operators to pivot toward high-density or vertical technologies that demand larger upfront capital and more technical skill.
Other drivers and restraints analyzed in the detailed report include:
- Foreign-Investor-Led Technology Transfer in Waste-to-Energy Projects
- Rising Public-Health Awareness & Urban Cleanliness Campaigns
- Capital Constraints for Provincial Waste-Infrastructure Upgrades
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Residential streams held 55.12% of the Vietnam waste management market share in 2025, underpinned by an expanding urban population that generated predictable, route-dense tonnage. As a result, municipal operators have optimized pick-up times and standardized bins, bringing down per-household costs and freeing capital for treatment upgrades. The Vietnam waste management market size for commercial waste is much smaller today, yet it is forecast to rise at an 7.92% CAGR through 2031 as shopping centers, logistics hubs, and hospitality venues multiply across Tier-2 cities. Commercial clients also accept premium service packages, such as weekend pick-up and secure shredding, that carry higher margins.
Industrial, medical, and construction waste together account for the remaining share, yet each niche opens specialized revenue streams. Hazardous-waste contractors earn certification premiums to handle solvents and sludge, while hospitals in Bac Giang must conform to Decision 33/2025/QD-UBND's strict segregation rules. Rubber producers have begun converting wastewater sludge into organic fertilizer, signaling agricultural up-cycling potential. With policy pressure mounting, these sub-segments will scale, but residential tonnage will continue to anchor fleet utilization across the Vietnam waste management market.
Complete Report Scope:
- By Source
- Residential
- Commercial (retail, office, etc.)
- Industrial
- Medical (Health and Pharmaceutical)
- Construction & Demolition
- Others (institutional, agricultural, etc)
- By Service Type
- Collection, Transportation, Sorting & Segregation
- Disposal / Treatment
- Landfill
- Recycling & Resource Recovery
- Incineration & Waste-to-Energy
- Others (Chemical Treatment, Composting, etc.)
- Others (Consulting, Audit & Training, etc.)
- By Waste Type
- Municipal Solid Waste
- Industrial Hazardous Waste
- E-waste
- Plastic Waste
- Biomedical Waste
- Construction & Demolition Waste
- Agricultural Waste
- Other Specialized Waste (radio active, etc)
- By Geography
- Ho Chi Minh City
- Hanoi
- Da Nang
- Rest of Vietnam
List of Companies Covered in this Report:
- CITENCO
- URENCO (Urban Environment Company Hanoi)
- INSEE Ecocycle
- Vietnam Waste Solutions
- Vietstar Environment
- Tetra Tech Coffey Vietnam
- Thuan Thanh Environment JSC
- Sonadezi Services JSC
- DUYTAN Plastic Recycling
- Green Environment Production Services Trade Co. Ltd
- Vietnam Australia Environment JSC
- SGS Vietnam
- Tan Phat Tai Co. Ltd
- An Phat Holdings (AnEco)
- Ha Noi Urban Environment Co. Ltd
- Bac Ninh Clean & Environment JSC
- TKV Waste Treatment Centre
- Holcim Vietnam Geocycle
- Indovin Power (Waste-to-Energy)
- Green Growth Asia Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening environmental legislation & enforcement
- 4.2.2 Rising public health awareness & urban cleanliness campaigns
- 4.2.3 National circular-economy roadmap targeting 85 % waste collection by 2030
- 4.2.4 Foreign-investor led technology transfer in waste-to-energy projects
- 4.2.5 Extended Producer Responsibility (EPR) expansion to packaging & electronics
- 4.3 Market Restraints
- 4.3.1 Limited landfill capacity & land-acquisition hurdles
- 4.3.2 Capital constraints for provincial waste-infrastructure upgrades
- 4.3.3 Fragmented collection system in rural communes
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Force Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Values, In USD Billion)
- 5.1 By Source
- 5.1.1 Residential
- 5.1.2 Commercial (retail, office, etc.)
- 5.1.3 Industrial
- 5.1.4 Medical (Health and Pharmaceutical)
- 5.1.5 Construction & Demolition
- 5.1.6 Others (institutional, agricultural, etc)
- 5.2 By Service Type
- 5.2.1 Collection, Transportation, Sorting & Segregation
- 5.2.2 Disposal / Treatment
- 5.2.2.1 Landfill
- 5.2.2.2 Recycling & Resource Recovery
- 5.2.2.3 Incineration & Waste-to-Energy
- 5.2.2.4 Others (Chemical Treatment, Composting, etc.)
- 5.2.3 Others (Consulting, Audit & Training, etc.)
- 5.3 By Waste Type
- 5.3.1 Municipal Solid Waste
- 5.3.2 Industrial Hazardous Waste
- 5.3.3 E-waste
- 5.3.4 Plastic Waste
- 5.3.5 Biomedical Waste
- 5.3.6 Construction & Demolition Waste
- 5.3.7 Agricultural Waste
- 5.3.8 Other Specialized Waste (radio active, etc)
- 5.4 By Geography
- 5.4.1 Ho Chi Minh City
- 5.4.2 Hanoi
- 5.4.3 Da Nang
- 5.4.4 Rest of Vietnam
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 CITENCO
- 6.4.2 URENCO (Urban Environment Company Hanoi)
- 6.4.3 INSEE Ecocycle
- 6.4.4 Vietnam Waste Solutions
- 6.4.5 Vietstar Environment
- 6.4.6 Tetra Tech Coffey Vietnam
- 6.4.7 Thuan Thanh Environment JSC
- 6.4.8 Sonadezi Services JSC
- 6.4.9 DUYTAN Plastic Recycling
- 6.4.10 Green Environment Production Services Trade Co. Ltd
- 6.4.11 Vietnam Australia Environment JSC
- 6.4.12 SGS Vietnam
- 6.4.13 Tan Phat Tai Co. Ltd
- 6.4.14 An Phat Holdings (AnEco)
- 6.4.15 Ha Noi Urban Environment Co. Ltd
- 6.4.16 Bac Ninh Clean & Environment JSC
- 6.4.17 TKV Waste Treatment Centre
- 6.4.18 Holcim Vietnam Geocycle
- 6.4.19 Indovin Power (Waste-to-Energy)
- 6.4.20 Green Growth Asia Corp.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment