|
시장보고서
상품코드
2123122
싱가포르의 폐기물 관리 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore Waste Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
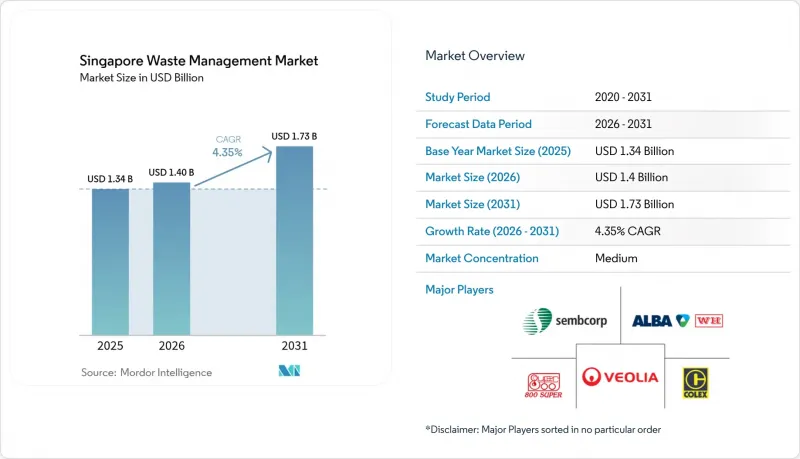
에 의하면, 싱가포르의 폐기물 관리 시장 규모는 2025년 13억 4,000만 달러로 평가되었고, 2026년에는 14억 달러로 추정되고, 2026-2031년 CAGR 4.35%로 성장을 지속할 전망이며, 2031년에는 17억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 발생원별(주거, 상업, 산업 등), 서비스 유형별(수집, 운송, 선별·분리 등), 폐기물 유형별(일반 폐기물, 산업 유해 폐기물, 전자 폐기물, 플라스틱 등), 그리고 계약 모델별(민간·공공)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
싱가포르의 폐기물 관리 시장 동향 및 인사이트
제로 웨이스트 마스터 플랜과 순환 경제 의무화
‘제로 웨이스트 마스터 플랜’은 2030년까지 전국 재활용률을 70%로 높일 것을 의무화하고, 매립 폐기물을 30% 감축하도록 규정하고 있으며, 이에 따라 싱가포르 폐기물 관리 시장의 현금 흐름 구조가 재편되고 있습니다. 전자 폐기물, 식품 폐기물, 포장재라는 3대 우선 분야는 전체 폐기물의 40% 이상을 차지하며, 규제 준수가 선별, 퇴비화 및 고도 재활용 설비에 대한 수요를 견인하고 있습니다. RSA(폐기물 관리 규정)에 따르면, 2024년부터 대규모 시설에서의 음식물 쓰레기 분리 수거가 의무화되어, 이에 따라 사업들은 부지 내 처리 설비나 바이오 펄퍼로 유도되고 있습니다. 신축 시설에서는 이러한 설비를 위한 공간을 확보해야 할 의무가 있어, 기술 공급업체에게는 확실한 프로젝트가 보장됩니다. 또한 월별 보고 의무나 단계적으로 강화되는 벌칙 등 집행 조치가 마련되어 있어 수익의 예측 가능성이 높아지고 있습니다. ‘투아스 넥서스’ 구상에서 볼 수 있듯이, 폐기물 에너지화(WTE)와 물 회수를 통합하여 제공하는 사업자는 정책상 유리한 입지에 위치해 있습니다.
매립지 용량 제한이 소각 및 재활용 수요를 견인
세마카우 매립지는 2035년까지 설계 상의 한계에 도달할 가능성이 있으므로, 이 섬나라는 폐기물 처리처를 변경하거나 폐기물 양을 줄여야 합니다. 현재 4개의 폐기물 에너지화(WTE) 플랜트가 연간 380만 톤을 처리하며, 전력망의 2%를 공급하고 있습니다. 한편, 2021년에 가동을 시작한 투아스 원(TuasOne) 유닛은 하루 3,600톤을 처리하여 전력망에 120MW를 공급하고 있습니다. 투아스 넥서스에 건설될 예정인 통합 폐기물 관리 시설(IWMF)은 하루 5,800톤의 처리 능력을 갖추고 있어 세계 최대 규모의 단일 폐기물 처리 시설이 될 전망입니다. 소각되는 톤수가 늘어날수록 귀중한 토지가 확보되므로, 안정적인 원료 공급 전망이 민간 부문의 장기 건설·운영·양도(BOT) 계약에 대한 의지를 뒷받침하고 있습니다.
신규 시설 부지 부족
토지 이용 경쟁으로 인해 기회 비용이 증가하고 있으며, 악취를 동반하거나 잠재적으로 유해한 활동이 허용되는 산업용지는 이제 극히 일부만 남아 있습니다. 다층식이나 지하식 설계는 부지 면적을 줄일 수 있지만, 설비 투자(Capex) 및 운영·유지보수(O&M)의 복잡성을 증가시킵니다. 사업자는 동일한 부지 내에서 더 높은 처리 능력을 실현하는 설계를 강요받게 되며, 그 결과 기술적 위험과 보험료가 높아집니다. 재활용 센터에는 포장된 폐기물을 보관할 장소가 필요하지만, 수거 구역 근처에 합리적인 가격의 공간이 부족하여 신규 진입을 제한하고 있습니다.
부문 분석
2025년, 싱가포르 폐기물 관리 시장에서 주거용 폐기물은 39.12%라는 압도적인 점유율을 차지했습니다. 이는 주택개발청(HDB)의 단지와 분양 아파트에서 매일 안정적인 양의 폐기물이 발생하기 때문입니다. 상업용 폐기물은 가장 빠르게 성장하고 있으며, RSA가 의무화한 음식물 쓰레기 분리 수거, 전자기기 회수 키오스크, 그리고 쇼핑몰에 폐기물 감축 계획 제출을 의무화하는 그린리스 요건을 배경으로 연평균 성장률(CAGR) 6.31%로 확대되고 있습니다. 주택 부문이 시장의 기반을 이루고 있어 공공 부문 수거 경로에는 기본 수요가 확보되어 있지만, 민간 수거 업체들은 현재 퇴비화기 및 실시간 쓰레기통 수위 센서를 세트로 구성한 ‘사용량 기반 요금 제도’를 내세워 호텔 및 비즈니스 파크 대상 영업에 주력하고 있습니다.
상업 부문의 성장은 적극적인 서비스 다각화도 반영하고 있습니다. 체인 레스토랑에서는 Westcom Bio-Chem 등 지역 스타트업에서 공급한 일일 2톤 용량의 소화조를 도입하기 시작하여 발생원에서의 폐기물 양을 줄이고 있습니다. 오피스 빌딩에서는 블루투스 지원 압축기를 도입하여 ESG 대시보드에 반영되는 데이터를 수집하고 있습니다. 이러한 혁신은 기존의 도로변 수거 방식을 뛰어넘는 것이기 때문에 사업자들은 수익성이 높은 계약을 확보하고 있으며, 이것이 싱가포르 폐기물 관리 시장 전망 가치를 뒷받침하고 있습니다.
수집, 운송, 선별은 2025년 매출의 47.15%를 차지했으며, 싱가포르 폐기물 관리 시장의 물류 중추를 이루고 있습니다. 트럭은 공회전 시간을 줄여주는 텔레매틱스의 지원을 받으며 시내를 단거리 이동해 중계 스테이션으로 폐기물을 운반합니다. 한편, 재활용 및 자원 회수 분야는 2031년까지 연평균 성장률(CAGR) 6.42%의 궤도에 올라 있습니다. 그 예로 REMEX사의 잔재 처리 플랜트를 들 수 있습니다. 이 플랜트는 소각재에서 철계 금속의 90%를 회수하여, 본래라면 폐기되었을 폐기물을 수익화하고 있습니다.
기술의 고도화에 따라 재활용 사업의 이익률이 향상되고 있습니다. 쉘(Shell)사가 프라우 부콤에 신설한 열분해유 정제 플랜트는 재활용이 어려운 플라스틱 5만 톤을 크래커의 원료로 전환하고 있어, 자원 회수가 얼마나 증가액를 견인하는지 보여주고 있습니다. 이러한 움직임을 통해 싱가포르는 고부가가치 순환형 소재 분야의 지역 거점으로서의 위상을 확립하게 되었으며, 싱가포르의 폐기물 관리 시장 규모가 석유화학 밸류체인에 임베디드될 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the Singapore waste management market size is expected to grow from USD 1.34 billion in 2025 to USD 1.4 billion in 2026 and is forecast to reach USD 1.73 billion by 2031 at 4.35% CAGR over 2026-2031.
This report is Segmented by Source (Residential, Commercial, Industrial, and More), by Service Type (Collection, Transportation, Sorting & Segregation, and More), by Waste Type (Municipal Solid, Industrial Hazardous, E-Waste, Plastic, and More), and by by Contract Model (Private and Public). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Waste Management Market Trends and Insights
Zero-Waste Masterplan and Circular-Economy Mandates
The Zero-Waste Masterplan sets a mandatory 70% national recycling rate and orders a 30% cut in landfill waste by 2030, reshaping the cash-flow logic of the Singapore waste management market. Three priority streams, e-waste, food waste, and packaging, together generate more than 40% of total waste, so compliance drives demand for sorting, composting, and advanced recycling kits. The RSA makes food-waste segregation compulsory for large premises from 2024, funneling business toward on-site digesters and bio-pulpers. A new build must now reserve space for such equipment, guaranteeing pipeline projects for technology vendors. Revenue predictability rises because enforcement includes mandatory monthly reporting and escalating penalties. Operators that supply integrated WTE and water recovery, as seen in the Tuas Nexus concept, sit in the policy sweet spot.
Limited Landfill Capacity Driving Incineration and Recycling Demand
Semakau Landfill may reach its design limit by 2035, so the island republic must divert waste or miniaturize it. Four WTE plants currently vaporize 3.8 million t annually and supply 2% of the grid, while the 2021-commissioned TuasOne unit processes 3,600 t per day and delivers 120 MW to the network. The coming Integrated Waste Management Facility (IWMF) at Tuas Nexus will be able to handle 5,800 t per day, becoming the largest single waste complex worldwide. Each incremental tonne incinerated frees scarce land, so feedstock certainty underwrites private-sector appetite for long-term build-operate-transfer deals.
Scarcity of Land for New Facilities
Competing land uses raise opportunity costs, and only a handful of industrial plots remain zoned for odorous or potentially hazardous activities. Multi-story or subterranean designs can compress footprints but raise capex and O&M intricacy. Operators must design for higher throughput in the same envelope, which in turn raises technology risk and insurance premiums. Recycling centers need lay-down yards for baled goods, yet affordable space near collection zones is scarce, limiting new entrants.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory Extended Producer Responsibility Schemes
- NEA Incentive Grants Accelerating Private-Sector Recycling Capacity
- High Capital Expenditure of Advanced Treatment Assets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Residential streams captured a commanding 39.12% share of the Singapore waste management market in 2025 as Housing Development Board estates and condominiums generated steady daily tonnage. Commercial waste is the fastest riser, expanding at a 6.31% CAGR on the back of RSA-mandated food-waste segregation, electronics take-back kiosks, and green-lease requirements that compel malls to file waste-reduction plans. The residential backbone ensures base-load demand for public-sector collection routes, yet private haulers now court hotels and business parks with pay-as-you-throw schemes that bundle composters and real-time bin-level sensors.
Growth in the commercial slice also reflects aggressive service diversification. Chain eateries have begun installing 2 t-per-day digesters sourced from local start-ups such as Westcom Bio-Chem, shrinking disposal volumes at source. Office towers adopt Bluetooth-enabled compactors to unlock data that feeds ESG dashboards. Because these innovations go beyond traditional curbside pickup, operators secure higher-margin contracts that underpin the future value of the Singapore waste management market.
Collection, transport, and sorting still represent 47.15% of 2025 revenue, embodying the logistics backbone of the Singapore waste management market. Trucks make short urban hops to transfer stations, supported by Telematics that cut idle time. Yet the recycling and resource-recovery cluster is on a 6.42% CAGR trajectory through 2031. One example is REMEX's bottom-ash processing plant that recovers 90% of ferrous metals from incinerator ash, monetizing an otherwise wasted stream.
Technology upgrades lift margins in recycling. Shell's new pyrolysis oil upgrader turns 50,000 t of hard-to-recycle plastics into cracker feedstock at Pulau Bukom, signaling how resource recovery will dominate incremental dollar value. These moves reposition Singapore as a regional node for high-value circular materials, and they embed the Singapore waste management market size into the petrochemical supply chain.
Complete Report Scope:
- By Source
- Residential
- Commercial (retail, office, etc.)
- Industrial
- Medical (Health and Pharmaceutical)
- Construction & Demolition
- Others (institutional, agricultural, etc)
- By Service Type
- Collection, Transportation, Sorting & Segregation
- Disposal / Treatment
- Landfill
- Recycling & Resource Recovery
- Incineration & Waste-to-Energy
- Others (Chemical Treatment, Composting, etc.)
- Others (Consulting, Audit & Training, etc.)
- By Waste Type
- Municipal Solid Waste
- Industrial Hazardous Waste
- E-waste
- Plastic Waste
- Biomedical Waste
- Construction & Demolition Waste
- Agricultural Waste
- Other Specialized Waste (radio active, etc)
- By Contract Model
- Public
- Private
List of Companies Covered in this Report:
- SembWaste (Sembcorp)
- Veolia Singapore
- ALBA W&H Smart City
- Colex Holdings Ltd.
- 800 Super Holdings
- ECO Industrial Environmental Engineering
- Wah & Hua Pte Ltd.
- TES-AMM Singapore
- Ramky Cleantech Services
- Enviro-Hub Holdings
- Cleanway Disposal Services
- ChemCollect Services
- Envipure
- Rictec Pte Ltd.
- CH E-Recycling
- Industrial Wastes Auction
- Citic Envirotech
- IUT Global
- ENVAC Singapore
- Zero Waste SG (Services arm)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Zero-Waste Masterplan & Circular Economy mandates
- 4.2.2 Mandatory Extended Producer Responsibility (EPR) schemes
- 4.2.3 Limited landfill capacity driving incineration & recycling demand
- 4.2.4 NEA incentive grants accelerating private-sector recycling capacity
- 4.2.5 Pneumatic Waste Conveyance Systems (PWCS) deployment momentum
- 4.2.6 Tuas Nexus waste-to-hydrogen pilot projects
- 4.3 Market Restraints
- 4.3.1 High capex of advanced treatment infrastructure
- 4.3.2 Scarcity of land for new facilities
- 4.3.3 Rising operating costs (labour, fuel, carbon tax)
- 4.3.4 Volatile recyclables prices in a small domestic market
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Force Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Values, In USD Billion)
- 5.1 By Source
- 5.1.1 Residential
- 5.1.2 Commercial (retail, office, etc.)
- 5.1.3 Industrial
- 5.1.4 Medical (Health and Pharmaceutical)
- 5.1.5 Construction & Demolition
- 5.1.6 Others (institutional, agricultural, etc)
- 5.2 By Service Type
- 5.2.1 Collection, Transportation, Sorting & Segregation
- 5.2.2 Disposal / Treatment
- 5.2.2.1 Landfill
- 5.2.2.2 Recycling & Resource Recovery
- 5.2.2.3 Incineration & Waste-to-Energy
- 5.2.2.4 Others (Chemical Treatment, Composting, etc.)
- 5.2.3 Others (Consulting, Audit & Training, etc.)
- 5.3 By Waste Type
- 5.3.1 Municipal Solid Waste
- 5.3.2 Industrial Hazardous Waste
- 5.3.3 E-waste
- 5.3.4 Plastic Waste
- 5.3.5 Biomedical Waste
- 5.3.6 Construction & Demolition Waste
- 5.3.7 Agricultural Waste
- 5.3.8 Other Specialized Waste (radio active, etc)
- 5.4 By Contract Model
- 5.4.1 Public
- 5.4.2 Private
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 SembWaste (Sembcorp)
- 6.4.2 Veolia Singapore
- 6.4.3 ALBA W&H Smart City
- 6.4.4 Colex Holdings Ltd.
- 6.4.5 800 Super Holdings
- 6.4.6 ECO Industrial Environmental Engineering
- 6.4.7 Wah & Hua Pte Ltd.
- 6.4.8 TES-AMM Singapore
- 6.4.9 Ramky Cleantech Services
- 6.4.10 Enviro-Hub Holdings
- 6.4.11 Cleanway Disposal Services
- 6.4.12 ChemCollect Services
- 6.4.13 Envipure
- 6.4.14 Rictec Pte Ltd.
- 6.4.15 CH E-Recycling
- 6.4.16 Industrial Wastes Auction
- 6.4.17 Citic Envirotech
- 6.4.18 IUT Global
- 6.4.19 ENVAC Singapore
- 6.4.20 Zero Waste SG (Services arm)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment