|
시장보고서
상품코드
2123731
인도의 핀테크 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)India Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
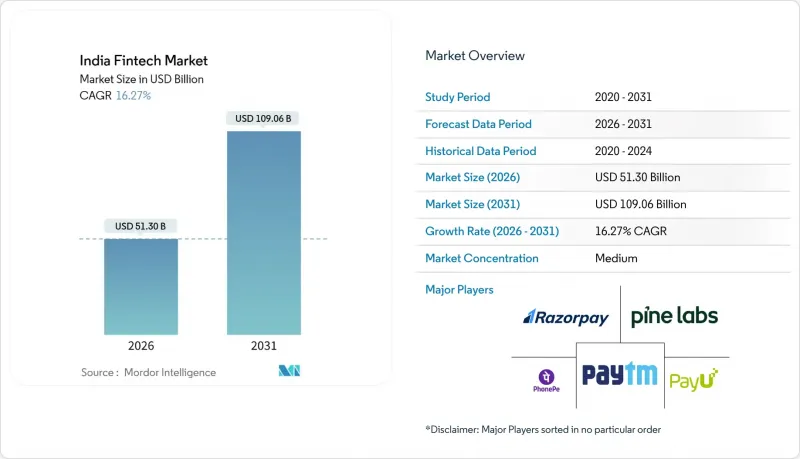
에 의하면, 인도 핀테크 시장 규모는 2026년에 513억 달러가 되어, 예측 기간(2026-2031년)에서 CAGR 16.27%로 성장을 지속하여, 2031년에는 1,090억 6,000만 달러에 이를 전망입니다.
본 보고서는 서비스별(디지털 결제, 디지털 대출·자금 조달, 디지털 투자, 인슈어테크, 네오뱅킹), 최종 사용자별(개인, 법인), 사용자 인터페이스별(모바일 앱, 웹/브라우저, POS/IoT 기기)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도 핀테크 시장 동향과 인사이트
정부가 구축한 디지털 공공 인프라(UPI, Aadhaar, OCEN)가 대중 시장에서의 보급을 가속화하고 있습니다.
인도의 실시간 결제 인프라, Aadhaar 기반의 신원 확인, 상호 운용 가능한 데이터 공유 기반이 결합되어, 그동안 대규모 신규 고객 확보와 거래를 지연시켰던 장벽을 제거하고 있습니다. 2023년, 인도의 전 세계 실시간 결제 시장 점유율은 49%에 달했으며, 이를 통해 정기적인 결제 활동과 매일 발생하는 방대한 거래량에서 수익을 창출하는 가맹점 수용 모델이 뒷받침되고 있습니다. 2025년 8월 기준, 아드하르를 통한 인증 건수는 22억 1,000만 건에 달하며, 성인 커버율은 99.7%에 이르렀습니다. 이를 통해 KYC(고객 신원 확인)의 공백이 해소되고, 인도 핀테크 시장의 신규 고객 확보 과정이 단축되고 있습니다. 계좌 통합 네트워크는 동의를 얻은 사용자를 26억 1,000만 건 이상의 연계 계좌와 연결하여, 대출 기관이나 보험 판매업자가 수 초 이내에 검증된 금융 데이터를 확보할 수 있도록 하고 있습니다. 이를 통해 신용 이력이 부족한 고객에 대한 신용 심사 기간이 단축됩니다. 인도 핀테크 시장이 준도시 및 농촌 지역으로 서비스 범위를 확대함에 따라, 이러한 결제 인프라들은 결합되어 결제, 신용, 보험, 투자에 걸친 통합형 서비스 전개를 뒷받침하는 규모의 경제를 창출하고 있습니다.
데이터 기반 신용 심사를 가능하게 하는 계정 통합자(Account Aggregator) 프레임워크
계좌 통합업체(AA) 프레임워크는 금융 데이터에 대한 동의 기반 접근을 표준화하여, 핀테크 플랫폼과 제휴하는 은행 및 비은행 금융회사(NBFC)의 리스크 평가 비용을 절감합니다. 사용자가 라이선스를 취득한 AA를 통해 은행 계좌 및 기타 금융 정보원을 연동함으로써, 대출 기관은 현금 흐름을 실시간으로 파악할 수 있게 되며, 이를 통해 신용 이력이 부족한 고객에게 소액의 운전자금이나 개인 대출을 제공할 수 있게 됩니다. RBI(인도준비은행)의 광범위한 규제 샌드박스 및 디지털 대출에 관한 지침은 정보 공개 및 민원 처리 절차를 강화하고 있으며, 더 많은 대출 기관이 스크린 스크래핑에서 감사 가능한 동의 모델로 전환함에 따라 인도 핀테크 시장의 지속 가능한 성장을 뒷받침하고 있습니다. API 및 동의 흐름의 표준화를 통해, 과거에는 소규모 기업이나 긱 워커를 정식 대출에서 배제했던 수동 검증으로 인한 지연이 완화됩니다. 장기적으로는 검증된 거래 내역을 기반으로 한 신용 심사를 통해 포트폴리오의 질이 향상되는 동시에, 인도 핀테크 시장에서 처음으로 대출을 받는 사람들의 접근성도 확대될 것입니다.
RBI의 강화된 디지털 대출 및 FLDG 기준이 규정 준수 비용을 상승시키고
RBI의 디지털 대출 지침은 정보 공개, 에스크로 분리, 민원 처리를 강화하고 있으며, 이로 인해 인도 핀테크 시장의 플랫폼 및 규제 대상 파트너의 고정적인 규정 준수 비용이 증가하고 있습니다. 위험 보유 및 채무 불이행 보증에 대한 명확화로 인해 자본 요건이 대출 기관 및 공동 대출 기관에 전가되어, 은행 파트너로의 위험 이전에 의존하던 비즈니스 모델의 마진이 압박받고 있습니다. 대규모 대출 기관이나 자본력이 탄탄한 플랫폼은 이러한 비용을 흡수할 수 있지만, 인도 핀테크 시장에서 규정 준수가 규모의 경제로 자리 잡음에 따라 소규모 사업자들은 시장에서 철수하거나 통합될 수밖에 없는 상황에 처해 있습니다. RBI의 샌드박스 및 감독상 중점 방침에 따라 상품 설계는 투명성과 고객 보호 방향으로 이끌리고 있으며, 이로 인해 규제 리스크는 감소하고 있지만 실험적인 서비스의 전개는 둔화되고 있습니다. 이러한 재조정으로 인해 급속한 성장보다는 지속 가능한 대출 구성에 우선순위가 두어지게 되어, 인도 핀테크 시장에서 새로운 균형이 형성될 때까지는 디지털 대출의 확대가 억제될 것입니다.
부문 분석
2025년, 디지털 결제는 인도 핀테크 시장 점유율의 42.87%를 차지했습니다. 이는 UPI의 규모와 가맹점에서의 수용이 일상적인 구매에서 습관적인 이용을 뒷받침하고 있기 때문입니다. 인도의 실시간 결제 인프라는 결제 전환율과 가맹점의 신뢰를 뒷받침하고 있으며, 이는 인도 핀테크 시장 전체에서 보험, 대출, 자산 운용 상품에 대한 교차 판매를 촉진하고 있습니다. 인도의 핀테크 업계는 앱을 최우선으로 하는 사용자 경험과 상호 운용 가능한 결제 인프라를 활용하여 고객 확보의 장벽을 낮추는 동시에, 대도시권을 넘어 준도시 지역으로의 도달 범위를 확대되고 있습니다. 어그리게이터는 구매자 보호 및 수출 결제 계좌를 포함한 대기업 및 중소기업용 도구를 제공함으로써, 인도 핀테크 시장에서 MDR(가맹점 수수료율)을 넘어서는 수익화를 실현하고 있습니다. 결제 애그리게이터에 대한 규제 지침에 따라 순자산 기준, 규모의 경제, 규정 준수 성숙도가 높아짐에 따라 결제 분야의 업계 재편이 촉진되고 있습니다.
인도 핀테크 시장에서 네오뱅킹 시장 규모는 멀티뱅크형 UPI 모델과 앱 중심의 계좌가 ‘디지털 퍼스트’ 고객층에서의 이용을 심화함에 따라, 2026년부터 2031년까지 연평균 성장률(CAGR) 19.64%로 확대될 것으로 예측됩니다. 네오뱅크는 기존 인프라 위에 예산 관리, 신용 접근, 비즈니스 뱅킹 기능을 중첩하여 제공함으로써, 인도 핀테크 시장에서 고객 유지율과 수수료 수익의 향상을 도모하고 있습니다. 디지털 대출의 성장은 당분간 완만해질 전망입니다. 이는 위험 인수 기준 및 정보 공개를 중시하는 프로세스가 비용 증가를 초래하고, 은행과의 공동 대출 모델 및 더욱 엄격한 대출 심사가 촉진되기 때문입니다. 인도 핀테크 시장에서 자산 운용 및 보험 애그리게이터는 판매 채널과 서비스 계층을 결합하여 규모를 확대하는 한편, 대규모 결제 인프라를 활용한 교차 판매를 통해 고객 확보를 유지하고 있습니다. 예측 기간 동안, 결제, 신용, 보장을 통합된 인터페이스로 결합한 서비스 제안은 인도 핀테크 시장에서 사용자 1인당 평생 가치(LTV)를 더 높게 확보할 수 있는 입지에 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the India fintech market size is USD 51.30 billion in 2026 and is projected to reach USD 109.06 billion by 2031 at a 16.27% CAGR during the forecast period (2026-2031).
This report is Segmented by Service Proposition (Digital Payments, Digital Lending and Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), and User Interface (Mobile Applications, Web/Browser, POS/IoT Devices). The Market Forecasts are Provided in Terms of Value (USD).
India Fintech Market Trends and Insights
Government-Built Digital Public Infrastructure (UPI, Aadhaar, OCEN) Accelerating Mass-Market Adoption
India's real-time payments infrastructure, Aadhaar-based identity, and interoperable data-sharing rails together remove friction that previously slowed onboarding and transactions at scale. India's share of global real-time payments reached 49% in 2023, which supports recurring payment behaviours and merchant acceptance models that monetize at large daily volumes. Aadhaar authentication hit 2.21 billion in August 2025, with adult coverage at 99.7%, which closes KYC gaps and shortens onboarding in the India fintech market. The Account Aggregator network has linked consented users to over 2.61 billion enabled accounts, allowing lenders and insurance distributors to retrieve verified financial data within seconds, which compresses underwriting timelines for thin-file customers. Together, these rails power scale economics that favour embedded journeys across payments, credit, insurance, and investments as the India fintech market deepens coverage in semi-urban and rural districts.
Account Aggregator Framework Unlocking Data-Driven Credit Underwriting
The Account Aggregator framework normalizes consent-based access to financial data and reduces the cost of risk assessment for banks and NBFCs partnering with fintech platforms. With users connecting bank accounts and other financial repositories through licensed AAs, lenders derive a real-time view of cash flows, which supports extensions of small-ticket working capital and personal credit to thin-file customers. RBI's broader regulatory sandbox and digital lending directions strengthen disclosures and grievance processes, which support sustainable scale for the India fintech market as more lenders shift from screen-scraping to auditable consent models. Standardization across APIs and consent flows lowers manual verification delays that once kept micro-entrepreneurs and gig workers outside formal credit. Over time, underwriting that relies on verified transaction trails improves portfolio quality while increasing access for first-time borrowers in the India fintech market.
RBI's Stricter Digital-Lending and FLDG Norms Raising Compliance Cost
RBI's digital lending directions strengthen disclosures, escrow segregation, and grievance handling, which increases fixed compliance costs for platforms and their regulated partners in the India fintech market. Clarifications around risk retention and default guarantees shift capital requirements to lenders and co-lenders, which compresses margins for models that depended on risk transfer to bank partners. Larger lenders and well-capitalized platforms can absorb these costs, while smaller entities face exit or consolidation as compliance becomes a scale advantage in the India fintech market. RBI's sandbox and supervisory focus push product design toward transparency and customer protection, which reduces regulatory risk but slows experimental rollouts. This recalibration prioritizes sustainable origination over rapid growth, which tempers expansion in digital lending before a new equilibrium emerges in the India fintech market.
Other drivers and restraints analyzed in the detailed report include:
- Embedded-Finance Demand from E-commerce and Gig-Economy Platforms
- Formalization of MSMEs Post-GST Creating New SME Fintech Demand Pools
- Zero-MDR Policy Compressing Payment-Gateway Profit Pools
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Digital payments captured 42.87% of the India fintech market share in 2025, anchored by UPI's scale and merchant acceptance that sustains habitual usage across daily purchases. India's real-time rail supports checkout conversion and merchant trust, which anchors cross-sell into protection, loan, and wealth products across the India fintech market. The India fintech industry uses app-first journeys and interoperable rails to reduce acquisition friction and extend reach beyond metros into semi-urban districts. Aggregators ship enterprise and SMB tools, including buyer protection and export settlement accounts, which create monetization beyond MDR in the India fintech market. As regulatory guidance on payment aggregators raises net worth thresholds, scale advantages, and compliance maturity, it drives consolidation within payments.
The India fintech market size for neobanking is projected to expand at a 19.64% CAGR between 2026 and 2031 as multi-bank UPI models and app-centric accounts deepen usage among digital-first customers. Neobanks layer budgeting, credit access, and business banking features on top of existing rails, which improves retention and fee capture in the India fintech market. Digital lending growth moderates in the near term as risk retention norms and disclosure-heavy processes add cost, which encourages co-lending models with banks and more selective origination. Wealth and insurance aggregators scale by combining distribution with service layers, while maintaining customer acquisition through cross-sell on a large payment basis in the India fintech market. Over the forecast period, propositions that bundle payments, credit, and protection into unified interfaces are positioned to capture higher lifetime value per user in the India fintech market.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending and Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
List of Companies Covered in this Report:
- Paytm (One97 Communications Ltd)
- PhonePe Pvt Ltd
- Razorpay Software Pvt Ltd
- Pine Labs Pvt Ltd
- PayU Payments Pvt Ltd
- BharatPe (Resilient Innovations Pvt Ltd)
- MobiKwik (One MobiKwik Systems Ltd)
- PolicyBazaar (PB Fintech Ltd)
- Zerodha Broking Ltd
- Upstox (RKSV Securities India Pvt Ltd)
- Groww (Nextbillion Technology Pvt Ltd)
- Cred Financial Technologies Pvt Ltd
- Slice (GaragePreneurs Internet Pvt Ltd)
- KreditBee (Finnov Pvt Ltd)
- Lendingkart Finance Ltd
- Capital Float (Axio Digital)
- NeoGrowth Credit Pvt Ltd
- Navi Technologies Ltd
- Jupiter (Amica Finance Pvt Ltd)
- NIYO Solutions Pvt Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-Built Digital Public Infrastructure (UPI, Aadhaar, OCEN) Accelerating Mass-Market Adoption
- 4.2.2 Account Aggregator Framework Unlocking Data-Driven Credit Underwriting
- 4.2.3 Embedded-Finance Demand from E-commerce & Gig-Economy Platforms
- 4.2.4 Formalization of MSMEs post-GST Creating New SME Fintech Demand Pools
- 4.2.5 Millennial & Gen-Z Wealth Creation Driving Low-Cost Robo-Advisory Uptake
- 4.2.6 Cross-Border UPI Linkages (e.g., Singapore, UAE) Opening New Remittance Revenues
- 4.3 Market Restraints
- 4.3.1 RBI's Stricter Digital-Lending & FLDG Norms Raising Compliance Cost
- 4.3.2 Zero-MDR Policy Compressing Payment-Gateway Profit Pools
- 4.3.3 Escalating Cyber-Fraud Incidents Undermining Consumer Trust
- 4.3.4 Post-2022 Funding Winter Constraining Scale-Up Capital
- 4.4 Value Chain Analysis
- 4.5 Regulatory or Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Investment & Funding Trend Analysis
5 Market Size & Growth Forecasts (Value)
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending and Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Paytm (One97 Communications Ltd)
- 6.4.2 PhonePe Pvt Ltd
- 6.4.3 Razorpay Software Pvt Ltd
- 6.4.4 Pine Labs Pvt Ltd
- 6.4.5 PayU Payments Pvt Ltd
- 6.4.6 BharatPe (Resilient Innovations Pvt Ltd)
- 6.4.7 MobiKwik (One MobiKwik Systems Ltd)
- 6.4.8 PolicyBazaar (PB Fintech Ltd)
- 6.4.9 Zerodha Broking Ltd
- 6.4.10 Upstox (RKSV Securities India Pvt Ltd)
- 6.4.11 Groww (Nextbillion Technology Pvt Ltd)
- 6.4.12 Cred Financial Technologies Pvt Ltd
- 6.4.13 Slice (GaragePreneurs Internet Pvt Ltd)
- 6.4.14 KreditBee (Finnov Pvt Ltd)
- 6.4.15 Lendingkart Finance Ltd
- 6.4.16 Capital Float (Axio Digital)
- 6.4.17 NeoGrowth Credit Pvt Ltd
- 6.4.18 Navi Technologies Ltd
- 6.4.19 Jupiter (Amica Finance Pvt Ltd)
- 6.4.20 NIYO Solutions Pvt Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment