|
시장보고서
상품코드
2123764
석유 및 가스 다운스트림 부문 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Oil And Gas Downstream - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
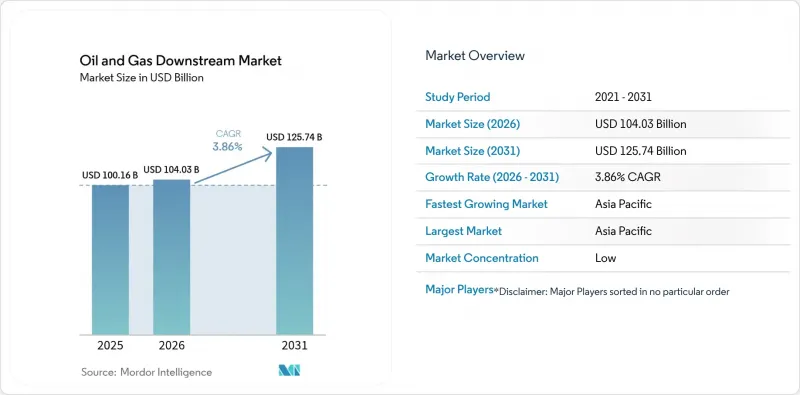
석유 및 가스 다운스트림 부문 시장 규모는 2026년에 1,040억 3,000만 달러로 추정되며, 2025년 1,001억 6,000만 달러에서 확대해, 2031년에는 1,257억 4,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 3.86%로 성장할 것으로 전망됩니다.

본 보고서는 유형별(정유시설 및 석유화학 플랜트), 제품 유형별(정제 석유 제품, 석유화학제품, 윤활유),유통 채널별(직접 판매/도매, 유통업체/상업, 소매), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 석유 및 가스 다운스트림 부문 시장 동향 및 인사이트
정제 능력 확대의 급증으로 지역 간 재균형 촉진
2024년부터 2028년까지 아시아태평양 및 중동에서 총 490만 배럴/일의 프로젝트가 진행 중이며, 이에 따라 세계 경제의 중심이 이러한 거점으로 이동하고 있습니다. 이로 인해 통합형 운영사는 규모의 경제와 원료의 근접성이라는 이점을 얻는 반면, 유럽 및 북미의 이익률은 압박을 받고 있습니다.
석유화학제품 수요 증가가 정유시설의 경제성을 변화시키고 있습니다.
석유화학제품은 이미 전 세계 석유 수요의 14%를 차지하고 있으며, 앞으로도 더욱 증가할 것으로 예측됩니다. 이로 인해 정유사들은 사우디 아람코의 ‘모티바’나 중국 연안 지역의 메가 프로젝트에서 볼 수 있듯이, 통합형 복합 시설에서 나프타 분해 및 방향족 화합물 추출을 위해 운영 체제를 재구축해야 하는 상황에 직면해 있습니다.
전기차 보급이 휘발유 수요의 펀더멘털에 압박을 가하고 있다.
2024년 전 세계 전기차(EV) 판매 대수는 1,400만 대에 달하여, 유럽 및 중국 일부 지역에서 휘발유 수요 감소를 가속화했습니다. 이에 따라 정유사들은 디젤 연료, 제트 연료 및 석유화학제품에 집중하고 있습니다.
부문별 분석
2025년, 정유시설은 석유 및 가스 다운스트림 부문 시장의 65.25%를 차지하며, 자산 활용도 향상과 석유화학 부문 확충에 힘입어 연평균 성장률(CAGR) 4.52%로 성장할 전망입니다. 이 부문은 실시간 마진 신호에 따라 운송용 연료와 화학 원료 사이를 전환할 수 있는 유연한 구성의 이점을 누리고 있습니다. 사우디 아람코의 모티바(Motiva) 확장 프로젝트와 릴라이언스의 잠나가르 복합 단지는 배럴당 비용을 절감하고 하이드로크래커의 수율을 향상시키는 규모의 시너지를 구현하고 있습니다. 통합형 시설의 건설로 인해 석유화학 플랜트와의 경계가 모호해지면서, 소규모 독립 시설의 경우 진입 장벽이 높아지고 있습니다.
석유화학 플랜트는 시장 점유율이 34.75%로 작지만, 아시아태평양에서 나프타 크래커와 프로판 탈수소 설비가 급증함에 따라 4.72%의 성장 궤도를 보이고 있습니다. 사업자들은 공용 유틸리티, 물류, 수소 네트워크를 통합하여 제품별 부가가치 창출을 활용하고 있습니다. 그러나 원료 가격 변동과 통합형 메가사이트와의 경쟁으로 인해 단독 시설의 경제성은 제한받고 있습니다. 전반적으로 석유 및 가스 다운스트림 시장 규모는 이 두 가지 추세를 모두 아우르는 생산 능력 전략을 통해 회복력을 높이고 있습니다.
지역별 분석
아시아태평양은 2025년에 32.85%의 점유율로 1위를 차지하며, 인구 동향의 호재, 산업화, 정책 지원이 맞물려 중국, 인도, 동남아시아의 생산 능력이 급증함에 따라 연평균 4.92%의 성장이 예상됩니다. 중국에서는 석유화학제품 수요가 휘발유 소비의 정체세를 상쇄하고 있는 반면, 인도의 정유업체들은 아프리카와 라틴아메리카로의 수출 프리미엄을 추구하고 있습니다. 인도네시아, 말레이시아, 태국은 주요 해상 루트를 따라 구축된 허브 앤 스포크(hub-and-spoke)형 물류망을 통해 제품 균형을 강화하고 있습니다.
북미에서는 휘발유 수요가 감소하고 있지만, 에탄을 풍부하게 함유한 셰일 자원을 활용하여 석유화학 크래커 및 수소화 처리 설비에 원료를 공급함으로써 경쟁력 있는 현금 비용을 유지하고 있습니다. Philips 66(Phillips 66) 등 미국의 통합 기업들은 캘리포니아주의 LCFS(저탄소 연료 기준) 및 연방 정부의 SAF(지속 가능한 항공 연료) 인센티브에 대응하기 위해 재생 가능 디젤 생산 설비로 개조를 추진하고 있습니다. 캐나다의 중질유 업그레이더와 멕시코 정부 주도의 신규 건설 프로젝트는 원료 구성의 다각화를 도모하고 있지만, 신규 단독 생산 능력에 대해서는 여전히 자금 조달 과제가 남아 있습니다.
유럽에서는 ‘Fit-for-55’ 프레임워크 하에서 연료 수요 감소에 대응하기 위해 각 거점을 HVO 및 SAF를 생산하는 바이오 허브로 전환하는 한편, 잔류 CO₂를 저감하기 위해 CCS 클러스터를 통합하고 있습니다. ADNOC의 루와이스 2단계 등 중동의 프로젝트에서는 가스·액체 유동과 보조금을 받은 유틸리티을 활용하여 EU 및 아시아의 수입업체에게 공급하고 있습니다. 아프리카에서는 나이지리아와 앙골라에서 새로운 복합 시설이 등장하고 있지만, 자본 부족에 직면해 있습니다. 한편, 브라질의 페트로브라스는 국내 수요 충당과 통화 및 정책 주기의 변동 사이에서 균형을 맞추면서, 지역별 석유 및 가스 다운스트림 시장의 다양한 상황을 종합적으로 주도하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, oil and gas downstream market size market size in 2026 is estimated at USD 104.03 billion, growing from 2025 value of USD 100.16 billion with 2031 projections showing USD 125.74 billion, growing at 3.86% CAGR over 2026-2031.
This report is Segmented by Type (Refineries and Petrochemical Plants), Product Type (Refined Petroleum Products, Petrochemicals, and Lubricants), Distribution Channel (Direct Sales/Wholesale, Distributors/Commercial, and Retail), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Oil And Gas Downstream Market Trends and Insights
Surge in Refining Capacity Expansion Drives Regional Rebalancing
Asia-Pacific and Middle Eastern projects, totaling 4.9 million b/d between 2024 and 2028, are tilting global economics toward these hubs, giving integrated operators scale and feedstock proximity advantages while compressing European and North American margins.
Petrochemical Demand Growth Transforms Refinery Economics
Petrochemicals already account for 14% of global oil demand and are expected to rise further, prompting refiners to reconfigure their operations toward naphtha cracking and aromatics extraction in integrated complexes, as exemplified by Saudi Aramco's Motiva and China's coastal mega-projects.
Electric Vehicle Adoption Pressures Gasoline Demand Fundamentals
Global EV sales reached 14 million units in 2024, accelerating the decline in gasoline demand in Europe and certain segments of China, prompting refiners to shift their focus toward diesel, jet fuel, and petrochemicals.
Other drivers and restraints analyzed in the detailed report include:
- IMO Sulfur Regulations Drive Ongoing Compliance Investments
- Aviation-Fuel Recovery and SAF Mandates Create New Revenue Streams
- Net-Zero Climate Policies Constrain Long-Term Investment Horizons
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Refineries accounted for 65.25% of the Oil & Gas Downstream market in 2025 and should advance at a 4.52% CAGR, a pace underpinned by asset-utilization upgrades and petrochemical add-ons. This segment benefits from a flexible configuration that toggles between transport fuels and chemical feedstocks based on real-time margin signals. Saudi Aramco's Motiva expansion and Reliance's Jamnagar complex exemplify the scale synergies that lower per-barrel costs and enhance hydrocracker yields. Integrated builds blur the lines with petrochemical plants, raising barriers for smaller standalone facilities.
Petrochemical plants, although holding a smaller 34.75% share, post a 4.72% trajectory as naphtha crackers and propane dehydrogenation units proliferate in the Asia-Pacific region. Operators bundle shared utilities, logistics, and hydrogen networks to exploit co-product valorization. Yet feedstock-price swings and competition from integrated mega-sites temper standalone economics. Overall, the Oil & Gas Downstream market size gains resilience from this dual-track capacity strategy.
Complete Report Scope:
- By Type
- Refineries
- Petrochemical Plants
- By Product Type
- Refined Petroleum Products
- Petrochemicals
- Lubricants
- By Distribution Channel
- Direct Sales/Wholesale
- Distributors/Commercial
- Retail
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Norway
- Netherlands
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
The Asia-Pacific region leads with a 32.85% share in 2025 and is expected to grow at a rate of 4.92% annually due to capacity surges in China, India, and Southeast Asia, where demographic tailwinds, industrialization, and policy support converge. China's petrochemical pull counters peaking gasoline use, while Indian refiners chase export premiums to Africa and Latin America. Indonesia, Malaysia, and Thailand strengthen their product balance through hub-and-spoke logistics along vital sea lanes.
North America, despite a decline in gasoline demand, exploits ethane-rich shale to feed petrochemical crackers and hydrotreaters, thereby anchoring competitive cash costs. U.S. consolidators such as Phillips 66 retrofit units for renewable diesel to align with California's LCFS and federal SAF incentives. Canada's heavy-oil upgraders and Mexico's government-driven builds diversify feedstock slates, though financing hurdles persist for new standalone capacity.
Europe navigates declining fuel volumes under the Fit-for-55 umbrella by converting sites into bio-hubs producing HVO and SAF, while integrating CCS clusters to mitigate residual CO2. Middle Eastern projects, such as ADNOC's Ruwais Phase II, leverage gas-liquids streams and subsidized utilities to serve EU and Asian importers. Africa is witnessing emerging complexes in Nigeria and Angola, but it is contending with capital scarcity. Meanwhile, Brazil's Petrobras balances domestic demand coverage with volatility in currency and policy cycles, collectively steering the regional mosaic of the oil and gas downstream market.
- China Petroleum & Chemical Corp (Sinopec)
- Exxon Mobil Corporation
- Royal Dutch Shell plc
- Saudi Arabian Oil Company (Saudi Aramco)
- BP plc
- TotalEnergies SE
- China National Petroleum Corporation (CNPC)
- Reliance Industries Limited
- Indian Oil Corporation Limited
- Chevron Corporation
- Phillips 66 Company
- Marathon Petroleum Corporation
- Valero Energy Corporation
- Petroleo Brasileiro S.A. (Petrobras)
- ENI S.p.A.
- PTT Public Company Limited
- SK Innovation Co., Ltd.
- Kuwait Petroleum Corporation
- Lukoil PJSC
- OMV Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in refining capacity (APAC & Middle East)
- 4.2.2 Booming petrochemical demand
- 4.2.3 Stricter IMO 2020 & sulfur fuel rules
- 4.2.4 Aviation-fuel rebound & SAF mandates
- 4.2.5 Digital-twin/AI OPEX optimization
- 4.2.6 Hydrogen co-product monetization
- 4.3 Market Restraints
- 4.3.1 EV penetration eroding gasoline demand
- 4.3.2 Net-zero policies curbing fossil fuels
- 4.3.3 Climate-risk-driven downtime & insurance
- 4.3.4 High interest rates limit new refineries
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Refinery Throughput Capacity Analysis
- 4.8 Key Projects Information
- 4.9 Porter's Five Forces
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
- 4.10 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Refineries
- 5.1.2 Petrochemical Plants
- 5.2 By Product Type
- 5.2.1 Refined Petroleum Products
- 5.2.2 Petrochemicals
- 5.2.3 Lubricants
- 5.3 By Distribution Channel
- 5.3.1 Direct Sales/Wholesale
- 5.3.2 Distributors/Commercial
- 5.3.3 Retail
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 Norway
- 5.4.2.4 Netherlands
- 5.4.2.5 Russia
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Australia
- 5.4.3.7 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Nigeria
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 China Petroleum & Chemical Corp (Sinopec)
- 6.4.2 Exxon Mobil Corporation
- 6.4.3 Royal Dutch Shell plc
- 6.4.4 Saudi Arabian Oil Company (Saudi Aramco)
- 6.4.5 BP plc
- 6.4.6 TotalEnergies SE
- 6.4.7 China National Petroleum Corporation (CNPC)
- 6.4.8 Reliance Industries Limited
- 6.4.9 Indian Oil Corporation Limited
- 6.4.10 Chevron Corporation
- 6.4.11 Phillips 66 Company
- 6.4.12 Marathon Petroleum Corporation
- 6.4.13 Valero Energy Corporation
- 6.4.14 Petroleo Brasileiro S.A. (Petrobras)
- 6.4.15 ENI S.p.A.
- 6.4.16 PTT Public Company Limited
- 6.4.17 SK Innovation Co., Ltd.
- 6.4.18 Kuwait Petroleum Corporation
- 6.4.19 Lukoil PJSC
- 6.4.20 OMV Group
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment