

|
시장보고서
상품코드
2124222
미국의 의약품 CMO 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Pharmaceutical CMO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
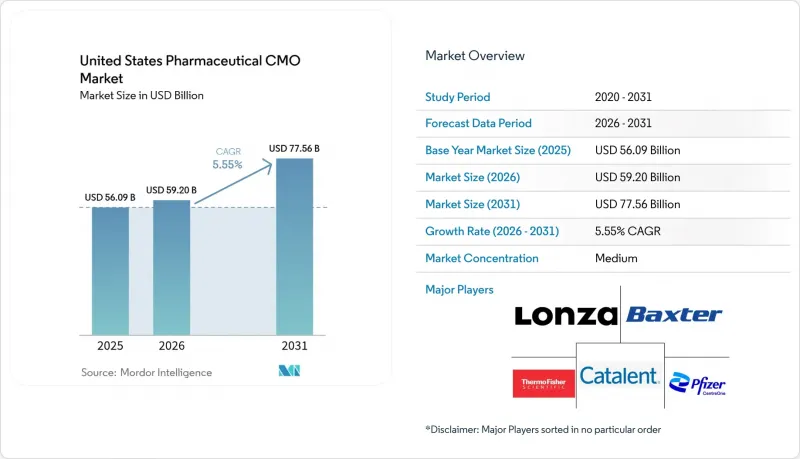
에 의하면, 미국의 의약품 CMO 시장 규모는 2025년에 559억 1,000만 달러로 평가되었고, 2026년 592억 달러에서 2031년까지 775억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.55%를 나타낼 전망입니다.
본 보고서는 서비스 유형별(API 제조, FDF 개발 및 제조, 2차 포장), 약제 분자 유형별(저분자, 바이오의약품, 첨단 치료제), 사업 규모별(임상 단계 제조, 상업적 규모 제조), 최종 사용자별(대형 의약품사, 기타), 치료 분야별(종양학, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국의 의약품 CMO 시장 동향 및 인사이트
GLP-1 수요 급증에 따른 충전·마무리 생산 능력 부족
2023-2025년 세마글루타이드와 틸제파티드의 주간 처방량이 3배로 증가함에 따라, 원래 인슐린 생산량에 맞추어 설계되었던 주사기 및 자동 주사기 생산 라인이 이를 감당하지 못하는 상황이 되었습니다. 2024년 노보노르디스크가 카탈렌트의 3개 공장을 인수함에 따라 일반 시장의 주사제 생산 할당량의 약 4분의 1이 사라졌으며, 중소규모의 의뢰 기업들은 18개월의 대기 시간이나 할증 요금을 감수할 수밖에 없는 상황입니다. 일라이 릴리사가 인디애나주 레바논에 90억 달러를 투자해 추진 중인 확장 계획에 따라 2027년까지 4개의 무균 제조 시설이 추가될 예정이지만, 당분간은 공급 부족이 지속되고 있습니다. 각 CDMO 업체들은 현재 GLP-1 관련 프로젝트에 대해 2024년 요금보다 30-40% 높은 요금을 청구하고 있으며, 이로 인해 일회용 충전 시스템과 자동 시각 검사의 신속한 도입이 촉진되고 있습니다. 2024년에 시작된 FDA의 ‘품질 관리 성숙도 시범 프로그램’에서는 배치 주기를 2-3주 단축하는 실시간 출하 전 검사에 대해 인센티브가 지급됩니다.
바이오시큐어 법과 국내 조달 인센티브
2024년 5월에 시행된 바이오시큐어법에 따라 연방 정부 계약업체는 중국과 밀접한 관계를 맺고 있는 공급업체로부터 원료를 조달하는 것이 금지되었으며, 이에 따라 1년 이내에 약 30억 달러 규모의 바이오의약품 관련 업무가 국내 및 동맹국의 CDMO로 전환될 전망입니다. 포유류 세포 배양 수주 대기 기간은 현재 9-15개월에 달하고 있으며, 이에 따라 삼성바이오로직스는 2027년 하반기 가동을 목표로 하는 22억 달러 규모, 25만 6,000리터 용량의 텍사스 공장 착공에 착수했습니다. 이에 이어 론자(Lonza)는 CHO 세포주에 초점을 맞춘 10억 달러 규모의 피어랜드(Pierland) 거점 확장 계획을 발표했습니다. 내셔널 리질리언스(National Resilience)는 생물방어 관련 계약을 목적으로 캘리포니아주에 유전자 치료 허브를 건설하기 위해 8억 달러를 조달했습니다. 연방 감사관은 현재 ISO 13485 및 21 CFR Part 11 준수 여부를 그 어느 때보다 상세하게 면밀히 조사했으며, 소규모 경쟁사들에게는 시장 진입 장벽이 높아지고 있습니다.
아시아태평양 및 남미의 저비용 CDMO
인도와 중국 공급업체들은 미국 API 가격보다 30-40% 낮은 가격을 책정하고 있으며, 브라질의 사업자들은 2025년에 무균 주사제 생산 능력을 4억 달러 규모로 증설했습니다. 바이오콘 바이오로직스와 닥터 레디스는 트라스투주맙과 아달리무맙 바이오시밀러의 생산 규모를 확대하고 있으며, 2027-2028년에 미국 특허가 만료될 때 시장 점유율을 확보할 준비를 갖추고 있습니다. 2024년 FDA는 데이터 완전성 관련 미비 사항을 이유로 인도의 API 제조 공장에 14건의 경고장을 발부했으나, 제네릭 의약품의 이익률로는 미국의 비용 구조를 상쇄할 수 없기 때문에 듀얼 소싱은 여전히 일반적입니다. 그 결과, 국내 CDMO는 저비용 경쟁사가 따라올 수 없는 속도, 품질 지표, 혹은 높은 격리 수준을 요구하는 틈새 시장에서 경쟁해야 합니다. 이익률 압박이 가장 심각한 분야는 가격 민감도가 가장 높은 범용 경구 고형 제제 부문입니다.
부문 분석
고활성 API(HPAPI) 관련 사업은 2031년까지 연평균 6.21%의 성장률을 보이며, 서비스 구성 중 가장 빠른 성장세를 나타냈습니다. 미국 의약품 CMO 시장에서 API 서비스 규모는 2025년에 261억 7,000만 달러에 달한 것으로 평가되었으며, 항체-약물 복합체(ADC)의 페이로드에는 나노그램 수준의 봉입이 요구되기 때문에 HPAPI가 가장 높은 이익률을 가져다주고 있습니다. 캠브렉스(Cambrex)사가 아이오와주에 건설한 1억 2,000만 달러 규모의 반응 장치는 세포 독성 약물에 특화하기 위한 전환을 상징합니다. 고형제, 액제, 주사제를 포함한 모든 제형의 제제가 나머지 수익을 차지하고 있지만, GLP-1 및 바이오의약품 파이프라인 덕분에 주사제 수요가 가장 빠르게 확대되고 있습니다. 고형제의 연속 제조는 사이클 타임을 75% 단축하지만, 이 기술을 채택한 국내 생산 라인은 20개 미만에 그치고 있습니다.
서비스 제공업체는 양극화가 진행되고 있으며, 대규모 사업자는 API부터 포장까지의 통합 체인에 투자하는 반면, 틈새 시장 기업은 HPAPI, 방사성 표지, 또는 지질 나노입자 제제를 대상으로 하고 있습니다. 스폰서 기업들은 표준 반응기에 비해 SafeBridge 인증 설비에 30-70%의 프리미엄을 지불하고 있으며, 기존 설비의 개조를 촉진함으로써 미국의 의약품 CMO 시장을 확대되고 있습니다. 대조적으로, 범용 고형 제형 제조업체들은 특히 제네릭 의약품의 가격 압박이 커지는 가운데, 처리 능력과 비용 면에서 경쟁하고 있습니다.
2025년 시점에서도 저분자 의약품이 매출의 58.24%를 차지했지만, 첨단 치료제는 2031년까지 연평균 성장률(CAGR) 6.52%로 확대되고 있습니다. 바이러스 벡터와 플라스미드 DNA의 생산 능력 부족으로 인해 수주까지의 대기 기간은 12-18개월로 늘어났습니다. 서모피셔(Thermo Fisher)의 플레인빌(Plainville) 거점과 후지필름 디오신스(Fujifilm Diosynth)의 노스캐롤라이나 캠퍼스는 대규모 유전자 치료제 생산을 위한 자본 경쟁의 대표적인 사례입니다. 바이오의약품은 중간 수준의 성장 궤도를 따르고 있으며, 확립된 CHO 플랫폼과 블록버스터 항체의 독점권이 만료됨에 따라 발생하는 바이오시밀러 기회에 힘입고 있습니다.
첨단 치료와 관련된 미국의 의약품 CMO 시장 점유율은 현재로서는 소규모이지만, 보험사가 일회성 근치적 치료를 수용함에 따라 확대될 전망입니다. 동시에, 저분자 의약품 CDMO 기업들은 HPAPI 대응 설비를 강화하고 오남용 방지 제형에 대한 전문 지식을 활용하여 수익성을 유지하려고 노력하고 있습니다. 따라서 분자의 다양성은 수탁 기업에게 전략적 유연성의 기반이 되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the United States pharmaceutical CMO market size was valued at USD 55.91 billion in 2025 and estimated to grow from USD 59.2 billion in 2026 to reach USD 77.56 billion by 2031, at a CAGR of 5.55% during the forecast period (2026-2031).
This report is Segmented by Service Type (API Manufacturing, FDF Development and Manufacturing, and Secondary Packaging), Drug Molecule Type (Small Molecule, Biologics, and Advanced Therapies), Scale of Operation (Clinical-Phase, and Commercial-Scale), End User (Big Pharma, and More), Therapeutic Area (Oncology, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
United States Pharmaceutical CMO Market Trends and Insights
Surge In GLP-1 Demand Straining Fill-Finish Capacity
Weekly semaglutide and tirzepatide prescriptions tripled between 2023 and 2025, overwhelming syringe and autoinjector lines originally sized for insulin volumes. The 2024 acquisition of three Catalent plants by Novo Nordisk removed roughly one-quarter of open-market injectable slots, forcing smaller sponsors to accept 18-month queues or premium surcharges. Eli Lilly's USD 9 billion Lebanon, Indiana, build-out will add four aseptic suites by 2027, yet interim shortages persist. CDMOs now charge 30%-40% more than 2024 rates for expedited GLP-1 projects, spurring rapid adoption of single-use filling systems and automated vision inspection. The FDA's Quality Management Maturity pilot, launched in 2024, rewards real-time release testing that trims two to three weeks from batch cycles.
BioSecure Act And Domestic Sourcing Incentives
Effective May 2024, the BioSecure Act bars federal contractors from sourcing drug substance from suppliers with significant Chinese ties, redirecting an estimated USD 3 billion in biologics work to domestic and allied CDMOs within a year. Mammalian cell-culture bookings now run 9-15 months, prompting Samsung Biologics to break ground on a USD 2.2 billion, 256,000-liter Texas plant slated for late 2027 start-up. Lonza followed with a USD 1 billion Pearland expansion focused on CHO cell lines. National Resilience raised USD 800 million for a California gene-therapy hub aimed at biodefense contracts. Federal auditors now scrutinize ISO 13485 and 21 CFR Part 11 compliance in unprecedented depth, raising the bar for smaller competitors.
Lower-Cost CDMOs In Asia-Pacific and South America
Indian and Chinese suppliers undercut U.S. API pricing by 30%-40%, and Brazilian operators added USD 400 million in sterile-injectable capacity during 2025. Biocon Biologics and Dr. Reddy's have scaled biosimilars for trastuzumab and adalimumab, positioning to capture share when U.S. patents expire in 2027-2028. Although the FDA issued 14 warning letters to Indian API plants in 2024 for data-integrity failures, dual-sourcing remains common because generic margins cannot absorb U.S. cost structures. Consequently, domestic CDMOs must compete on speed, quality metrics, or high-containment niches that low-cost rivals cannot mimic. Margin compression is most acute in commodity oral solids, where price sensitivity is highest.
Other drivers and restraints analyzed in the detailed report include:
- Growing Pipeline of Biologics and Advanced Therapies
- Shift Toward Outsourcing to Reduce CapEx
- Regulatory Complexities and Serialization Mandates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High-potency API work grew 6.21% annually through 2031, the quickest pace within the service mix. The United States pharmaceutical CMO market size for API services reached USD 26.17 billion in 2025, with HPAPI contributing the steepest margin because antibody-drug conjugate payloads require nanogram-level containment. Cambrex's USD 120 million Iowa reactors exemplify the shift toward cytotoxic specialization. Full-dose formulation, including solid, liquid, and injectable products, fills the remainder of revenue, yet injectable demand is expanding fastest due to GLP-1 and biologics pipelines. Continuous manufacturing in solid dose cuts cycle time 75% but fewer than 20 domestic lines use the technology.
Service providers are bifurcating scale players invest in integrated API-to-packaging chains, while niche firms target HPAPI, radiolabelling, or lipid-nanoparticle formulation. Sponsors pay 30%-70% premiums for SafeBridge-certified suites versus standard reactors, expanding the United States pharmaceutical CMO market by incentivizing brownfield retrofits. Commodity solid-dose producers, by contrast, compete on throughput and cost, especially as generic pricing pressure intensifies.
Small molecules still accounted for 58.24% revenue in 2025, yet advanced therapies are accelerating at a 6.52% CAGR to 2031. Viral-vector and plasmid-DNA capacity shortfalls elevate booking windows to 12-18 months. Thermo Fisher's Plainville site and FUJIFILM Diosynth's North Carolina campus illustrate the capital race toward large-scale gene-therapy production. Biologics occupy the middle trajectory, sustained by established CHO platforms and biosimilar opportunities as blockbuster antibodies lose exclusivity.
The United States pharmaceutical CMO market share for advanced therapies, while modest today, is set to widen as payers embrace one-time curative treatments. Simultaneously, small-molecule CDMOs hedge with HPAPI upgrades and abuse-deterrent formulation expertise to defend margins. Molecule diversity therefore anchors strategic flexibility for contractors.
Complete Report Scope:
- By Service Type
- API Manufacturing
- Small Molecule
- Large Molecule
- High-Potency API (HPAPI)
- FDF Development and Manufacturing
- Solid Dose
- Liquid Dose
- Injectable Dose
- Secondary Packaging
- API Manufacturing
- By Drug Molecule Type
- Small Molecule
- Biologics
- Advanced Therapies (Cell and Gene)
- By Scale of Operation
- Clinical-Phase Manufacturing
- Commercial-Scale Manufacturing
- By End User
- Big Pharma
- Generic Pharma
- Emerging / Virtual Biotech
- Specialty Pharma
- By Therapeutic Area
- Oncology
- Cardiovascular
- Central Nervous System (CNS)
- Infectious Disease
- Other Therapeutic Areas
List of Companies Covered in this Report:
- Catalent Inc.
- Thermo Fisher Scientific Inc. (Patheon)
- Lonza Group AG
- Pfizer CentreOne (Pfizer Inc.)
- Baxter International Inc. (BioPharma Solutions)
- AbbVie Contract Manufacturing (AbbVie Inc.)
- Recipharm AB
- Jubilant Pharmova Limited
- Boehringer Ingelheim BioXcellence
- Aenova Group GmbH
- Siegfried Holding AG
- Samsung Biologics Co., Ltd.
- FUJIFILM Diosynth Biotechnologies USA Inc.
- Cambrex Corporation
- Alcami Corporation Inc.
- PCI Pharma Services
- Ajinomoto Bio-Pharma Services
- Emergent BioSolutions Inc.
- Vetter Pharma-Fertigung GmbH & Co. KG
- Grand River Aseptic Manufacturing Inc.
- Curia Global Inc.
- National Resilience Inc.
- Avid Bioservices Inc.
- KBI Biopharma Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift Toward Outsourcing to Reduce CapEx
- 4.2.2 Growing Pipeline of Biologics and Advanced Therapies
- 4.2.3 Capacity Shortages Among U.S. Sterile Facilities
- 4.2.4 Rising Demand for High-Potency API Suites
- 4.2.5 Surge in GLP-1 Demand Straining Fill-Finish Capacity
- 4.2.6 BioSecure Act and Domestic Sourcing Incentives
- 4.3 Market Restraints
- 4.3.1 Lower-Cost CDMOs in Asia-Pacific and Latin America
- 4.3.2 Regulatory Complexities and Serialization Mandates
- 4.3.3 Acute Scarcity of Skilled Radiopharmaceutical Workforce
- 4.3.4 Cybersecurity Insurance Premiums Post-Ransomware Incidents
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors on the Market
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 API Manufacturing
- 5.1.1.1 Small Molecule
- 5.1.1.2 Large Molecule
- 5.1.1.3 High-Potency API (HPAPI)
- 5.1.2 FDF Development and Manufacturing
- 5.1.2.1 Solid Dose
- 5.1.2.2 Liquid Dose
- 5.1.2.3 Injectable Dose
- 5.1.3 Secondary Packaging
- 5.1.1 API Manufacturing
- 5.2 By Drug Molecule Type
- 5.2.1 Small Molecule
- 5.2.2 Biologics
- 5.2.3 Advanced Therapies (Cell and Gene)
- 5.3 By Scale of Operation
- 5.3.1 Clinical-Phase Manufacturing
- 5.3.2 Commercial-Scale Manufacturing
- 5.4 By End User
- 5.4.1 Big Pharma
- 5.4.2 Generic Pharma
- 5.4.3 Emerging / Virtual Biotech
- 5.4.4 Specialty Pharma
- 5.5 By Therapeutic Area
- 5.5.1 Oncology
- 5.5.2 Cardiovascular
- 5.5.3 Central Nervous System (CNS)
- 5.5.4 Infectious Disease
- 5.5.5 Other Therapeutic Areas
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Relative Positioning Analysis
- 6.4 Market Share Analysis
- 6.5 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.5.1 Catalent Inc.
- 6.5.2 Thermo Fisher Scientific Inc. (Patheon)
- 6.5.3 Lonza Group AG
- 6.5.4 Pfizer CentreOne (Pfizer Inc.)
- 6.5.5 Baxter International Inc. (BioPharma Solutions)
- 6.5.6 AbbVie Contract Manufacturing (AbbVie Inc.)
- 6.5.7 Recipharm AB
- 6.5.8 Jubilant Pharmova Limited
- 6.5.9 Boehringer Ingelheim BioXcellence
- 6.5.10 Aenova Group GmbH
- 6.5.11 Siegfried Holding AG
- 6.5.12 Samsung Biologics Co., Ltd.
- 6.5.13 FUJIFILM Diosynth Biotechnologies USA Inc.
- 6.5.14 Cambrex Corporation
- 6.5.15 Alcami Corporation Inc.
- 6.5.16 PCI Pharma Services
- 6.5.17 Ajinomoto Bio-Pharma Services
- 6.5.18 Emergent BioSolutions Inc.
- 6.5.19 Vetter Pharma-Fertigung GmbH & Co. KG
- 6.5.20 Grand River Aseptic Manufacturing Inc.
- 6.5.21 Curia Global Inc.
- 6.5.22 National Resilience Inc.
- 6.5.23 Avid Bioservices Inc.
- 6.5.24 KBI Biopharma Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


