

|
시장보고서
상품코드
2124225
인도네시아의 연포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Indonesia Flexible Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
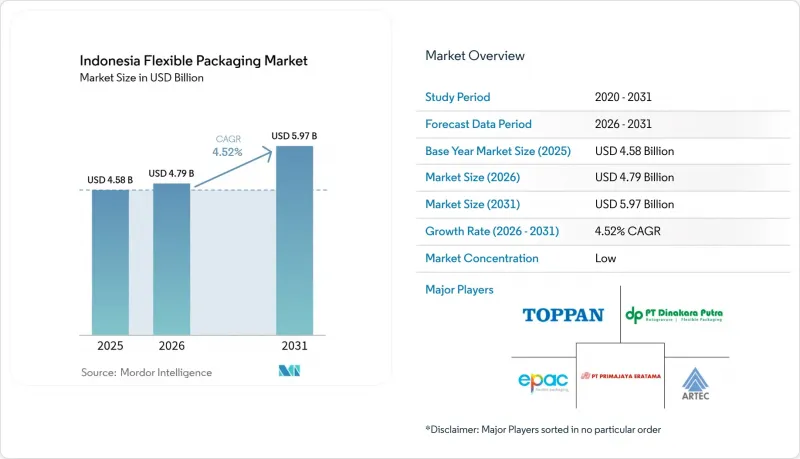
에 의하면, 인도네시아의 연포장 시장 규모는 2025년에 45억 8,000만 달러로 평가되었고, 2026년 47억 9,000만 달러에서 2031년까지 59억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.52%를 나타낼 전망입니다.
본 보고서는 소재별(종이, 플라스틱, 금속박, 바이오플라스틱·퇴비화 가능한 소재), 제품 유형별(백·파우치, 필름·랩, 기타), 최종 사용자 산업별(식품, 음료, 의료 및 의약품, 기타), 인쇄 기술별(플렉소 인쇄, 그라비아 인쇄, 디지털 인쇄, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도네시아의 연포장 시장 동향 및 인사이트
포장 식품 및 음료 소비의 급증
2024년, 포장 식품은 국내총생산(GDP)의 6.47%를 차지했습니다. 인도네시아 식음료 사업자 협회는 도시 지역 가구가 즉석 식품이나 고급 스낵을 선호하는 경향이 있어 이 비중이 더욱 상승할 것으로 예측했습니다. 2024년 10월에 도입된 할랄 표시 의무화로 인해 선명하고 내구성이 뛰어난 인쇄가 요구되고 있으며, 각 브랜드는 인도네시아의 높은 습도와 수많은 섬으로 구성된 공급망 전반에 걸쳐 제품 품질을 유지할 수 있는 고차단성 다층 필름을 채택하고 있습니다. 수입된 특산 식품과 가처분 소득 증가 또한 고급 보호 구조에 대한 수요를 더욱 부추기고 있습니다. 이러한 배경으로, 고도의 산소·수분 차단 필름을 제공하는 컨버터 기업들은 유제품, 육류, 과자류 가공업체로부터 수주를 늘리고 있습니다. 인도네시아의 연질 포장 시장은 이러한 꾸준한 수량 증가와 진열에 적합한 스탠드업 파우치를 선호하는 현대적인 유통 채널로의 전환으로부터 직접적인 혜택을 받고 있습니다.
지속 가능한 포장 솔루션에 대한 수요 증가
2025년에 시행될 EPR 규정은 생산자에게 2029년까지 소비 후 플라스틱 폐기물을 30% 감축할 것을 요구하고 있으며, 이로 인해 재활용 가능한 단일 소재 필름 및 인증된 퇴비화 가능 소재에 대한 투자가 촉진되고 있습니다. 현지 스타트업인 Greenhope와 Biopac은 PHA 및 전분 기반 필름의 생산 규모를 확대하고 있는 반면, 다논 인도네시아와 같은 다국적 기업들은 이미 PET 병에 25%의 재활용 소재를 사용하고 있어 식품용 rPET 수요를 견인하고 있습니다. 환경적 노력을 강조하고자 하는 브랜드들은 현재, 차단 성능을 유지하면서도 사용 후 처리를 간소화하는 ‘드롭인’ 기재를 지정하고 있습니다. 그 결과, 인도네시아의 연포장 시장에서는 아시아 및 수출 시장의 재활용 기준을 충족하는 필름에 대한 수주가 호조를 보이고 있습니다.
폴리올레핀 원료 가격 변동
저렴한 수입품으로 인해 국내 원료의 경쟁력이 저하되면서, 2024년 초에는 국내 업스트림 부문의 가동률이 55% 미만으로 떨어졌습니다. 수지의 현물 가격이 전월 대비 15% 이상 변동함에 따라, 컨버터는 비용을 확실하게 헤지할 수 없어 고정 가격 포장 계약의 이익률이 압박받고 있습니다. 제안된 반덤핑 관세로 인해 국내 공급은 안정될 가능성이 있습니다. 그러나 국내 크래커가 생산량을 늘리거나 수입 할당량이 축소될 때까지는 불확실성이 지속될 것으로 보입니다. 그 결과, 인도네시아의 연질 포장 시장에서는 견조한 최종 수요가 있음에도 불구하고 생산 능력 확대는 신중한 속도로 진행되고 있습니다.
부문 분석
플라스틱은 비용 효율성과 뛰어난 방습 특성 덕분에 2025년에도 매출 점유율 67.61%를 유지하며 인도네시아 연질 포장 시장의 기반을 이루고 있습니다. 폴리에틸렌(PE)과 폴리프로필렌(PP) 필름은 스낵, 냉동 식품, 농업 용도에서 여전히 필수적이지만, PE 60만 5,000톤과 PP 59만 9,000톤에 달하는 수입 의존도가 가격 안정을 저해하고 있습니다. 바이오플라스틱과 퇴비화 가능한 소재는 시작 규모는 작지만, EPR(확대 생산자 책임) 기한이 다가오는 가운데 연평균 성장률(CAGR) 7.45%로 가장 높은 성장세를 기록하고 있습니다.
경쟁사들의 대응 사례로는 Greenhope의 PHA 기반 필름이나 퇴비화 기준을 준수한 Biopac의 전분 혼합 제품 등을 들 수 있습니다. 브랜드 소유주들은 기계적 강도를 유지하면서 재활용을 간소화하는 단일 소재 PE 라미네이트를 시범적으로 도입하고 있습니다. 생분해성 폴리머 공장에 대한 정부의 장려책으로 인해, 현재의 비용 프리미엄에도 불구하고 2031년까지 인도네시아 연포장 시장 내 대체 기판의 규모는 계속 확대될 전망입니다.
2025년, 인도네시아 연포장 시장 규모 중 봉지와 파우치가 46.88%를 차지했습니다. 이는 식품, 퍼스널케어, 농약 각 제품 라인에서 높은 범용성을 갖추고 있기 때문입니다. 스탠드업형, 지퍼, 주입구는 현대 소매 환경에서 편의성과 진열 매력을 높이고 있습니다. 필름과 랩은 육류 가공 및 원예 산업에 활용되고 있는 반면, 라벨은 프리미엄 브랜딩 예산을 확보하고 있습니다.
연평균 성장률(CAGR) 6.35%로 확대되고 있는 소형 봉지와 스틱팩은 군도 국가 시장에서 합리적인 가격과 시제품에 대한 수요를 충족시키고 있습니다. 디지털 인쇄기를 통해 금형을 변경하지 않고도 지역별 고유 언어나 명절 디자인을 적용할 수 있게 되어, 제품 출시까지의 주기를 며칠로 단축하고 있습니다. 일회용 플라스틱에 대한 규제 당국의 감시가 강화됨에 따라, 각 변환 업체들은 리필용 파우치와 재활용 가능한 라미네이트 구조를 제안하며, 소형 포장의 편의성과 환경 규제 준수의 균형을 맞추고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the Indonesia flexible packaging market size was valued at USD 4.58 billion in 2025 and estimated to grow from USD 4.79 billion in 2026 to reach USD 5.97 billion by 2031, at a CAGR of 4.52% during the forecast period (2026-2031).
This report is Segmented by Material (Paper, Plastic, Metal Foil, Bioplastics and Compostable Materials), Product Type (Bags and Pouches, Films and Wraps, and More), End-User Industry (Food, Beverage, Healthcare and Pharmaceutical, and More), Printing Technology (Flexography, Rotogravure, Digital Printing, and More). The Market Forecasts are Provided in Terms of Value (USD).
Indonesia Flexible Packaging Market Trends and Insights
Surging Packaged Food and Beverage Consumption
Packaged foods contributed 6.47% to national GDP in 2024, a share the Indonesian Association of Food and Beverage Entrepreneurs expects to rise as urban households favor ready-to-eat meals and premium snacks. Mandatory halal labels introduced in October 2024 require clear, durable printing, pushing brands toward high-barrier multi-layer films that preserve product integrity across Indonesia's humid, multi-island supply chain. Imported specialty foods and rising disposable incomes further drive demand for premium protective structures. Against this backdrop, converters offering advanced oxygen- and moisture-barrier films are gaining orders from dairy, meat, and confectionery processors. The Indonesia flexible packaging market benefits directly from this steady volume growth and the shift to modern trade channels that prefer merchandisable stand-up pouches.
Accelerating Demand for Sustainable Packaging Solutions
EPR regulations effective 2025 require producers to cut post-consumer plastic waste by 30% by 2029, spurring investments in recyclable mono-material films and certified compostables. Local start-ups Greenhope and Biopac are scaling PHA- and starch-based films, while multinationals such as Danone Indonesia already use 25% recycled content in water bottles, creating pull-through for food-grade rPET. Brands seeking to signal their environmental credentials now specify drop-in substrates that maintain barrier performance while simplifying end-of-life handling. The Indonesian flexible packaging market, therefore, records strong order inflows for films that meet Asian and export-market recyclability standards.
Volatility in Polyolefin Raw Material Prices
Domestic upstream utilization fell below 55% in early 2024 after cheaper imports cut local feedstock competitiveness. Converters cannot reliably hedge costs because spot resin price swings exceed 15% month-on-month, compressing margins on fixed-price packaging contracts. Proposed anti-dumping duties may stabilize the domestic supply; however, uncertainty persists until local crackers increase output or import quotas are tightened. The Indonesia flexible packaging market therefore experiences cautious capacity expansions despite solid end-use demand.
Other drivers and restraints analyzed in the detailed report include:
- Growth of E-Commerce and Online Grocery Fulfilment
- Rising Urban Middle Class Driving Smaller Pack Sizes
- Inadequate Recycling Infrastructure and Collection Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics retained 67.61% revenue share in 2025 owing to cost efficiency and robust moisture-barrier properties, anchoring the Indonesia flexible packaging market. Polyethylene and polypropylene films remain integral to snacks, frozen food, and agricultural applications; however, import dependence for 605,000 t of PE and 599,000 t of PP limits price stability. Bioplastics and compostables, though starting from a smaller base, log the fastest 7.45% CAGR as EPR deadlines loom.
Competitive responses include PHA-based films by Greenhope and starch blends from Biopac that comply with compostability norms. Brand owners are trialing mono-material PE laminates that simplify recycling while maintaining mechanical strength. Government incentives for biodegradable polymer plants should keep the Indonesian flexible packaging market size for alternative substrates expanding through 2031 despite current cost premiums.
Bags and pouches commanded 46.88% of Indonesia flexible packaging market size in 2025, thanks to versatility across food, personal care, and agrochemical lines. Stand-up formats, zippers, and spouts enhance convenience and shelf appeal in modern retail. Films and wraps serve the meat processing and horticulture industries, whereas labels capture premium branding budgets.
Sachets and stick packs, advancing at 6.35% CAGR, address affordability and sampling needs across archipelagic markets. Digital presses enable region-specific languages and holiday designs without altering tooling, trimming launch cycles to days. Regulatory scrutiny of single-use plastics prompts converters to propose refill pouches and recyclable laminate structures, striking a balance between small-format convenience and environmental compliance.
Complete Report Scope:
- By Material
- Paper
- Plastic
- Metal Foil
- Bioplastics and Compostable Materials
- By Product Type
- Bags and Pouches
- Films and Wraps
- Sachets and Stick Packs
- Labels and Sleeves
- BY End-user Industry
- Food
- Baked Goods
- Snacks
- Meat, Poultry and Seafood
- Confectionery
- Pet Food
- Other Food Products
- Beverage
- Healthcare and Pharmaceutical
- Personal Care and Cosmetics
- Agriculture and Horticulture
- Other End-Use Industries
- Food
- By Printing Technology
- Flexography
- Rotogravure
- Digital Printing
- Other Printing Technologies
List of Companies Covered in this Report:
- Amcor plc
- Mondi plc
- PT Trias Sentosa Tbk
- PT Indopoly Swakarsa Industry Tbk
- PT Argha Prima Industry Tbk
- Sealed Air Corporation
- Huhtamaki Oyj
- PT Primajaya Eratama
- PT ePac Flexibles Indonesia
- PT Indonesia Toppan Printing
- PT Dinakara Putra
- PT Artec Package Indonesia
- PT Lotte Packaging
- PT Karuniatama Polypack
- PT Masplast Poly Film
- PT Polidayaguna Perkasa
- Constantia Flexibles Group GmbH
- UFlex Limited
- Sonoco Products Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Packaged Food and Beverage Consumption
- 4.2.2 Accelerating Demand for Sustainable Packaging Solutions
- 4.2.3 Growth of E-Commerce and Online Grocery Fulfilment
- 4.2.4 Rising Urban Middle Class Driving Smaller Pack Sizes
- 4.2.5 Rapid Adoption of Digital and Flexographic Short-Run Printing
- 4.2.6 Venture-Backed FMCG Startups Scaling Flexible Formats
- 4.3 Market Restraints
- 4.3.1 Volatility in Polyolefin Raw Material Prices
- 4.3.2 Inadequate Recycling Infrastructure AND Collection Systems
- 4.3.3 Escalating Environmental Regulations on Single-Use Plastics
- 4.3.4 High Inter-Island Logistics Costs Limiting Barrier Film Uptake
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Impact of Macroeconomic Factors on the Market
- 4.7 Regulatory Landscape and Recycling Policies in Indonesia
- 4.8 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Paper
- 5.1.2 Plastic
- 5.1.3 Metal Foil
- 5.1.4 Bioplastics and Compostable Materials
- 5.2 By Product Type
- 5.2.1 Bags and Pouches
- 5.2.2 Films and Wraps
- 5.2.3 Sachets and Stick Packs
- 5.2.4 Labels and Sleeves
- 5.3 BY End-user Industry
- 5.3.1 Food
- 5.3.1.1 Baked Goods
- 5.3.1.2 Snacks
- 5.3.1.3 Meat, Poultry and Seafood
- 5.3.1.4 Confectionery
- 5.3.1.5 Pet Food
- 5.3.1.6 Other Food Products
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceutical
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 Agriculture and Horticulture
- 5.3.6 Other End-Use Industries
- 5.3.1 Food
- 5.4 By Printing Technology
- 5.4.1 Flexography
- 5.4.2 Rotogravure
- 5.4.3 Digital Printing
- 5.4.4 Other Printing Technologies
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products AND Services, AND Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi plc
- 6.4.3 PT Trias Sentosa Tbk
- 6.4.4 PT Indopoly Swakarsa Industry Tbk
- 6.4.5 PT Argha Prima Industry Tbk
- 6.4.6 Sealed Air Corporation
- 6.4.7 Huhtamaki Oyj
- 6.4.8 PT Primajaya Eratama
- 6.4.9 PT ePac Flexibles Indonesia
- 6.4.10 PT Indonesia Toppan Printing
- 6.4.11 PT Dinakara Putra
- 6.4.12 PT Artec Package Indonesia
- 6.4.13 PT Lotte Packaging
- 6.4.14 PT Karuniatama Polypack
- 6.4.15 PT Masplast Poly Film
- 6.4.16 PT Polidayaguna Perkasa
- 6.4.17 Constantia Flexibles Group GmbH
- 6.4.18 UFlex Limited
- 6.4.19 Sonoco Products Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


