

|
시장보고서
상품코드
2124664
유럽, 중동 및 아프리카의 연포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe, Middle East And Africa (EMEA) Flexible Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
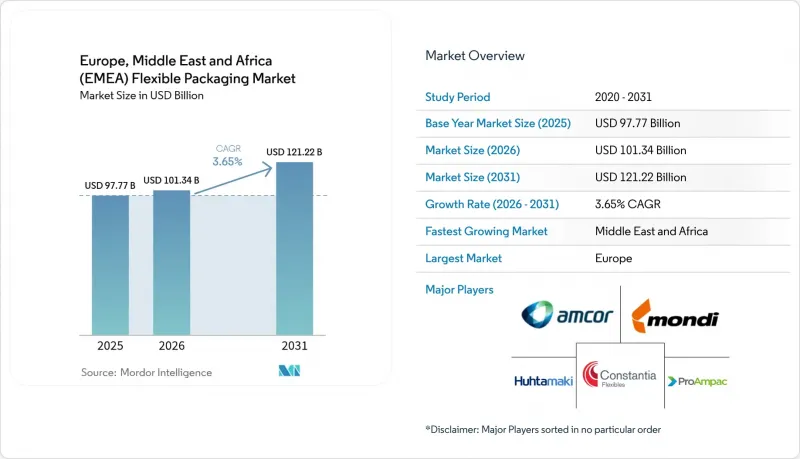
에 의하면, 2026년 유럽, 중동 및 아프리카(EMEA)의 연포장 시장 규모는 1,013억 4,000만 달러로 추정되고, 2025년 977억 7,000만 달러에서 확대해, 2031년에는 1,212억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 3.65%를 나타낼 전망입니다.
본 보고서는 소재별(플라스틱, 종이 등), 제품 유형별(봉지·파우치, 필름·랩 등), 최종 사용자 산업별(식품, 음료 등), 인쇄 기술별(플렉소 인쇄, 그라비아 인쇄 등), 지역별(유럽, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽·중동 및 아프리카(EMEA)의 연포장 시장 동향 및 인사이트
가공식품 및 편의식품 수요의 꾸준한 증가
도시로의 인구 이동으로 식습관이 변화함에 따라, 소매업체와 외식업체는 긴 유통 주기에도 신선도를 유지할 수 있는 가볍고 상온 보관이 가능한 포장을 선호하는 추세입니다. 비용 효율이 뛰어난 봉지나 파우치가 경질 포장을 대체하며, 운송비와 CO2 배출량을 줄이고 있습니다. 각 변환업체들은 ProAmpac사의 ‘RotiBag’과 같은 ‘그랩 앤 고(그랩 앤 고)’ 디자인을 도입하고 있습니다. 이는 외부 상자 없이도 따뜻한 식품을 운반할 수 있는 누출 방지 기능을 갖춘 포맷입니다. HACCP 및 ISO 22000 준수와 더불어 이러한 성능 향상으로 인해, EMEA 지역의 연포장 시장 전반에서 필름 기판 및 지퍼형 밀봉재에 대한 기본 수요가 증가하고 있습니다.
재활용 가능하고 지속 가능한 포장을 위한 규제 추진
EU의 ‘포장 및 포장 폐기물에 관한 규정(2025/40)’은 2030년까지 재활용 가능 소재의 함유율을 65%로 할 것을 의무화하고, PFAS 계열 배리어 화학물질의 사용을 금지하고 있어, 이로 인해 기존의 다층 라미네이트에 대한 광범위한 재설계가 촉진되고 있습니다. 현재 연구개발 센터에서는 산소 및 수증기 차단성을 유지하면서 기계적 회수가 가능한 상용화제를 이용한 단일 PE 또는 단일 PP 구조를 우선적으로 개발하고 있습니다. BASF의 퇴비화 가능한 코팅과 Sudpack의 화학적 재활용 폴리아미드 층은 혁신이 PPWR의 이정표와 어떻게 부합하는지를 보여줍니다. 브랜드 소유주들은 EU 수준의 규정 준수에 따라 세계 SKU를 표준화하고 있으며, 이로 인해 바이오플라스틱 공급업체와 섬유 기반 가공업체들은 EMEA 지역의 연포장 시장에서 새로운 시장 점유율 확대 기회를 얻고 있습니다.
폴리머 수지 가격 변동
원유 가격 변동과 유럽의 에너지 요금 체계 급등으로 인해 PE 및 PP 등급의 원자재 비용이 왜곡되고 있으며, 각 변환 업체들은 분기마다 고객과의 계약을 재협상할 수밖에 없는 상황에 처해 있습니다. 수직 통합형 기업은 수년에 걸친 원자재 조달 계약을 통해 리스크를 헤지하고 있지만, 중소규모 기업들은 이익률 하락에 직면하고 있으며, 그 결과 새로운 프레스 기계나 리와인더에 대한 설비 투자가 위축되고 있습니다. 이러한 영향으로 EMEA 지역의 연포장 시장에서 가격에 민감한 분야에서는 설비 교체 주기가 둔화되고, 혁신 도입이 지연되고 있습니다.
부문 분석
2025년, 플라스틱은 비용 면에서의 우위, 높은 기계적 강도, 그리고 확립된 공급망을 강점으로 삼아 EMEA 지역의 연포장 시장에서 67.35%의 점유율을 유지했습니다. 그러나 규제 강화와 브랜드의 재생 가능 소재에 대한 노력으로 인해 바이오플라스틱과 퇴비화 가능한 소재가 탄력을 받고 있으며, 연평균 성장률(CAGR) 4.88%로 확대되고 있습니다. AIMPLAS의 ‘폐기물 유래 PHA’ 이니셔티브 등 EU가 자금을 지원하는 시범 사업은 규모 확대에 따른 위험을 완화하는 제도적 지원을 보여주고 있습니다. 현재 각 컨버터 기업들은 기존의 LDPE 외에도 해조류 유래, PHA 또는 PLA 필름용 압출 라인을 병행하여 가동하고 있습니다. 이는 규정 준수 위험을 헤지하면서 조기 도입 브랜드에 대응하는 ‘듀얼 트랙’ 접근 방식입니다. EMEA 지역의 바이오 소재를 사용한 연포장 시장 규모는 2031년까지 52억 8,000만 달러를 돌파할 전망이며, 이러한 대폭적인 시장 점유율 확대는 공급망의 집적화와 퇴비화 가능 로고에 대한 소비자 인지도 향상에 힘입은 것입니다.
성능 저하를 방지하기 위해 하이브리드 라미네이트에는 화학적으로 재활용된 PP와 버진 소재를 포함하지 않는 PET 타이 층이 배합되어 있어, 재활용 소재 함유율 기준과 박막화라는 목표 모두를 달성하고 있습니다. PPWR(플라스틱 폐기물 규정)에 따라 EU가 승인한 프로토콜을 통해 재활용 가능성을 입증할 책임이 컨버터에게 부과되고 있기 때문에 이러한 혁신은 시의적절하다고 할 수 있습니다. 이는 플라스틱 업계의 기존 기업들이 넘어야 할 규정 준수 장벽이며, 이를 극복하지 못하면 신흥 셀룰로오스 기반 웹 제품들에게 시장 점유율을 빼앗기게 될 것입니다.
2025년에도 봉지와 파우치는 EMEA 지역의 연포장 시장 규모의 47.05%를 차지했으며, 시리얼에서 세제에 이르기까지 폭넓은 용도에 대응할 수 있는 범용성을 바탕으로 그 입지를 확고히 하고 있습니다. 그러나 향낭과 스틱 팩은 1회용 커피, 전해질 파우더, 피부과용 크림 등 수요에 힘입어 2031년까지 연평균 성장률(CAGR) 4.43%라는 주목할 만한 성장세를 보이고 있습니다. 퍼스널케어 분야의 다국적 기업들은 정기 구독 박스 내에서 향이나 SPF 성분을 체험해 볼 수 있도록 디지털 인쇄된 사셰를 채택하고 있으며, 가변 그래픽을 활용하여 소셜 미디어에서의 참여를 촉진하고 있습니다. 이러한 형태는 진열 공간의 가치가 높은 편의점에서 재료 사용량이 적다는 장점을 효과적으로 활용하고 있습니다. IFFA 2025에서 전시된 식용 알긴산염 향낭은 2차 폐기물을 완전히 제거함으로써 그 가능성을 더욱 넓히고 있습니다.
정확한 분량 계량과 외출 시 사용을 원하는 소비자 수요는 과도한 섭취를 자제하도록 유도하는 각국의 영양 표시 제도와 부합합니다. 그 결과, EMEA 지역의 연포장 시장에서는 더 빠른 레인 카운터, 마이크로 천공 시스템, 배송 네트워크를 견딜 수 있는 기밀 에지 씰을 도입하기 위해 FFS(Form-Fill-Seal) 라인의 재구성이 진행되고 있습니다. 또한, 소형 파우치 채택은 의약품 콜드체인 요건과도 밀접한 관련이 있으며, 호일 배리어가 적용된 사면 밀봉 방식이 지역 간 운송 중에 흡습성이 있는 원료의약품(API)을 보호하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Europe, Middle East and Africa (EMEA) flexible packaging market size in 2026 is estimated at USD 101.34 billion, growing from 2025 value of USD 97.77 billion with 2031 projections showing USD 121.22 billion, growing at 3.65% CAGR over 2026-2031.
This report is Segmented by Material (Plastics, Paper, and More), Product Type (Bags and Pouches, Films and Wraps, and More), End-User Industry (Food, Beverage, and More), Printing Technology (Flexography, Rotogravure, and More), and Geography (Europe, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Europe, Middle East And Africa (EMEA) Flexible Packaging Market Trends and Insights
Steady Rise in Demand for Processed and Convenience Foods
Urban migration is reshaping meal habits, prompting retailers and foodservice operators to favor lightweight, shelf-stable packs that protect freshness during extended distribution cycles. Cost-effective bags and pouches displace rigid alternatives, lowering freight bills and CO2 footprints. Converters introduce grab-and-go designs such as ProAmpac's RotiBag, a leak-resistant format able to carry hot foods without outer cartons. Combined with HACCP and ISO 22000 compliance, these performance upgrades increase baseline volume for film substrates and zipper closures across the EMEA flexible packaging market.
Regulatory Push for Recyclable and Sustainable Packaging
The EU Packaging and Packaging Waste Regulation 2025/40 enforces 65% recyclable content by 2030 and bans PFAS barrier chemistries, triggering broad redesign of legacy multi-layer laminates. R&D centers now prioritize mono-PE or mono-PP structures with compatibilizers that preserve oxygen and moisture barrier while allowing mechanical recovery. BASF's compostable coatings and Sudpack's chemically recycled polyamide layers show how innovation is aligning with PPWR milestones. Brand owners standardize global SKUs around EU-level compliance, giving bioplastic suppliers and fiber-based converters new share-gain avenues in the EMEA flexible packaging market.
Volatility in Polymer Resin Prices
Crude-oil swings and Europe's higher energy tariff structure distort input costs for PE and PP grades, forcing converters to renegotiate customer contracts every quarter. Integrated players hedge exposure through multi-year feedstock deals, but small and mid-scale firms face margin erosion that curtails CapEx on new presses and rewinders. The net effect tempers replacement cycles and slows innovation adoption in price-sensitive portions of the EMEA flexible packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Lightweighting for Logistics-Cost Reduction
- Rapid E-commerce Growth Across EMEA
- Intensifying Competitive Landscape Squeezing Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics retained 67.35% of the EMEA flexible packaging market share in 2025, anchored by cost advantages, high mechanical strength and well-established supply chains. Yet bioplastics and compostables are gaining ground-advancing at 4.88% CAGR-because regulatory stringency and brand commitments lean toward renewable content. EU-funded pilots, such as AIMPLAS' PHA-from-waste initiative, illustrate institutional support that de-risks scale-up. Converters now run parallel extrusion lines for seaweed, PHA or PLA films alongside traditional LDPE, a dual-track approach that hedges compliance risks while servicing early-adopter brands. The EMEA flexible packaging market size for bio-based substrates is set to breach the USD 5.28 billion mark by 2031, a material share jump underpinned by supply-chain co-location and rising consumer visibility of compostability logos.
To prevent performance compromises, hybrid laminates blend chemically recycled PP with virgin-free PET tie layers, hitting both recycled-content quotas and downgauge objectives. Such innovations are timely because the PPWR places the onus on converters to prove recyclability through EU-accepted protocols-a compliance ceiling that plastics incumbents must clear or surrender share to emerging cellulosic webs.
Bags and pouches still dominated 47.05% of the EMEA flexible packaging market size in 2025, a position grounded in versatility from cereals to detergents. Yet sachets and stick packs are enjoying headline-grabbing momentum with a 4.43% CAGR through 2031, driven by single-serve coffee, electrolyte powders and dermatology creams. Personal-care multinationals deploy digitally printed sachets to trial scents or SPF formulas in subscription boxes, harnessing variable graphics to spark social media engagement. The format's low-material footprint slots neatly into convenience stores where shelf space commands a premium. Edible alginate sachets displayed at IFFA 2025 push the envelope further by erasing secondary waste streams altogether.
Consumer demand for precise dosing and on-the-go use aligns with national nutrition labeling schemes that discourage oversized servings. Consequently, the EMEA flexible packaging market is retooling form-fill-seal lines for faster lane counters, micro-perforation systems and hermetic edge seals that withstand courier networks. Sachet adoption also dovetails with cold-chain pharmaceutical requirements, where foil-barrier four-side seals protect hygroscopic APIs during regional transport.
Complete Report Scope:
- By Material
- Plastics
- Polyethylene (PE)
- Biaxially Oriented Polypropylene (BOPP)
- Cast Polypropylene (CPP)
- Other Plastics
- Paper
- Metal Foil
- Bioplastics and Compostable Materials
- Plastics
- By Product Type
- Bags and Pouches
- Films and Wraps
- Sachets and Stick Packs
- Other Product Types
- BY End-user Industry
- Food
- Baked Goods
- Snacks
- Meat, Poultry and Seafood
- Confectionery
- Pet Food
- Other Food Products
- Beverage
- Healthcare and Pharmaceutical
- Personal Care and Cosmetics
- Agriculture and Horticulture
- Other End-Use Industries
- Food
- By Printing Technology
- Flexography
- Rotogravure
- Digital Printing
- Other Printing Technologies
- By Geography
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- Europe
List of Companies Covered in this Report:
- Amcor plc
- Constantia Flexibles Group GmbH
- Mondi plc
- Huhtamaki Oyj
- ProAmpac Holdings Inc.
- Bischof + Klein SE & Co. KG
- Aluflexpack AG
- Bak Ambalaj Sanayi ve Ticaret A.S.
- Coveris Management GmbH
- Danaflex OOO
- Gualapack S.p.A.
- Wipak Oy
- SUDPACK Holding GmbH & Co. KG
- Schur Flexibles Holding Ges.m.b.H.
- ePac Holdings LLC
- Treofan Germany GmbH & Co. KG
- Cellografica Gerosa S.p.A.
- Flextrus AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Steady rise in demand for processed and convenience foods
- 4.2.2 Regulatory push for recyclable and sustainable packaging
- 4.2.3 Lightweighting for logistics cost reduction
- 4.2.4 Rapid e-commerce growth across EMEA
- 4.2.5 Expansion of pharma cold-chain requiring high-barrier laminates
- 4.2.6 Digital printing enabling low-MOQ, localized SKUs
- 4.3 Market Restraints
- 4.3.1 Volatility in polymer resin prices
- 4.3.2 Intensifying competitive landscape squeezing margins
- 4.3.3 Inadequate film-recycling infrastructure in MEA
- 4.3.4 Emerging PFAS and mineral-oil migration regulations
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Plastics
- 5.1.1.1 Polyethylene (PE)
- 5.1.1.2 Biaxially Oriented Polypropylene (BOPP)
- 5.1.1.3 Cast Polypropylene (CPP)
- 5.1.1.4 Other Plastics
- 5.1.2 Paper
- 5.1.3 Metal Foil
- 5.1.4 Bioplastics and Compostable Materials
- 5.1.1 Plastics
- 5.2 By Product Type
- 5.2.1 Bags and Pouches
- 5.2.2 Films and Wraps
- 5.2.3 Sachets and Stick Packs
- 5.2.4 Other Product Types
- 5.3 BY End-user Industry
- 5.3.1 Food
- 5.3.1.1 Baked Goods
- 5.3.1.2 Snacks
- 5.3.1.3 Meat, Poultry and Seafood
- 5.3.1.4 Confectionery
- 5.3.1.5 Pet Food
- 5.3.1.6 Other Food Products
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceutical
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 Agriculture and Horticulture
- 5.3.6 Other End-Use Industries
- 5.3.1 Food
- 5.4 By Printing Technology
- 5.4.1 Flexography
- 5.4.2 Rotogravure
- 5.4.3 Digital Printing
- 5.4.4 Other Printing Technologies
- 5.5 By Geography
- 5.5.1 Europe
- 5.5.1.1 United Kingdom
- 5.5.1.2 Germany
- 5.5.1.3 France
- 5.5.1.4 Italy
- 5.5.1.5 Spain
- 5.5.1.6 Rest of Europe
- 5.5.2 Middle East and Africa
- 5.5.2.1 Middle East
- 5.5.2.1.1 Saudi Arabia
- 5.5.2.1.2 United Arab Emirates
- 5.5.2.1.3 Turkey
- 5.5.2.1.4 Rest of Middle East
- 5.5.2.2 Africa
- 5.5.2.2.1 South Africa
- 5.5.2.2.2 Nigeria
- 5.5.2.2.3 Kenya
- 5.5.2.2.4 Rest of Africa
- 5.5.2.1 Middle East
- 5.5.1 Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amcor plc
- 6.4.2 Constantia Flexibles Group GmbH
- 6.4.3 Mondi plc
- 6.4.4 Huhtamaki Oyj
- 6.4.5 ProAmpac Holdings Inc.
- 6.4.6 Bischof + Klein SE & Co. KG
- 6.4.7 Aluflexpack AG
- 6.4.8 Bak Ambalaj Sanayi ve Ticaret A.S.
- 6.4.9 Coveris Management GmbH
- 6.4.10 Danaflex OOO
- 6.4.11 Gualapack S.p.A.
- 6.4.12 Wipak Oy
- 6.4.13 SUDPACK Holding GmbH & Co. KG
- 6.4.14 Schur Flexibles Holding Ges.m.b.H.
- 6.4.15 ePac Holdings LLC
- 6.4.16 Treofan Germany GmbH & Co. KG
- 6.4.17 Cellografica Gerosa S.p.A.
- 6.4.18 Flextrus AB
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


