|
시장보고서
상품코드
2124237
아시아태평양의 텔레매틱스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)APAC Telematics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
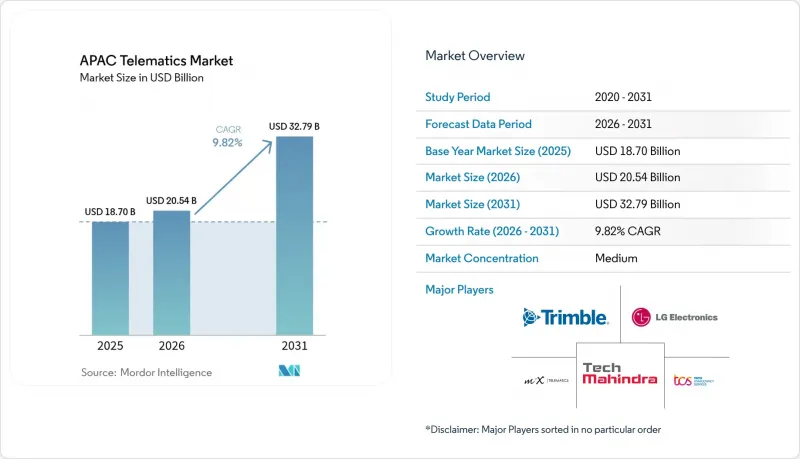
에 의하면, 아시아태평양의 텔레매틱스 시장 규모는 2025년에 187억 달러로 평가되었고, 2026년 205억 4,000만 달러에서 2031년까지 327억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.82%를 나타낼 전망입니다.
본 보고서는 차종별(소형 상용차, 중대형 상용차), 채널별(OEM 내장형, 애프터마켓(유선), 애프터마켓용 OBD-II 동글), 서비스 유형별(차량·자산 추적, 내비게이션 및 인포테인먼트, 기타), 통신 기술별(GNSS/GPS, 셀룰러 통신, 기타), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아시아태평양의 텔레매틱스 시장 동향 및 인사이트
OEM 탑재형 연결 모듈의 보급
출고 시 텔레매틱스 유닛의 탑재는 신규 상용차에서 점점 더 표준화되고 있으며, 2028년까지 탑재율은 94%에 달할 전망입니다. 중국 제조업체들은 국내 모바일 네트워크 사업자와 제휴하여 임베디드 SIM을 통합하고 있는 반면, 일본의 OEM 업체들은 Android Automotive OS를 채택하여 클라우드 네이티브 서비스를 제공합니다. 이러한 변화로 인해 규제 준수가 간소화되고, 무선 소프트웨어 업데이트가 가능해지며, 예기치 않은 가동 중지 시간을 줄여주는 예측 유지보수가 지원됩니다. 반면, 애프터마켓 벤더들은 차량 버스와의 더 깊은 통합을 요구하는 차량 운영업체들 수요가 늘어나면서, 이는 임베디드 하드웨어로만 구현 가능한 기능인 만큼 가격 면에서 압박을 받고 있습니다.
AIS-140 및 eCall 관련 규제 요건
인도 교통부는 AIS-140에 따라 모든 상용차에 GPS 추적 기능과 비상 버튼의 탑재를 의무화하고 있으며, 2026년 4월부터는 대형 승용차에 대해서도 긴급 제동 기능 및 졸음 운전 경고 기능을 적용 대상으로 확대할 예정입니다. 일본과 한국에서는 eCall이 도입되어 통일된 긴급 대응 능력이 추진되고 있습니다. 이러한 동향에 따라 플랫폼 공급업체는 지역 전체에 걸쳐 규정 준수 솔루션을 확대할 수 있게 되었지만, 기술 사양의 차이로 인해 여전히 모듈식 소프트웨어 아키텍처가 요구되고 있습니다.
사이버 보안 및 데이터 개인정보 보호에 대한 우려
차량 관리 사업자들은 원격 해킹이나 위치 정보·CAN 버스 데이터에 대한 무단 접근을 우려하고 있습니다. 아시아태평양의 일부 정부는 데이터 현지화에 관한 엄격한 규정을 시행하고 위반 시 벌칙을 부과하고 있어, 규정 준수 관련 예산이 증가하고 있습니다. 하드웨어 공급업체들은 현재 RoT(Root of Trust) 칩을 내장하고, 통신 사업자와 협력하여 종단 간암호화를 도입하고 있습니다. 또한, 이상 현상을 모니터링하고 신속한 패치 적용을 조정하기 위한 MSOC(Managed Security Operations Center) 서비스도 등장하고 있습니다.
부문 분석
2031년까지의 연평균 성장률(CAGR) 10.41%로 중대형 상용차(M/HCV) 부문이 가장 빠른 성장세를 보일 전망이지만, 2025년 시점에서는 아시아태평양 텔레매틱스 시장 점유율의 53.58%를 소형 상용차(LCV)가 차지했습니다. 장거리 트럭의 차량당 평균 수익이 높은 이유는 정밀 연료 분석, 브레이크 마모 예측, 비용이 많이 드는 도로변 검사를 줄여주는 규정 준수 모듈 덕분입니다. 한편, 소형 상용차 사업자들은 화물 안전 확보와 도시 지역 내 배송 효율화를 목적으로 저비용 GPS 추적을 우선시하고 있습니다. 인도에서 버스 및 트럭용 ADAS(첨단 운전자 지원 시스템) 규제가 도입되는 등 규제 측면의 움직임도 중형·대형 상용차(M/HCV)의 텔레매틱스 도입률을 더욱 높이고 있습니다. Platform Science가 2025년에 Trimble의 차량 관리 사업 부문을 인수한 사례에서 볼 수 있듯이, 플랫폼 통합은 ELD(전자 운전 기록 장치) 규정 준수 및 배터리 상태 대시보드를 아우르는 통합형 솔루션이 향후 성장을 주도할 것임을 시사합니다.
M/HCV의 전동화 프로젝트에서는 주행 거리 연장 및 충전 시간대 최적화를 도모하기 위해 텔레매틱스의 동시 도입이 필수적입니다. EC(전자상거래)의 서비스 수준 계약(SLA)에 쫓기는 LCV 플릿 관리자는 사고율을 낮추기 위해 카메라 기반 운전 행동 분석을 도입하고 있습니다. 도입 대수 전체의 대부분은 여전히 LCV가 차지하고 있지만, 구독형 분석 플랫폼과 결합된 기능이 풍부한 솔루션 덕분에 매출 점유율은 M/HCV 쪽으로 기울고 있습니다. 따라서 이러한 부문 간의 상호 작용이 하드웨어 OEM 및 플랫폼 제공업체의 차별화된 시장 진출 전략을 형성하고 있습니다.
2025년에도 OEM 내장형 유닛은 매출 점유율 41.89%를 유지했지만, 애프터마켓용 OBD-II 동글은 연평균 성장률(CAGR) 10.02%의 속도로 성장하고 있습니다. 비용에 민감한 차량 운용 사업자의 경우, 자체 설치가 용이하고 보증을 잃지 않고 공급업체를 변경할 수 있는 점을 중요하게 여깁니다. 대조적으로, 내장형 모듈은 차량 버스와 더욱 깊은 통합을 실현하며, 무선 펌웨어 다운로드 및 공장 출하 시 진단 기능을 지원합니다. 각 OEM 업체들은 타사 소프트웨어 플랫폼을 위해 API를 점점 더 개방하고 있어, 유연성 면에서 기존 모델과의 격차를 좁히고 하이브리드형 배포 모델을 촉진하고 있습니다.
인증된 애프터마켓 장치는 구형 차량의 개조나 인도의 AIS-140 규격 대응에 있어 여전히 매우 중요한 역할을 하고 있습니다. 유선 연결 방식의 블랙박스는 변조 방지 기록이나 위성 통신을 통한 페일오버가 필요한 차량 함대에 활용되고 있습니다. 클라우드 네이티브 텔레매틱스 공급업체는 임베디드형과 애프터마켓형 데이터 스트림을 모두 통합하는 통합 대시보드를 제공함으로써 채널 간의 격차를 해소하고 있습니다. 2026년 이후 5G 모뎀이 표준화됨에 따라 공급업체들은 하드웨어 업데이트 주기가 가속화될 것으로 예상하고 있으며, 자본 투자를 최소화한 구독형 패키지가 소규모 사업자의 도입을 촉진할 것으로 전망됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the APAC telematics market size was valued at USD 18.70 billion in 2025 and estimated to grow from USD 20.54 billion in 2026 to reach USD 32.79 billion by 2031, at a CAGR of 9.82% during the forecast period (2026-2031).
This report is Segmented by Vehicle Type (Light Commercial Vehicles, Medium and Heavy Commercial Vehicles), Channel (OEM-Embedded, Aftermarket Hard-Wired, Aftermarket OBD-II Dongle), Service Type (Fleet/Asset Tracking, Navigation and Infotainment, and More), Communication Technology (GNSS/GPS, Cellular, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
APAC Telematics Market Trends and Insights
Proliferation of OEM-installed connectivity modules
Factory-fitted telematics units are increasingly standard across new commercial vehicles as attach rates rise toward 94% by 2028. Chinese manufacturers collaborate with domestic mobile-network operators to integrate embedded SIMs, while Japanese OEMs layer Android Automotive OS to deliver cloud-native services. The shift simplifies regulatory compliance, enables over-the-air software updates, and supports predictive maintenance that cuts unplanned downtime. Aftermarket vendors face pricing pressure as fleets favor deeper vehicle-bus integration that only embedded hardware can provide.
Regulatory mandates on AIS-140 and eCall
India's transport ministry requires GPS tracking and panic buttons under AIS-140 for all commercial vehicles, and from April 2026, will extend emergency braking and drowsiness warnings to larger passenger vehicles. Japan and South Korea have rolled out eCall, driving uniform emergency-response capabilities. This convergence allows platform vendors to scale compliance solutions region-wide, though varying technical formats still demand modular software architectures.
Cyber-security and data-privacy concerns
Fleet operators worry about remote hacking and unauthorized access to location or CAN bus data. Several APAC governments enforce strict rules on data localization and impose penalties for breaches, raising compliance budgets. Hardware vendors now integrate root-of-trust chips and collaborate with telecom carriers to deploy end-to-end encryption. Managed security operations center services are also emerging to monitor anomalies and coordinate rapid patching .
Other drivers and restraints analyzed in the detailed report include:
- Rising demand for usage-based insurance (UBI)
- Growth of e-commerce last-mile fleets
- Semiconductor supply-chain volatility post-2025
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Medium and Heavy Commercial Vehicles account for the fastest expansion at 10.41% CAGR to 2031, whereas Light Commercial Vehicles held 53.58% of the APAC telematics market share in 2025. The higher average revenue per installed unit on long-haul trucks comes from advanced fuel analytics, brake-wear prediction, and compliance modules that reduce costly roadside inspections. Conversely, LCV operators prioritize low-cost GPS tracking to safeguard parcels and streamline urban drops. Regulatory momentum, such as India's incoming ADAS rules for buses and trucks, further lifts M/HCV penetration. Platform consolidation, evident in Platform Science's 2025 acquisition of Trimble's fleet unit, signals that integrated offerings spanning ELD compliance and battery-health dashboards will dominate future growth.
M/HCV electrification projects necessitate concurrent telematics deployment to extend driving range and optimize charging windows. LCV fleet managers, pressed by e-commerce service-level agreements, adopt camera-based driver-behavior analytics to cut accident rates. Although the overall installed-base majority remains within LCVs, revenue share tilts toward M/HCVs because of feature-rich solutions bundled with subscription analytics platforms. The segment interplay, therefore, shapes differentiated go-to-market strategies for hardware OEMs and platform providers.
OEM-embedded units retained 41.89% revenue share in 2025, yet Aftermarket OBD-II dongles are on pace for 10.02% CAGR. Cost-conscious fleets value the ease of self-installation and the ability to switch vendors without forfeiting warranties. In contrast, embedded modules offer deeper vehicle-bus integration that supports over-the-air firmware downloads and factory-grade diagnostics. OEMs increasingly open APIs to third-party software platforms, narrowing the historical gap in flexibility and encouraging hybrid deployment models.
Certified aftermarket devices remain pivotal for retrofitting older assets and meeting AIS-140 in India. Hard-wired black boxes serve fleets demanding tamper-proof records or satellite fallback. Cloud-native telematics vendors bridge the channel divide by delivering a unified dashboard that ingests both embedded and aftermarket data streams. As 5G modems become standard from 2026 onward, vendors expect hardware refresh cycles to accelerate, allowing capex-light subscription bundles to spur adoption among small operators.
Complete Report Scope:
- By Vehicle Type
- Light Commercial Vehicles (LCV)
- Medium and Heavy Commercial Vehicles (M/HCV)
- By Channel
- OEM-embedded
- Aftermarket Hard-wired
- Aftermarket OBD-II Dongle
- By Service Type
- Fleet/Asset Tracking
- Navigation and Infotainment
- Remote Diagnostics
- Safety and Security (eCall, SVR)
- Insurance Telematics (UBI/PAYD)
- By Communication Technology
- GNSS/GPS
- Cellular (2G/3G/4G/5G)
- Satellite-based
- DSRC/C-V2X
- By Country
- China
- Japan
- South Korea
- India
- Australia and New Zealand
- South-East Asia (Indonesia, Thailand, Malaysia, Singapore, Vietnam, Philippines)
List of Companies Covered in this Report:
- LG Electronics Inc.
- Tata Consultancy Services Limited (TCS)
- MiX Telematics India Private Limited (Powerfleet)
- Trimble Inc.
- Tech Mahindra Limited
- Octo Telematics Ltd.
- Meitrack Group
- Concox (Shenzhen Jimi IoT Co., Ltd.)
- Arya Omnitalk Wireless Solutions Private Limited
- Asia Mobiliti Sdn. Bhd.
- Efkon India Private Limited
- Geotab Inc.
- CalAmp Corp.
- SinoTrack Group Limited
- Teltonika IoT Group
- Bosch Mobility Platform and Solutions India Private Limited
- Harman International Industries, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of OEM-installed connectivity modules
- 4.2.2 Regulatory mandates on AIS-140 and eCall
- 4.2.3 Rising demand for usage-based insurance (UBI)
- 4.2.4 Growth of e-commerce last-mile fleets
- 4.2.5 Smart-city ITS pilots driving data partnerships
- 4.2.6 OEM-fintech leasing models bundling telematics
- 4.3 Market Restraints
- 4.3.1 Cyber-security and data-privacy concerns
- 4.3.2 High upfront hardware/communication cost
- 4.3.3 Fragmented interoperability standards
- 4.3.4 Semiconductor supply-chain volatility post-2025
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Industry
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Vehicle Type
- 5.1.1 Light Commercial Vehicles (LCV)
- 5.1.2 Medium and Heavy Commercial Vehicles (M/HCV)
- 5.2 By Channel
- 5.2.1 OEM-embedded
- 5.2.2 Aftermarket Hard-wired
- 5.2.3 Aftermarket OBD-II Dongle
- 5.3 By Service Type
- 5.3.1 Fleet/Asset Tracking
- 5.3.2 Navigation and Infotainment
- 5.3.3 Remote Diagnostics
- 5.3.4 Safety and Security (eCall, SVR)
- 5.3.5 Insurance Telematics (UBI/PAYD)
- 5.4 By Communication Technology
- 5.4.1 GNSS/GPS
- 5.4.2 Cellular (2G/3G/4G/5G)
- 5.4.3 Satellite-based
- 5.4.4 DSRC/C-V2X
- 5.5 By Country
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 South Korea
- 5.5.4 India
- 5.5.5 Australia and New Zealand
- 5.5.6 South-East Asia (Indonesia, Thailand, Malaysia, Singapore, Vietnam, Philippines)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 LG Electronics Inc.
- 6.4.2 Tata Consultancy Services Limited (TCS)
- 6.4.3 MiX Telematics India Private Limited (Powerfleet)
- 6.4.4 Trimble Inc.
- 6.4.5 Tech Mahindra Limited
- 6.4.6 Octo Telematics Ltd.
- 6.4.7 Meitrack Group
- 6.4.8 Concox (Shenzhen Jimi IoT Co., Ltd.)
- 6.4.9 Arya Omnitalk Wireless Solutions Private Limited
- 6.4.10 Asia Mobiliti Sdn. Bhd.
- 6.4.11 Efkon India Private Limited
- 6.4.12 Geotab Inc.
- 6.4.13 CalAmp Corp.
- 6.4.14 SinoTrack Group Limited
- 6.4.15 Teltonika IoT Group
- 6.4.16 Bosch Mobility Platform and Solutions India Private Limited
- 6.4.17 Harman International Industries, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment