

|
시장보고서
상품코드
2124582
베트남의 종이 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vietnam Paper Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
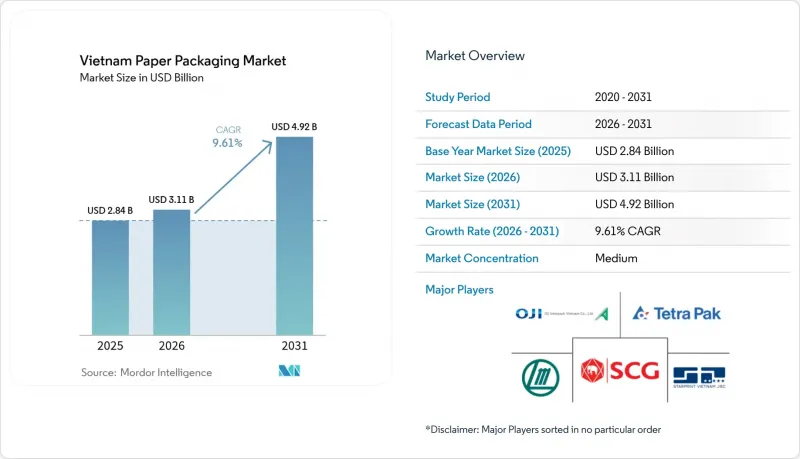
에 의하면, 베트남의 종이 포장 시장 규모는 2025년에 28억 4,000만 달러로 평가되었습니다. 2026년 31억 1,000만 달러에서 2031년까지 49억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 9.61%를 나타낼 전망입니다.
본 보고서는 등급(골판지 원지, 컨테이너보드), 제품(접이식 카톤, 골판지 상자·컨테이너 등), 최종 사용자 산업(식품, 음료, 헬스케어,가정용품, 전기 및 전자기기 등), 포장 형태(경질, 반경질, 성형 섬유 및 펄프 포장 제품 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
베트남의 종이 포장 시장 동향 및 인사이트
급증하는 전자상거래 소포 처리량
2024년, 국내 전자상거래 매출은 두 자릿수 성장률을 기록하며 호치민시, 하노이, 다낭 지역의 소포 총 유통량을 끌어올렸습니다. 이러한 증가로 인해 복합 운송 물류 체인을 견딜 수 있도록 설계된 골판지 배송 컨테이너에 대한 수요가 높아지고 있습니다. 2급 도시의 마이크로 풀필먼트 센터에서는 주문 경향이 소포 보관함이나 이륜차용 배송 랙에 들어갈 수 있는 소형 상자로 이동하고 있습니다. 베트남의 제221/QD-TTg호 결정은 물류가 GDP에 기여하는 비율을 9%-11%로 끌어올리겠다는 목표를 제시하고 있으며, 고속 분류를 위한 표준화된 포장 치수가 필요한 자동화 업그레이드를 촉진하고 있습니다. 2030년까지 스마트 물류 인프라에 투입될 50억 달러 규모의 설비 투자는 단기적인 처리량 안정성을 뒷받침하고 있습니다. 베트남의 종이 포장 시장은 이러한 소포 붐으로 인해 즉각적인 호재를 누리고 있습니다.
베트남으로의 FMCG 및 전자기기 급속한 오프쇼어링
2025년 신규 외국인 직접 투자(FDI)의 66% 이상이 가공 및 제조 분야로 유입되어, 북부와 남부의 산업 단지에서 운송에 적합한 골판지 상자에 대한 공장 차원 수요를 촉진했습니다. 9,000만 달러 규모의 하남 공장을 대표하는 스낵 식품 제조업체들은 100% 지속 가능한 조달 목표를 우선시하면서도 컨테이너 보드의 안정적인 수요를 뒷받침하고 있습니다. 중국에서 이전해 오는 전자기기 조립 제조업체들은 국제 품질 기준을 충족하는 정전기 방지 라이너,방습층, 화이트탑 크라프트 라이너를 지정하고 있습니다. 다국적 기업의 현지화 요구는 수입 의존도와 스코프 3 배출량을 줄이기 위해 국내 판지 생산을 촉진하고 있습니다. 그 결과, 베트남의 종이 포장 시장은 해외 공장의 가동 일정에 연동된 장기적인 수주를 확보하고 있습니다.
국내 버진 펄프의 구조적 부족과 수입 의존도
베트남에는 대규모의 지속 가능한 조림지가 부족하기 때문에 해당 국가의 제지 공장은 급증하는 크라프트 라이너 수요를 충족시킬 수 없습니다. 2023년 초, 포장용지 총 소비량은 28만 4,530톤에 달했으나, 수입량은 전월 대비 9.2% 증가하여 이러한 격차가 두드러지게 나타나고 있습니다. 환율 변동과 운임은 즉시 라이너보드 가격에 반영되어 가공업체의 이익률에 영향을 미치고 있습니다. 장섬유에 의존하는 고급 등급은 정기적으로 공급 부족에 직면하고 있어, 사용자들은 사양을 낮출 수밖에 없거나 할증료를 지불해야 합니다. 따라서 이러한 섬유 부족은 베트남의 종이 포장 시장에 구조적인 걸림돌이 되고 있습니다.
부문별 분석
2025년, 컨테이너 보드는 베트남의 종이 포장 시장 점유율의 57.18%를 차지했습니다. 이는 전 세계 해상 운송을 위해 견고한 골판지 심지에 의존하는 베트남의 수출 지향적 경제 구조를 반영한 것입니다. 화이트 탑 크라프트 라이너는 전자기기 산업 집적지에서 고가 시장을 차지하는 반면, 재생 플루팅은 국내 식품 및 음료 물류 수요를 충족시키고 있습니다. 세미케미컬 플루팅은 비용과 강도의 균형이 잘 잡혀 있어 구매자들의 관심을 끌고 있습니다. 카톤보드는 시장 규모는 작지만, 의약품 라벨 수요 증가와 소매용 디스플레이의 보급에 힘입어 2031년까지 연평균 성장률(CAGR) 11.13%로 성장을 지속하고 있습니다. 고형 표백 황산 펄프 및 접이식 상자용 판지는 다국적 FMCG 기업의 브랜드 차별화에 필수적인 고화질 표면을 제공합니다. 친환경 라벨이 구매 기준이 됨에 따라 코팅 재생 판지 및 비코팅 재생 판지에 대한 수요가 증가하고 있습니다. 테트라팩의 생산 능력 확대로 인해 생산량의 55%가 현지 바이어에게 공급되고 있으며, 이는 프리미엄 골판지 수요 증가에 대한 자신감을 보여줍니다.
베트남의 종이 포장 시장에서 컨테이너 보드 시장 규모는 산업단지의 창고 건설에 따라 꾸준히 확대될 것으로 전망됩니다. 한편, 종이 포장 시장 규모는 재활용률이 높고 경량 형태를 권장하는 규제 압력으로 인해 혜택을 볼 것으로 예측됩니다. 따라서 시장 포지션은 범용 라이너에서 특정 최종 용도나 소량 인쇄용으로 설계된 고부가가치 보드로 전환되고 있습니다.
2025년, 베트남의 종이 포장 시장 규모 중 골판지 상자 및 컨테이너가 50.12%를 차지했습니다. 이는 전자상거래(EC) 및 수출 운송이 출하량의 주류를 이루었기 때문입니다. 대규모 화주들은 해상 운송에서 내압성과 적재 효율의 균형이 잡힌 B플루트 및 C플루트 골판지 상자를 필요로 합니다. 2030년까지 50억 달러 규모의 스마트 물류 인프라가 구축됨에 따라 골판지 처리량은 계속해서 확보될 전망입니다. 한편, 헬스케어 및 퍼스널케어 브랜드들이 위조 방지 기능이나 매장 진열에 적합한 솔루션을 요구하는 가운데, 접이식 카톤 시장은 연평균 성장률(CAGR) 10.96%로 확대되고 있습니다. 디지털 인쇄에 대한 보조금으로 인해 카톤의 맞춤 제작이 가속화되고 있으며, 이는 프리미엄 가격 책정을 뒷받침하고 있습니다.
골판지의 두께를 얇게 만드는 기회는 펄프 공급이 안정될 때까지는 제한적입니다. 대조적으로, 종이 카톤의 경우 경량 코팅지 기재를 채택하여 재료 사용량을 최소화하고, 스코프 3 배출량 감축 목표에 부합하는 노력이 진행되고 있습니다. 접이식 골판지 상자의 형태에 통합된 성형 펄프 인서트는 제품의 차별화를 한층 더 강화하고 있습니다. 베트남의 종이 포장 시장은 대량 운송용 포장재에서 구조적 보호 기능과 판매 시점에서의 어필력을 겸비한 하이브리드 SKU로 진화를 거듭하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Vietnam paper packaging market size was valued at USD 2.84 billion in 2025 and estimated to grow from USD 3.11 billion in 2026 to reach USD 4.92 billion by 2031, at a CAGR of 9.61% during the forecast period (2026-2031).
This report is Segmented by Grade (Cartonboard, and Containerboard), Product (Folding Cartons, Corrugated Boxes and Containers, and More), End-User Industry (Food, Beverage, Healthcare, Household Care, Electrical and Electronics, and More), Packaging Format (Rigid, Semi-Rigid, Molded Fiber and Pulp Packaging Products, and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Paper Packaging Market Trends and Insights
Booming e-commerce parcel volumes
National e-commerce turnover rose at a double-digit pace in 2024, driving aggregate parcel flows across Ho Chi Minh City, Hanoi, and Da Nang. The uptick amplifies demand for corrugated shipping containers engineered to survive multimodal logistics chains. Micro-fulfillment centers in tier-2 cities are shifting order profiles toward smaller-format boxes that fit parcel lockers and two-wheeler delivery racks. Vietnam's Decision 221/QD-TTg targets a 9%-11% logistics GDP contribution, prompting automation upgrades that require standardized packaging dimensions for high-speed sortation. Capital spending of USD 5 billion earmarked for smart-logistics infrastructure through 2030 cements near-term volume visibility. The Vietnam paper packaging market gains immediate tailwinds from this parcel boom.
Rapid FMCG and electronics off-shoring into Vietnam
Over 66% of 2025's fresh FDI pledges flowed into processing and manufacturing, catalyzing plant-level demand for transport-worthy cartons in Northern and Southern industrial belts. Snack-food producers, exemplified by the USD 90 million Ha Nam facility, anchor steady containerboard pull-through while prioritizing 100% sustainable sourcing goals. Electronics assemblers relocating from China specify anti-static liners, moisture barriers, and white-top kraftliners that meet global quality codes. Localization mandates by multinational corporations promote in-country board production to cut import reliance and Scope-3 emissions. As a result, the Vietnam paper packaging market secures long-run orders tied to foreign plant commissioning schedules.
Structural shortfall of domestic virgin fiber; import dependence
Vietnam's mills cannot meet surging kraftliner demand because the country lacks large-scale, sustainable forestry plantations. In early 2023, total packaging-paper consumption hit 284,530 tons even as imports rose 9.2% month-on-month, underscoring the gap. Currency swings and freight costs translate quickly into linerboard prices, affecting converter margins. Premium grades that rely on long fiber face periodic shortages, forcing users to down-spec or pay surcharges. The fiber deficit, therefore, acts as a structural drag on the Vietnam paper packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Plastic phase-out regulations (EPR and DRS)
- Foreign brand owners' Scope-3 carbon cuts push lightweight recycled board
- Volatile recovered-paper import policy and quality controls
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Containerboard held 57.18% of the Vietnam paper packaging market share in 2025, a reflection of Vietnam's export-oriented profile that relies on robust corrugating medium for global shipping. White-top kraftliner commands premium pricing in electronics clusters, whereas recycled fluting satisfies domestic food-and-beverage logistics. Semi-chemical fluting attracts buyers, balancing cost and strength. Cartonboard, although smaller, records an 11.13% CAGR to 2031, propelled by rising pharmaceutical labeling needs and retail-ready displays. Solid bleached sulfate and folding boxboard deliver high-graphics surfaces essential for brand differentiation among multinational FMCG firms. Coated recycled board and uncoated recycled board gain traction as eco-labels become purchasing criteria. Tetra Pak's capacity boost dedicates 55% output to local buyers, signaling confidence in premium carton uptake.
The Vietnam paper packaging market size for containerboard is projected to rise steadily alongside warehouse construction in industrial parks. Meanwhile, the Vietnam paper packaging market size for cartonboard stands to benefit from regulatory pressure favoring lightweight formats with higher recycled content. Market positioning is thus shifting from commodity liner toward value-added board engineered for specific end uses and shorter print runs.
Corrugated Boxes and Containers accounted for 50.12% of the Vietnam paper packaging market size in 2025, as e-commerce and export shipping dominated volume patterns. Large shippers require B- and C-flute cases that strike a balance between crush resistance and stacking efficiency for sea freight. The rollout of USD 5 billion in smart-logistics infrastructure through 2030 ensures continued corrugated throughput. Folding cartons, however, are expanding at an 10.96% CAGR as healthcare and personal-care brands seek tamper-evident, shelf-ready solutions. Digital print subsidies accelerate carton customization, which supports premium pricing.
Down-gauge opportunities in corrugated remain limited until fiber supply stabilizes. In contrast, cartons utilize lightweight coated substrates to minimize material usage and align with Scope 3 emission targets. Molded pulp inserts integrated into folding-carton formats further differentiate offerings. The Vietnam paper packaging market is continuing to evolve from bulk shippers toward hybrid SKUs that combine structural protection with point-of-sale appeal.
Complete Report Scope:
- By Grade
- Cartonboard
- Solid Bleached Sulphate (SBS)
- Solid Unbleached Sulphate (SUS)
- Folding Boxboard (FBB)
- Coated Recycled Board (CRB)
- Uncoated Recycled Board (URB)
- Other Cartonboard Grades
- Containerboard
- White-top Kraftliner
- Other Kraftliners
- White-top Testliner
- Other Testliners
- Semi-chemical Fluting
- Recycled Fluting
- Other Grades
- Cartonboard
- By Product
- Folding Cartons
- Corrugated Boxes and Containers
- Other Products
- By End-User Industry
- Food
- Beverage
- Healthcare
- Personal Care
- Household Care
- Electrical and Electronics
- Other End-User Industries
- By Packaging Format
- Rigid (Corrugated, Solid Board)
- Semi-rigid (Folding Cartons excluding Solid Board Boxes)
- Flexible Paper (Sachets, Wraps)
- Molded Fiber and Pulp Packaging Products
List of Companies Covered in this Report:
- SONG LAM Trading & Packaging Production CO., Ltd
- Asia Pulp & Paper Group (APP)
- Tetra Pak International S.A.
- Oji Interpack Vietnam Co., Ltd
- Khang Thanh Manufacturing CO., LTD
- Hanh Packaging Co. Ltd
- SCG Paper Public Company Limited
- BINH MINH P.A.T CO.,LTD
- Kraft of Asia Paperboard & Packaging Co., Ltd..
- HC Packaging Vietnam Company Limited
- Starprint Vietnam Joint Stock Company
- Nippon Paper Industries Co., Ltd.
- Box-Pak (Malaysia) Bhd.
- Lee & Man Paper Manufacturing Ltd.
- Sai Gon Paper Corporation
- Dong Hai Ben Tre Joint Stock Company
- Nine Dragons Paper (Holdings) Limited
- Rengo Co., Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Booming e-commerce parcel volumes
- 4.2.2 Rapid FMCG and electronics off-shoring into Vietnam
- 4.2.3 Plastic phase-out regulations
- 4.2.4 Foreign brand owners' Scope-3 carbon cuts push lightweight recycled board
- 4.2.5 Rise of social-commerce micro-fulfilment in tier-2 cities
- 4.2.6 Tax-incentivised investments in high-speed digital printing lines
- 4.3 Market Restraints
- 4.3.1 Structural shortfall of domestic virgin fibre; import dependence
- 4.3.2 Volatile recovered-paper import policy and quality controls
- 4.3.3 US/EU trade actions on wood products tighten pulpwood feedstock
- 4.3.4 Industrial power-tariff hikes squeeze SME corrugators
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Grade
- 5.1.1 Cartonboard
- 5.1.1.1 Solid Bleached Sulphate (SBS)
- 5.1.1.2 Solid Unbleached Sulphate (SUS)
- 5.1.1.3 Folding Boxboard (FBB)
- 5.1.1.4 Coated Recycled Board (CRB)
- 5.1.1.5 Uncoated Recycled Board (URB)
- 5.1.1.6 Other Cartonboard Grades
- 5.1.2 Containerboard
- 5.1.2.1 White-top Kraftliner
- 5.1.2.2 Other Kraftliners
- 5.1.2.3 White-top Testliner
- 5.1.2.4 Other Testliners
- 5.1.2.5 Semi-chemical Fluting
- 5.1.2.6 Recycled Fluting
- 5.1.3 Other Grades
- 5.1.1 Cartonboard
- 5.2 By Product
- 5.2.1 Folding Cartons
- 5.2.2 Corrugated Boxes and Containers
- 5.2.3 Other Products
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Healthcare
- 5.3.4 Personal Care
- 5.3.5 Household Care
- 5.3.6 Electrical and Electronics
- 5.3.7 Other End-User Industries
- 5.4 By Packaging Format
- 5.4.1 Rigid (Corrugated, Solid Board)
- 5.4.2 Semi-rigid (Folding Cartons excluding Solid Board Boxes)
- 5.4.3 Flexible Paper (Sachets, Wraps)
- 5.4.4 Molded Fiber and Pulp Packaging Products
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 SONG LAM Trading & Packaging Production CO., Ltd
- 6.4.2 Asia Pulp & Paper Group (APP)
- 6.4.3 Tetra Pak International S.A.
- 6.4.4 Oji Interpack Vietnam Co., Ltd
- 6.4.5 Khang Thanh Manufacturing CO., LTD
- 6.4.6 Hanh Packaging Co. Ltd
- 6.4.7 SCG Paper Public Company Limited
- 6.4.8 BINH MINH P.A.T CO.,LTD
- 6.4.9 Kraft of Asia Paperboard & Packaging Co., Ltd..
- 6.4.10 HC Packaging Vietnam Company Limited
- 6.4.11 Starprint Vietnam Joint Stock Company
- 6.4.12 Nippon Paper Industries Co., Ltd.
- 6.4.13 Box-Pak (Malaysia) Bhd.
- 6.4.14 Lee & Man Paper Manufacturing Ltd.
- 6.4.15 Sai Gon Paper Corporation
- 6.4.16 Dong Hai Ben Tre Joint Stock Company
- 6.4.17 Nine Dragons Paper (Holdings) Limited
- 6.4.18 Rengo Co., Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


